Car Loan Default & Vehicle Seizure by Bank: Legal Rights & Protection
Facing auto loan default and cars repossession threats? Learn Supreme Court protections under ICICI Bank vs Prakash Kaur. Pre-sale notice mandates. And bank One-Time settlement solutions.
- Supreme Court ruling: In ICICI Bank v. Prakash Kaur (2007).The Supreme Court banned musclemen repossession without due court process.
- Hypothecation Ownership: Section 51 Motor cars Act creates a money charge. But ownership remains with the client.
- strict Cure Notice: Lenders must serve a 15 to 30 day demand cure notice before initiating repossession.
- Compulsory stock Sheet: Repossessing agents must provide a signed stock of cars contents and physical condition.
- Pre-Sale Valuation Notice: Banks cannot auction cars without serving a pre-sale notice with certified surveyor valuation.
- Criminal Penalties: Highway intercept towing constitutes criminal trespass (Section 329 BNS) and extortion (Section 308 BNS).
- Civil Court Injunction: clients can obtain status-quo stay orders under Section 9 hearing Act against seizure.
- Structured OTS relief: An bank OTS waives 40% to 55% of penal interest with an full No Dues letter.
RBI Guidelines on Vehicle Seizure for Hypothecated Assets
When a client defaults on an auto loan. Banks and NBFCs often deploy third-party claims firms that unlawfully threaten on-the-spot cars lifting or intercept drivers on highways. Under the. RBI Master Circular on Loans and Advances. and the Fair Practices Code for Lenders.Financiers are bound by strict legal steps before taking takeover of any hypothecated movable home.
The 5 Mandatory Steps Lenders Must Follow to Seize a Vehicle.
Formal 30–60 Day Demand Notice
The lender must serve a registered demand cure notice giving 15 to 30 days (or 60 days under Section 13(2) SARFAESI Act for eligible NBFCs) detailing the exact overdue main loan and default computation.
Police & Local Authority Intimation
Before touching the asset. Claims agents must provide written intimation to the local police station having police area over the cars’s location to avoid criminal breach of peace.
Restricted Daylight Hours Only
Visits and seizure actions can only occur between. 7:00 AM and 7:00 PM. at the client’s residence or workplace. Seizing a car on the highway or in transit is strictly illegal.
Mandatory Signed Inventory Sheet
agents must produce an on-spot stock report detailing odometer reading. Exterior body scratches. Fuel level. Private belongings. Signed by the client and witnessing agents.
Pre-Sale Valuation & 14-Day Redemption Period
Once in yard custody. The cars cannot be auctioned promptly. Lenders must issue a certified surveyor valuation report and allow the client at least 14 to 30 days to redeem the cars or settle the debt before any public auction.
ICICI Bank Ltd. v. Prakash Kaur (2007) 2 SCC 711: The Hon'ble Supreme Court reprimanded banks for hiring claims musclemen and held: ". Banks should resort to steps recognized by law to take takeover of cars. the practice of hiring musclemen must be stopped.".
Citigroup Inc. v. Gopalakrishna (2009): The High Court affirmed that taking takeover by force. Road interception. Without providing an stock copy amounts to criminal trespass and theft under penal law.
1. Debt Economics and NPA Dynamics in Auto Loan Defaults
Auto loans in India operate under hypothecation pacts governed by the Indian Contract Act. 1872 and registered under Section 51 of the Motor cars Act. 1988. While the financier maintains a charge on the asset. The client remains the registered owner. cars are rapidly depreciating assets whose market value declines sharply each quarter.
When loan installments remain unpaid. Accounts progress through RBI Special Mention Account stages: SMA-0 (1-30 days). SMA-1 (31-60 days). SMA-2 (61-90 days). Beyond 90 days past due. Loans become Non-Performing Assets (NPA). Under Basel III rules. Banks must set aside heavy cash provisions for NPAs. Because seized cars in storage yards rapidly deteriorate. Lenders have strong trade incentives to settle One-Time deals (OTS).
2. Auto Loan Settlement Math: Deconstructing Car Loan Penal Charges
When auto loans default. Gross bank claims swell from compounding interest. NACH bounce charges. Legal fees. Yard parking costs. A audits isolates genuine main loan from ancillary penalties. This lets deep waivers during One-Time settlement (OTS) talks:
Upon RTGS payment of ₹3,85,000. The bank issues an formal settlement Sanction Letter. Full No Dues letter. RTO Form 35 to release hypothecation.
3. Vehicle Resolution Matrix: Loan Settlement vs Repossession
Evaluating available auto loan relief routes is critical to prevent distress asset loss. This matrix compares key trade-offs across five avenues:
| Route | Waiver | Possession | Speed | NDC & Form 35. | CIBIL |
|---|---|---|---|---|---|
| One-Time settlement. | 40% to 55% | Retained / Redeemed. | 30-45 Days | Complete NDC | Settled |
| Restructuring | Zero Waiver | Retained + Interest. | 60-90 Days | Pending EMIs | Restructured |
| Court lawsuits. | None | Contested | 2-5 Years | Pending Decree | Suit Filed |
| Lok Adalat | 25% to 40% | Mutual Terms | Quarterly | Civil Award | Settled |
| Inaction / Seizure. | Distress Sale | Illegally Seized. | Ongoing Stress | Residual Debt | Repossessed |
4. CIBIL Algorithm: Auto Loan Scoring and Credit Rebound
Credit bureaus calculate scores across five pillars: payment History (35%). Credit use (30%). Credit Age (15%). Credit Mix (10%). Inquiries (10%). Defaulting triggers cascading 30 to 90+ DPD notations. Lowering scores by 80 to 140 points.
Executing an formal OTS updates bureau records to ". Settled". With zero balance. Stopping recurring monthly negative marks. With an full No Dues letter. A secured credit builder card. Disciplined payments. Clients recover scores above 750 within 12 to 24 months. Erroneous reporting can be corrected under Section 21 of CICRA. 2005.
Visual Defense Blueprint: 6-Stage Vehicle Repossession Defense
Review our visual roadmap outlining legal client protections against unlawful cars repossession and bank OTS deals workflows:
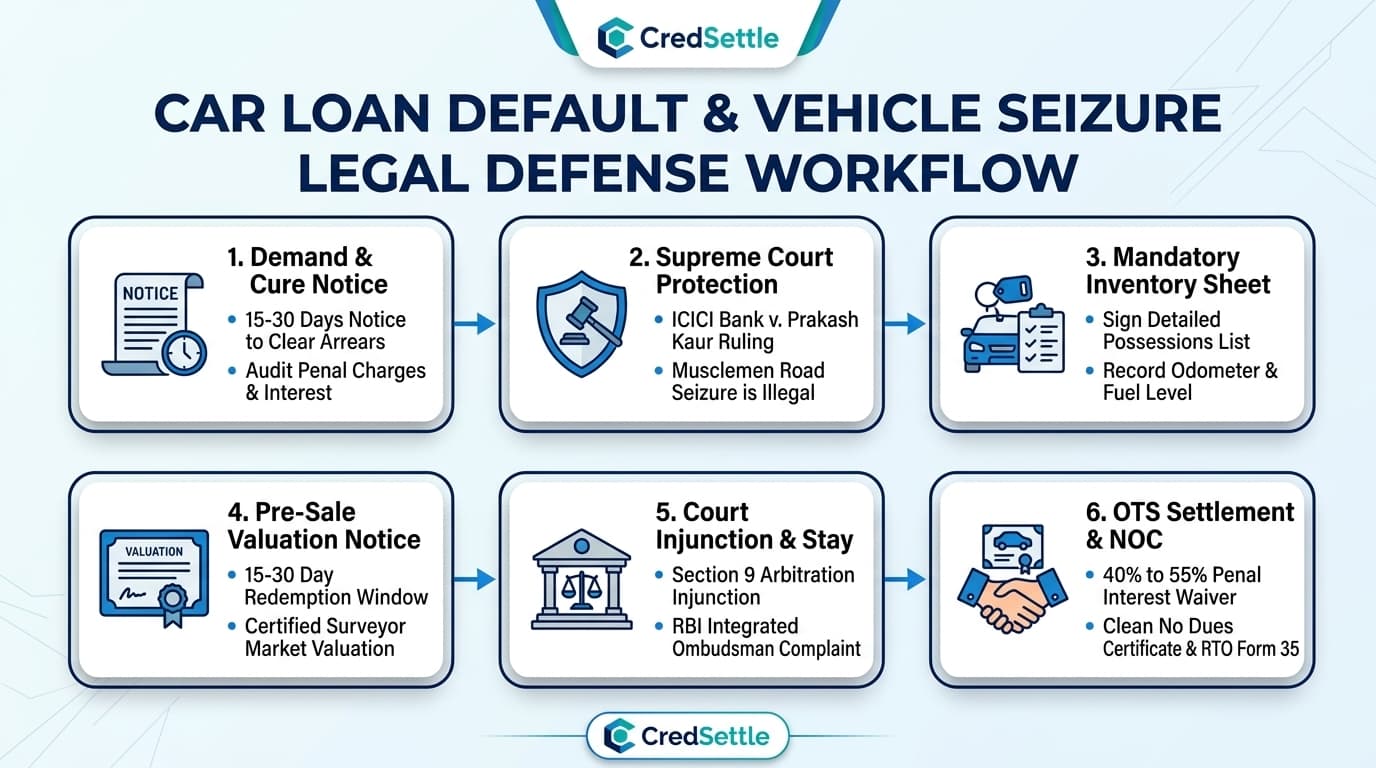
5. Step-by-Step SOP: 6-Stage Vehicle Settlement Process
CredSettle implements a structured Standard Operating steps to halt coercive claims tactics and settle straight with bank credit boards:
Legal audit of loan contracts and notices to identify illegal penalty charges. Unlawful towing fees. Verify whether strict RBI pre-repossession notices were served.
Compiling distress paperwork alongside an independent certified surveyor valuation report establishing realistic cars distress value for settlement discussions.
Formal legal help before the bank Credit boards and main loan Nodal agents. Asserting legal protections against claims musclemen under Supreme Court rules.
Negotiators engage the bank claims desk to secure 40% to 55% waivers on penal interest. Late fees. Yard parking expenses matched to client capacity.
Vetting the bank settlement Sanction Letter to confirm exact account details. OTS deal waiver terms. Binding commitments regarding hypothecation removal.
Direct payment to the bank loan account via RTGS. Followed by issuance of the full No Dues letter. RTO Form 35. Credit bureau closure.
6. Statutory Notice Defense: Analyzing Legal Provisions & Remedies
When auto loans enter default. Lenders serve legal notices to exert pressure. Understanding these provisions enables an effective legal defense:
Penalizes bounced electronic mandates. Lenders must issue notice within 30 days. Proving absence of fraud or active talks provides an effective legal defense.
Under Supreme Court rulings. Undated pledge cheques collected at loan disbursement cannot be presented for inflated amounts without prior reconciliation.
Unilateral arbitrator appointments by lenders are legally invalid. clients can seek interim stay orders under Section 9 hearing Act against cars repossession.
For claims over ₹20 Lakhs before DRT. Lenders must strictly comply with the RBI Fair Practices Code prohibiting client abuse and threats.
7. 3-Tier Grievance Redressal Matrix for Auto Loan Defaults
If claims agents violate RBI rules through abuse. Abusive calls. Repossession threats. Clients can escalate through three RBI tiers:
Grievance Redressal Officer
Submit formal written reports with call logs demanding cessation of rogue agent visits.
Principal Nodal Officer
Escalate unresolved reports to apex nodal agents citing RBI debt claims directions.
RBI Integrated Ombudsman
Lodge online reports on cms.rbi.org.in for RBI reprimand and claims relief.
8. Chronological Timeline Table: The 6-Month Procedural Lifecycle
Auto loan claims relief follows a predictable procedural sequence from default to final settlement:
| Phase | Status | Bank Strategy | Legal Step |
|---|---|---|---|
| Days 1 - 30 | SMA-0 | SMS alerts, soft calls. | Review payment plan. |
| Days 31 - 90 | SMA-1 &. SMA-2. | Agent calls, threat letters. | Serve Cease &. Desist notice. |
| Days 91 - 120 | NPA Asset | Demand &. hearing notices. | Initiate Credit boards OTS. |
| Days 121 - 150 | Provisioning Window. | Pre-sale notices, legal filings. | Finalize OTS deal terms. |
| Month 5 - 6 | Settled Account | Sanction letter issued. | Pay OTS. Get NDC &. Form 35. |
9. Specialized Real-World Scenarios: Complex Auto Loan Disputes
Auto loan defaults occur in various situation. CredSettle resolves complex claims scenarios across client categories in India:
Commercial Fleet Defaults
Fleet operators with cars hypothecated across NBFCs receive legal safety against highway intercepts. Helping structured multi-cars deals.
Executive Luxury Cars
workers with premium car loans facing unexpected layoffs receive strategic talks support. Securing waivers to help dignified redemption or surrender.
Total Loss Insurance Disputes
When accident-damaged cars face cover claim delays while banks demand EMIs. CredSettle coordinates claim settlement and shortfall waivers.
ARC Debt Assignments
When defaulted auto loans are sold to Asset Reconstruction Companies under SARFAESI Section 5. We enforce strict compliance with RBI claims codes.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
FAQs: Auto Loan Default and Vehicle Repossession Rules
Clear. Authoritative answers to the most critical legal and money questions surrounding car loan defaults. Repossession steps. client protections in India:
Statutory Citations & Authoritative Sources
CredSettle legal commentary and defense plans are strictly rooted in Indian statutes. Judicial rulings. RBI rules:
Key Judicial Precedents & Statutory Codes
- Supreme Court: ICICI Bank Ltd. v. Prakash Kaur (2007) 2 SCC 711. (Ban on musclemen).
- Motor cars Act, 1988: Section 51 (Motor cars hypothecation provisions).
- Reserve Bank of India: Master Direction on outside work and Debt claims Codes.
- Bharatiya Nyaya Sanhita, 2023: Sections 303 (Theft). 308 (Extortion). 329 (Trespass). 351 (threats).
- CICRA, 2005: Section 21 (claims relief and rectification of credit information).