
1. Introduction to Loan Settlement in India
Loan closure. commonly referred to in Indian banking as a One-Time closure (OTS) or deal closure. is a by law recognized process where a clients unable to service their debt negotiates with a lender (bank or NBFC) to pay an agreed lump-sum amount lower than the total ledger balance. Upon realization of this agreed amount. The lender forgives the residual balance and considers the debts fully discharged.
In India. Loan closure is not a legal right of default. It is a money and legal relief mechanism intended for individuals and firms experiencing checked. Irreversible money hardship such as job end. Key illness. Demise of an earning member. trade insolvency.
key Terminological Distinctions:
- Loan closure vs Loan payment: In standard payment. The clients pays 100% of the main sum and accrued rates as per the loan schedule. In closure. The bank waives a portion of main sum and penal rates. Closing the account with a partial payment.
- Loan closure vs Loan Waiver: A loan waiver is typically a government-subsidized scheme (such as agricultural debt relief) where the government reimburses banks. In a loan closure. The private lender voluntarily takes a trade loss (haircut) based on its own claims calculations.
- Loan closure vs Loan Restructuring: Restructuring adjusts loan tenures. Lowers rates rates. adds a EMI freeze without forgiving main sum dues. closure permanently extinguishes the loan account with a one-time discounted payment.
Loan Settlement Assessment
Answer 2 simple questions to check your settlement eligibility.
2. How Loan Settlement Works: Step-by-Step Procedure
A standard deal closure does not occur overnight. It progresses through a structured RBI sequence governed by the lender&apos. s internal claims Policy and RBI circulars:
Dues &. Hardship Assessment
Thorough audit of actual main sum. Normal rates. Penal charges. Assembly of incontrovertible medical. Employment. revenue loss records.
Formal Representation
Submitting a formal hardship letter and deal proposal to the bank branch or Stressed Asset claims Branch (SARB) offering a realistic lump-sum.
board talks
Bank&apos. s internal closure Advisory board evaluates liquidation value vs legal claims costs and issues terms.
Written closure Sanction
Lender issues a formal written approval letter specifying the agreed sum. Due dates. closure clauses.
Payment Execution
wire transfer executed strictly via authorized banking channels (NEFT/RTGS/valid payment gateway) credited straight to the loan account.
NOC &. desk Update
Lender issues a No Dues letter (NOC) and reports the account as &apos. Settled&apos. To CIBIL. Equifax. Experian. CRIF High Mark.
5-Step Loan steps in India
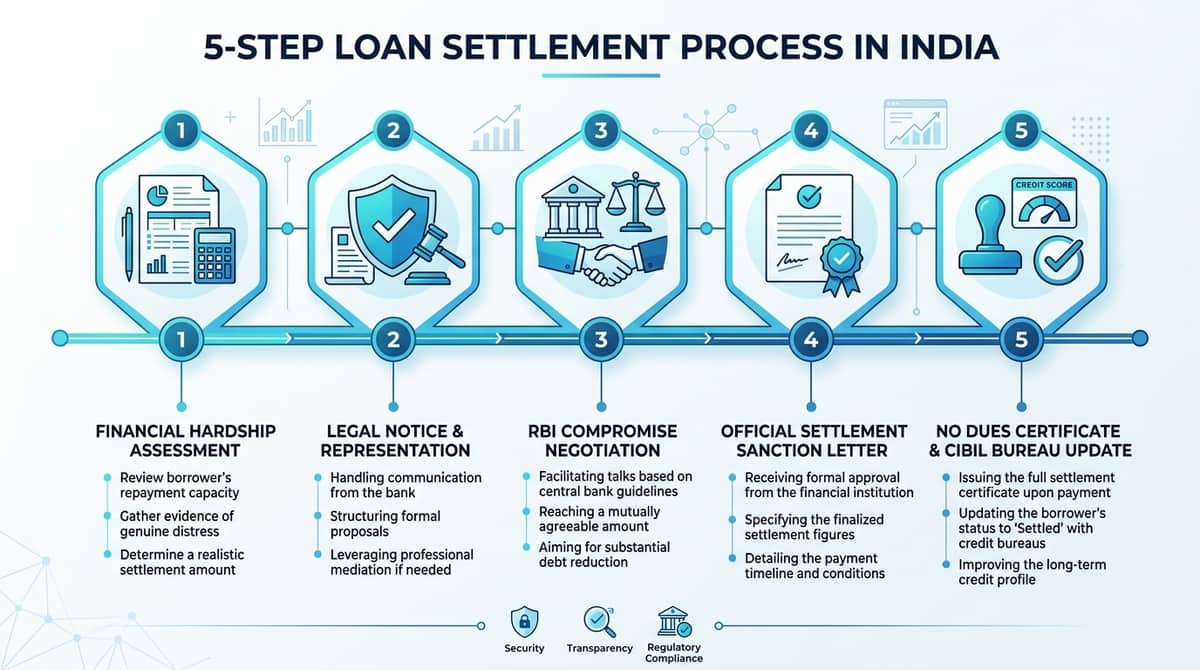
Infographic: Complete legal and procedural sequence for deal loan closure under RBI guidelines.
3. Who Can Opt for Loan Settlement? Eligibility Realities
Banks and NBFCs in India do not grant deal closures simply upon request. Lenders conduct care to distinguish between a genuine distressed clients and a willful defaulter.
Lenders actively consider closure applications under the following hardship:
- Loss of Employment or Primary Income: forced layoff, downsizing. company shutdown supported by end letters and non-salary bank statements.
- dire Medical Emergencies: Life-threatening illnesses. Major surgeries. prolonged treatments of the clients or direct dependents that consumed family savings.
- firm Failure &. trade Distress: Micro, small. Medium enterprise (MSME) closure. Loss of key contracts. insolvency.
- Excessive Debt-to-Income (DTI) Overload: When total monthly EMI debts exceed 80% to 100% of demonstrable monthly take-home earnings.
- Prolonged Default (NPA Classification): Accounts in Non-Performing Asset (NPA) status for 90 days or longer where claims prospects through normal calls are bleak.
4. Types of Loans That Can Be Settled in India
The viability of a loan closure depends heavily on whether the underlying loan is clean or secured.
| Loan Category | Collateral Status | Settlement Feasibility | Typical Haircut / Waiver |
|---|---|---|---|
| Credit Card Dues | clean | Very High | 40%. 70% of total balance (waiver of penal charges + rates) |
| own Loans | clean | High | 30%. 60% of total ledger balance |
| NBFC / Instant App Loans | clean | High | 40%. 65% depending on platform and vintage |
| clean firm Loans | clean / own Guarantee | Moderate to High | 25%. 50% subject to money audit |
| Vehicle / Auto Loans | Secured (Hypothecated Vehicle) | Conditional | closure generally limited to deficiency balance post-repossession |
| Home Loans / Mortgages | Secured (Immovable home) | Very Low | Lenders invoke SARFAESI Act to auction home rather than give large haircuts |
5. Loan Settlement vs Loan Restructuring
clients in distress must evaluate whether to seek a loan restructuring or a deal closure. Both address default risk. their money workings and desk repercussions are fundamentally different.
| Parameter | Loan Restructuring | Loan Settlement (OTS) |
|---|---|---|
| main sum payment | 100% of main sum is repaid over extended time | Bank waives a portion of main sum and charges |
| Loan Account Status | Remains active with revised EMI schedule | Account is permanently closed |
| Payment Mode | Extended monthly EMIs with lowered rates | Single lump-sum or 2. 4 short structured installments |
| CIBIL desk Reporting | Tagged as &apos. Restructured&apos. | Tagged as &apos. Settled&apos. or &apos. Post Write-Off Settled&apos. |
| Best Suited For | Temporary liquidity drops with intact earning capacity | Permanent earning impairment or severe insolvency |
6. RBI Guidelines on Compromise Settlements & Technical Write-offs
On June 8, 2023The Reserve Bank of India issued its landmark circular DOR.STR.REC.20/21.04.048/2023-24 entitled ". Framework for deal closures and Technical Write-offs". Reinforcing uniform standards across all Regulated Entities (REs):
Source: Reserve Bank of India. Department of rule. Central Office. Mumbai.
7. RBI Guidelines for Recovery Agents: Calling Hours & Rules
Under RBI Master Directions (including Circular RBI/2022-23/108 and unified Fair Practices Codes). The Reserve Bank strictly regulates debt calls. Banks and NBFCs remain vicariously liable for unlawful actions taken by their outsourced claims firms.
Permitted claims Practices
- Calling clients strictly between 8:00 AM and 7:00 PM.
- Verifying clients identity before discussing unpaid loan details.
- Agents carrying valid bank authorization letters and photo identity cards.
- Maintaining experts call recordings and contact audit trails.
Strictly Prohibited unlawful Conduct
- Initiating claims contacts outside the permissible 8:00 AM to 7:00 PM legal window.
- Resorting to false. Abusive. emotionally threaten remarks during calls.
- Contacting friends. Relatives. Neighbours. workplace employers.
- Visiting residence/workplace without prior notice or creating public scenes.
- Falsely claiming to be police heads. Court bailiffs. CBI officials.
8. How Much Can a Loan Be Settled For? The Mathematics of OTS
One of the most persistent myths in Indian debt relief is that there is a standard ". flat 50% discount". or guaranteed waiver rate. There is no legal flat rate. Every deal payout sum is calculated on a risk-claims matrix governed by the following factors:
- main sum vs Penal Charges Composition: Banks are far more willing to waive 100% of accumulated penal rates and late fees than their core disbursed main sum.
- Age of Default (NPA Vintage):
• SMA-0 to SMA-2 (0-90 days): Banks rarely consider closures. they push for full claims or restructuring.
• Sub-standard Asset (NPA 3. 12 months): deals typically range between 55% to 75% of total dues.
• Doubtful / Loss Asset (NPA >. 12 months): deals often range between 30% to 50% of the total balance because the bank has already made 100% provisioning in its books. - Demonstrable Inability to Pay: Documented zero liquid balance. Frozen accounts. medical debts prove that dragging the clients to civil court will yield zero recoverable assets.
- fast Lump-sum Capacity: A clients ready to transfer ₹3,00,000 within 48 hours will always receive a better OTS sanction than a clients seeking 12 installments.
9. How to Negotiate the Best Loan Settlement Amount
settle with a banking institution requires a disciplined. Evidence-based approach. Shouting at agents or ignoring calls weakens your position. Follow this battle-tested talks playbook:
Step 1: Obtain Complete Statement of Accounts (SOA)
Demand an itemized breakdown of pure main sum unpaid. Normal contractual rates. Penal rates. processing charges. Never settle on a vague &apos. total demand figure&apos. stated verbally over the phone.
Step 2: Establish the Anchoring Offer
Start talks by proposing waiver of 100% of penal charges and 60% of main sum. This anchors the discussion around main sum claims rather than accumulated rates fines.
Step 3: papers Hardship in Writing
Submit a thorough representation letter citing RBI deal Framework guidelines. Detailing health reports or end slips. Demonstrating that your offer is the maximum realizable value.
Step 4: Golden Rule. Never Pay Without Written Sanction
No matter how urgent the agents claims their monthly target isnever transfer a single rupee based on a WhatsApp message or verbal call. Insist on a formal closure note generated from the bank&apos. s centralized system with an valid dispatch number.
10. Legal Rights of Borrowers During Loan Recovery in India
Defaulting on a debt is a civil contractual breach. it is not a crime under Indian law. The Supreme Court of India and the Reserve Bank have repeatedly upheld fundamental legal rights safeguarding clients:
Right to Privacy (Article 21)
Lenders cannot disclose your debt status to your employer. Colleagues. Neighbours. extended family members. Doing so constitutes civil slander and an actionable breach of privacy.
Right Against threats
Repeated calling. Threatening penal incarceration. Shouting at doorsteps. Real stalking is actionable under the Bharatiya Nyaya Sanhita (BNS) / IPC Sections 351. 352. 503.
Right to Due Process &. Notice
Clients are by law entitled to receive prior written demand notices before any legal invocation (Arbitration. Sec 138 NI Act. SARFAESI repossession).
Right to Grievance Redressal
Access to the bank&apos. s main sum Nodal head (PNO) and subsequent escalation to the RBI Integrated RBI officer Scheme (CMS Portal) with mandatory 30-day relief windows.
11. What Legal Action Can a Bank or NBFC Take Against Defaulters?
grasp the distinction between an empty agents threat. A formal counsel&apos. s legal notice. an actual court summons is vital:
12. Legal Complications: Defaulting on a Settlement Agreement
Entering into a deal closure creates a new substituted contract under Section 62 and Section 63 of the Indian Contract Act. 1872. clients must be aware of the severe legal pitfalls if they fail to uphold the terms:
- Revocation of Waiver: Every standard closure Sanction Letter contains a default clause: ". In the event of delay or default in payment of any installment. The closure shall stand cancelled automatically. the bank shall be entitled to recover the entire original dues with retrospective rates.".
- Loss of Partial Payments: If you agree to settle for ₹3 Lakhs in 3 installments of ₹1 Lakh each. You pay ₹2 Lakhs but default on the 3rd. The bank typically treats the ₹2 Lakhs as normal partial payment against your original ledger dues and restarts claims for the balance!
- Pending Litigation Re-activation: If Section 138 or arbitration was stayed conditional upon closure payments. The bank can fast resume penal or execution steps before the court.
13. Impact of Loan Settlement on CIBIL & Credit Score
clients must enter closure with complete clarity on how Indian credit information companies (TransUnion CIBIL. Equifax. Experian. CRIF High Mark) record the transaction:
Represents 100% full payment of main sum and rates. Positive credit signal that builds or restores high 750+ CIBIL scores.
Represents account closed via deal haircut. Lowers credit score by 50. 120 points and remains on your desk report for up to 7 years.
Indicates the lender wrote off the debt as bad debt before you paid a deal amount. Severe red flag for tier-1 credit underwriting.
Is a &apos. Settled&apos. status worse than an active NPA? No. An active unpaid default continues to drag your CIBIL score downward month after month with Days Past Due (DPD) counters hitting 900+ days. Invites court cases. guarantees fast rejection. A settled status stops the bleeding and begins the 7-year countdown for credit rehabilitation.
14. What Happens After Loan Settlement? Post-Closure Checklist
Once your closure wire transfer clears the bank&apos. S account. Ensure you complete these four mandatory closing procedures:
- Demand the valid No Dues letter (NDC): The bank is mandated under RBI customer service directives to issue a stamped No Dues letter / Account Closure Letter within 15. 30 days confirming that no further claims survive.
- check Withdrawal of Court Cases: If Section 138 or arbitration notices were filed. Ensure the bank&apos. s counsel files a joint memo of deal or application for withdrawal before the relevant Magistrate or Arbitrator.
- Retrieve Post-Dated Cheques &. Security papers: Ensure the lender cancels NACH e-mandates and returns or destroys any real security cheques deposited at the time of loan payout.
- Check Credit desk After 45 Days: Download an updated CIBIL report 45 to 60 days post-closure to check that the balance unpaid shows zero and the status reflects &apos. Settled&apos. rather than active default.
15. Can You Get a Loan After Settlement? Rebuilding Creditworthiness
While prime banks will reject clean loan applications fast following a closure. You can systematically rebuild your credit score using this proven 3-phase pathway:
Open a fixed deposit (FD) of ₹25,000 to ₹50,000 with a bank (e.g. IDFC First WOW. Kotak 811 Dream Different. SBI Unnati) and obtain a secured credit card backed 100% by the FD. Use no more than 20% of the limit and repay the bill in full 5 days before the due date.
Consistent. On-time payments on your secured card generate running &apos. 000&apos. (paid on time) monthly records on CIBIL. Your score typically climbs from the low 600s back into the 700. 740 range.
Apply for entry-level consumer durable loans or gold loans. Once 36 months pass with zero fresh delinquencies. Secondary NBFCs and fintech lenders will readily approve fresh own credit.
16. Recovery Agent Harassment: How to Legally Defend Yourself
agents threats is the most painful ordeal for defaulting clients. If calls agents are crossing legal boundaries. Execute these fast defensive defenses:
- Enable Call Recording: Maintain an automatic audio recorder on your phone. Inform calling agents: ". This call is being recorded for evidence under RBI circular DOR.ORG.REC.65/21.04.158/2022-23.". This statement alone discourages 80% of harsh threats.
- Send a Formal Cease &. Desist Letter: Issue a registered legal notice to the bank&apos. s managing director and collections head demanding that third-party agents fast cease calling illegal numbers or visiting your workplace.
- Lodge a Complaint with the main sum Nodal head (PNO): Every bank has a designated PNO. Send the call audio. Agent phone numbers. WhatsApp screenshots. Under RBI rules. The bank must acknowledge within 24 hours.
- Escalate to the RBI Banking RBI officer (CMS Portal): If the threats does not halt within 30 days. File an online grievance on cms.rbi.org.in. The RBI officer can award compensation up to ₹20 Lakhs for mental anguish and threats.
17. Comprehensive Document Checklist for Loan Settlement
Having an organized dossier of hardship proof speeds up the bank&apos. s closure board approval:
KYC &. Loan Records
✓ PAN Card &. Aadhaar Card
✓ Latest Loan Account Statement (showing dues)
✓ Loan Sanction Letter / Credit Card pacts
✓ thorough CIBIL / Experian Credit Report
money Inability Proof
✓ Last 6 to 12 months Bank Statements (all active accounts)
✓ Job end Letter / Resignation / Salary Slips
✓ firm Closure letter / GST Surrender (for MSMEs)
✓ Hospital discharge summaries &. medical treatment bills
18. How to Verify a Genuine Settlement Offer & Avoid Scams
Thousands of Indian clients are defrauded each month by rogue claims telecallers and scammers sending forged closure letters on PDF templates. Use this 4-step checklist to check authenticity:
@hdfcbank.com, @icicibank.com, @sbi.co.in). Never accept letters from Gmail, Yahoo, or generic Outlook addresses.19. Common Loan Settlement Mistakes That Cost Borrowers Lakhs
- Relying on Verbal Promises of agents: Agents under target pressure often say: ". Just pay ₹50,000 today and the bank will close the card.". If you pay without a closure note. The bank treats it as partial rates claims and demands the rest next week!
- Ignoring Court Summons &. Legal Notices: Thinking that avoiding notices makes them disappear. Failing to appear in Section 138 or arbitration steps results in bailable/non-bailable warrants or ex-parte awards that freeze your bank accounts.
- Borrowing from Informal Loan Sharks to Settle: Taking a high-rates private loan (5%. 10% monthly rates) to settle a 14% bank loan creates a fatal debt vortex.
- Forgetting to Demand the No Dues letter (NDC): Assuming payment receipt is the same as an NOC. Without an valid NOC. Old calls firms may resurface years later demanding residual dues.
20. Practical Settlement Case Studies & Financial Breakdowns
Examine these real-world examples demonstrating how deal closures are settle across different loan portfolios:
clients Profile: IT experts terminated during tech layoffs.
Original Sanction: ₹8,00,000 | Total unpaid: ₹9,40,000 (with fines)
main sum Balance: ₹6,20,000 | Default Vintage: 11 Months NPA
settle closure: ₹3,80,000 in two installments.
Total Waiver: ₹5,60,000 (~60% of total ledger dues)
clients Profile: Retail shop owner with pandemic firm collapse.
Dues Across 3 Cards: ₹5,20,000 (main sum: ₹2,40,000 + ₹2,80,000 Finance Charges)
Default Vintage: 14 Months
settle closure: ₹1,90,000 total lump-sum payment.
Total Waiver: ₹3,30,000 (Waiver of 100% fines + ₹50,000 main sum haircut)
21. Loan Settlement Costs and Professional Legal Assistance
When evaluating experts debt closure and legal representation services in India. Transparency in fee structures is paramount:
- Direct payout sum (Paid to Bank): The settle deal sum paid straight to the lending bank or NBFC.
- experts Legal &. Representation Fees: Reputable legal advisory firms operate either on a transparent milestone retainer or a success-fee rate based on the checked money saved for the clients.
- No Upfront Hidden Charges: Legitimate firms never demand full upfront contingency fees before settle with the bank. Ensure you receive a formal service contract specifying exact deliverables. Legal notice drafting. anti-threats coverage.
22. Interactive Loan Settlement Calculator / Estimator
Estimate a realistic One-Time closure (OTS) deal band based on your main sum. Accumulated charges. default duration under standard Indian banking claims parameters:
*Disclaimer: This estimator provides statistical approximations based on standard RBI deal trends and NPA aging. Actual deal sanctions depend solely on the concerned bank or NBFC Board-approved deal policy and closure board approval.
23. Legal Remedies & When to Seek Advocate Representation
While simple default talks can sometimes be initiated straight by clients. Legal representation becomes crucial in the following hardship:
- Receipt of Section 138 NI Act or Section 25 PSSA Notice: A formal legal reply drafted by a practicing counsel must be served within the legal period to set up your defense and prevent summary conviction.
- Notice of Arbitration: Objecting to unilaterally appointed sole arbitrators and filing applications under Section 11. 12. 16 of the Arbitration and Conciliation Act 1996.
- Unlawful threats &. Blackmail: Issuing formal Cease &. Desist notices. Penal complaints under BNS/IPC. initiating injunction steps before Civil Courts against unlawful workplace visits.
- Drafting Watertight closure Contracts: Reviewing the bank&apos. s closure note to ensure it does not contain hidden clauses that keep own guarantees or co-clients debts alive.
24. Comprehensive Loan Settlement FAQs (20 Essential Q&As)
Answers to the most key legal. Operational. money questions regarding loan closure in India:
25. Conclusion: Your Action Plan for Financial Freedom
Loan closure is a viable. By law protected exit route for honest clients overwhelmed by uncontrollable economic distress. It shields your mental sanity. Halts harsh claims threaten. formally liquidates crushing debts.
yet. Closure must never be entered into impulsively or without proper legal proof. Always demand written closure sanction letters. Check authorized bank payment channels. Insist on your No Dues letter. commit to a structured 24-month credit rebuilding roadmap.
Don&apos. t Fight the Bank Alone
At CredSettle. Our team of seasoned counsel and banking relief specialists safeguard your rights under RBI guidelines. Stop agents threats fast. settle the highest possible legal waiver for your loans.
RBI &. Legal Attribution: Content authored and maintained in compliance with Reserve Bank of India (deal closures and Technical Write-offs Framework 2023. Circular DOR.STR.REC.20/21.04.048/2023-24) and Banking rule Act. 1949.
Disclaimer: The contents of this master guide are published for informational purposes and do not constitute formal lawyer-client advice until a legal representation pacts is formally executed.