What Happens If You Default on a Settlement Agreement? (OTS Guide)
Understand legal and financial results of missing an agreed OTS installment. Learn how revocation clauses revive waived interest, defend against Section 138/25 notices, and renegotiate terms.
Executive Summary: Settlement Agreement Default Risks
Defaulting on an agreed One-Time Settlement (OTS) triggers immediate contractual and banking repercussions across Indian financial institutions. Legal jurisprudence and RBI regulations govern borrower protections and restructuring pathways:
1. Debt Economics: Mechanics of a Settlement Default
When a borrower executes a One-Time Settlement (OTS) with a bank or NBFC, the agreement operates as a conditional compromise governed by the Indian Contract Act, 1872. The lending institution agrees to waive large interest and principal only on the strict condition that all installment tranches are paid exactly on schedule. If an agreed date is missed, the conditional agreement is breached, triggering the automatic revocation clause embedded in the sanction letter.
Under Reserve Bank of India prudential norms, the loan facility remains an active Non-Performing Asset (NPA) throughout the settlement period until the final tranche clears. When default occurs, the lender reverses proposed accounting write-offs and reinstates the entire gross claim. Because unsecured debts lack collateral under the SARFAESI Act, banks face costly 3 to 5 year litigations in civil courts or Debt Recovery Tribunals. as a result, institutional credit committees are commercially open to evaluating fresh compromise proposals before initiating aggressive legal action.
2. Financial Breakdown: Settlement Revocation Math
Defaulting on an OTS exposes borrowers to immediate balance inflation. Lenders retroactively reinstate waived penal interest (24% to 36% compound annual rates), mandate bounce surcharges. Legal recovery costs. also, money paid in prior tranches is reallocated toward interest rather than reducing settlement principal.
agent Settlement Default Math (₹10 Lakh Facility).
Revocation Impact.Gross claim inflated to ₹10,00,000 with penal fees.
Sanctioned into 3 monthly tranches of ₹1,16,666.
Cleared successfully on Day 1.
Waiver revoked; prior payment credited to penal interest.
By submitting a formal hardship dossier within the grace period, borrowers can preserve prior remittances and revalidate the 50% waiver under a revised sanction letter.
3. Strategic Options: Settlement Default vs Alternatives
Evaluating the optimal legal path after a settlement default requires comparing costs and timelines:
| Route | Financial Cost | Legal Impact | Timeline |
|---|---|---|---|
| OTS Default | Full debt + 24%-36% penal fees. | Sec 138/25 notices, arbitration. | 2 to 4 years |
| Renegotiated OTS. | 40%-55% principal (penal waived). | Notices quashed, clean NDC. | 30 to 90 days |
| Restructuring | 100% principal + standard interest. | Standard asset; zero discount. | 2 to 5 years |
| DRT Litigation | Full liability + legal costs. | Summons, hearings, attachments. | 3 to 7 years |
| Lok Adalat | 40% to 60% compromise sum. | Non-appealable consent award. | 1 day hearing |
4. Credit Bureau Impact: CIBIL Scoring Mechanics After an OTS Default
The TransUnion CIBIL scoring model evaluates creditworthiness across five weighted pillars: payment history (35%), credit use (30%), credit history length (15%), credit mix (10%). Recent inquiries (10%). Defaulting on an active settlement agreement severely damages the payment history pillar. Lenders update Days Past Due (DPD) to reflect continuous default and report negative remarks such as 'Suit Filed&apos. Or 'Wilful Default'.
This triggers a rapid credit score drop of 80 to 140 points, pushing scores below 600. However, this impact is reversible. Under Section 21 of the Credit Information Companies (Regulation) Act, 2005 (CICRA), borrowers have the legal right to rectify inaccurate bureau reporting. Completing a renegotiated settlement and securing an authentic No Dues Certificate updates the account to 'Settled&apos. With zero outstanding balance, enabling score recovery within 12 to 24 months.
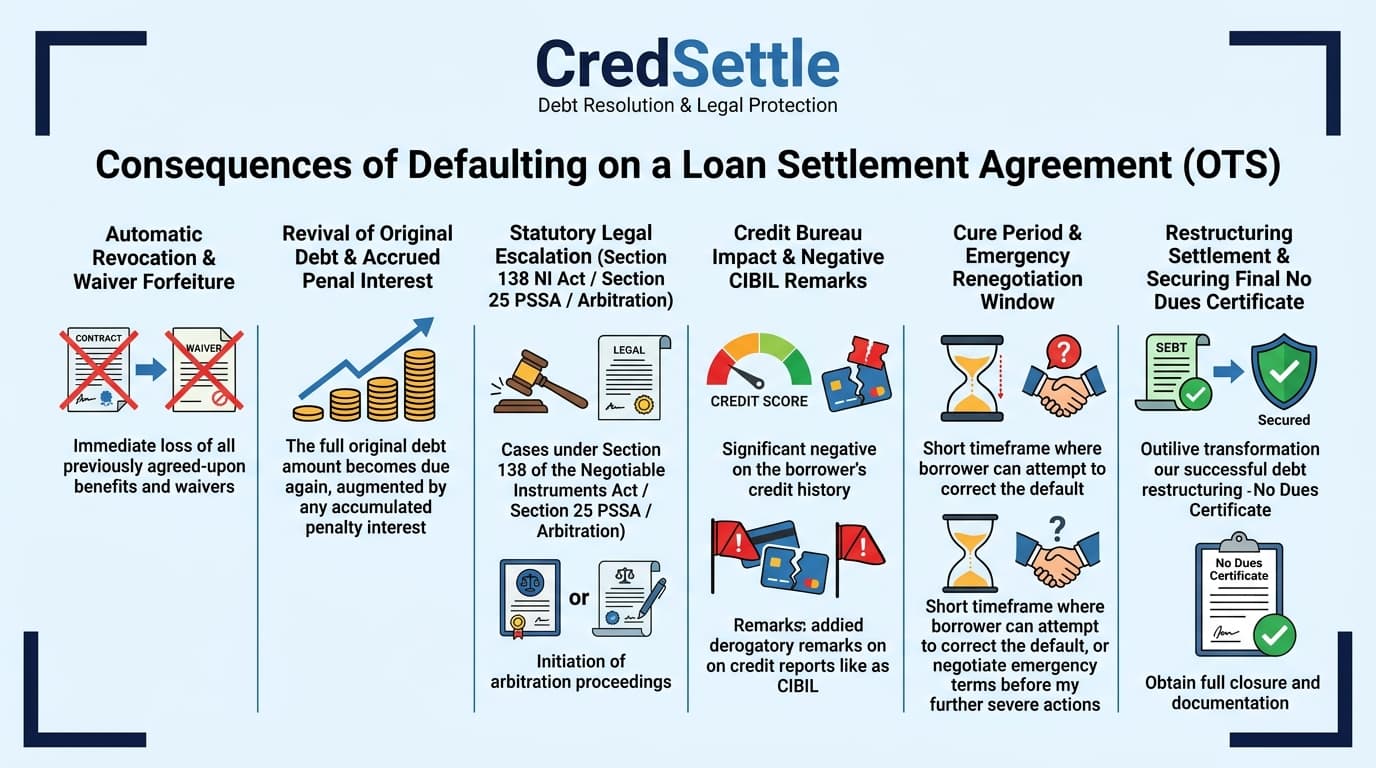
Settlement Default Consequences & Cure Roadmap
Review the 6 core pillars of settlement default results, statutory notice risks, and step-by-step cure procedures:
5. SOP: 6 Stages to Cure Default & Renegotiate Terms
Execute this disciplined 6-stage SOP to cure default triggers, protect prior payments, and revive your settlement agreement:
Forensic Statement Audit & Grace Period Check
Review the sanction letter for 7 to 15 day grace clauses. Calculate exact default shortfalls, isolate uncredited payments, and verify if formal revocation notices have been issued.
Emergency Hardship Dossier Preparation
Compile authentic evidence of default causes. This includes medical summaries, layoff letters, or business bank statements to document genuine cash-flow constraints.
Credit Committee Representation & Cure Notice
Submit a formal settlement preservation petition directly to the Zonal Credit Committee. Bypass aggressive recovery agents and propose a restructured installment schedule.
Bilateral Negotiations for Revised Terms
Negotiate with bank recovery managers. Protect earlier tranche payments from forfeiture by ensuring they credit toward the agreed compromise sum with an extended timeline.
Legal Due Diligence of Revised Sanction Letter
Vet the new settlement letter on official bank letterhead. Ensure it supersedes defaulted terms, waives 100% of penal interest, and guarantees NDC issuance.
Tranche Remittance & Procurement of Final NDC
pay remaining installments directly to your loan account via RTGS/NEFT. Maintain timestamped receipts, verify zero balance in core banking, and obtain your official NDC within 30 days.
6. Statutory Notice Defense: Post-Default Legal Action
Loan settlement default is strictly a civil contractual dispute. Knowing your legal protections ensures secure negotiation:
Issued when electronic mandate debits bounce. Serve a formal legal reply within 15 days proving lack of fraud and active renegotiation.
Applies to bounced security cheques. Offenses are compoundable under Section 147; complaints are quashed upon settlement fulfillment.
Unilateral arbitrator appointments by banks are void ab initio under Supreme Court rulings in TRF Ltd. and Perkins Eastman.
For debts over ₹20 Lakhs. Borrowers can file a written statement disputing penal interest and seek a Lok Adalat compromise.
Borrower Protections Under the RBI Fair Practices Code.
Under the RBI Master Direction on Fair Practices Code, lenders and recovery agents cannot call before 8:00 AM or after 7:00 PM, visit without notice, use abusive language. Contact relatives.
7. The 3-Tier Escalation Framework for Defaulted Settlement Disputes
If a bank recovery department unlawfully cancels compromise terms, escalate through this 3-tier statutory framework:
Submit a formal written petition proposing your revised plan directly to the GRO (7 to 10 days turnaround).
Escalate to the bank's apex PNO if Level 1 fails or if agent harassment persists (14 to 21 days turnaround).
Lodge a complaint on cms.rbi.org.in for unfair settlement cancellations or violations of the Fair Practices Code.
8. Chronological Timeline: Default to Re-Settlement
Follow chronological milestones and legal deadlines from initial installment default to final NDC delivery:
| Milestone | Status | Bank Action | Borrower Strategic Action. |
|---|---|---|---|
| Days 1-15 | Technical Default. | Grace tracking | Exercise grace clause, audit ledger, notify branch. |
| Days 16-30 | Sanction Breach | Revocation warning. | Submit hardship petition, request bilateral meeting. |
| Days 31-60 | Revived NPA | Section 138/25 notices. | Issue legal reply, challenge arbitrator, propose revised OTS. |
| Days 61-90 | Revalidated OTS | Revised terms approved. | Vet revised sanction letter, pay updated down payment. |
| Month 4-5 | Settled / Closed. | Ledger zero-balanced. | Collect official NDC, initiate CIBIL record update. |
9. Real-World Settlement Default Scenarios & Strategic Solutions
Applying tailored negotiation strategies across different borrower profiles ensures protected resolution:
Multi-Lender Portfolio Balancing
Defaulting on multiple loans requires sequencing settlements one by one rather than exhausting funds simultaneously across lenders.
Corporate Executive Layoffs
Submit verified severance paperwork to freeze installment schedules for 60 days without forfeiting prior tranche payments.
MSME Proprietorship Cash Flow
Propose balloon installments aligned with audited quarterly accounts receivable cycles to ensure sustainable payments.
ARC Debt Assignments
Leverage ARC discounted acquisition prices (70%-80% off) to negotiate deep 4 to 6 month restructured settlement terms.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions: Settlement Agreement Defaults
Official Regulatory Citations & Legal References
- RBI: Master Direction on Fair Practices Code for Lenders.
- RBI Ombudsman Scheme 2021: Statutory dispute mechanism on cms.rbi.org.in.
- CICRA 2005 (§21): Credit dispute resolution and bureau remark rectification.
- PSSA 2007 (§25): Dishonour of electronic funds transfer / NACH mandates.
- RDB Act 1993 (§19): Original Applications before Debt Recovery Tribunals (DRT).
- Indian Contract Act 1872: Sections 73 & 74 regarding contractual damages.
- NI Act 1881 (§138 & §147): Cheque dishonour defense and compounding of offenses.