Settle 2 Lakh Personal Loan
Have an unpaid own loan of ₹2 Lakhs? Discover how to settle a legal One-Time closure. Secure a 55% to 70% waiver. Eliminate claims threats. rebuild your CIBIL score.
Defaulting on an clean own loan of ₹2 Lakhs places clients in an anxious position. From an bank perspective. This balance represents one of the most viable loan sizes for securing a deep deal closure in India. Trade banks and Non-Banking money Companies (NBFCs) recognize that pursuing full-scale legal claims through civil summary suits or arbitration tribunals routinely costs upwards of ₹40,000 to ₹60,000 in counsel fees and procedural expenses. When a clients establishes genuine. Documented insolvency caused by unexpected life events. Lenders routinely approve One-Time closures (OTS) between ₹60,000 and ₹85,000. Fully waiving growing penal rates and overdue surcharges.
clients must recognize that an clean own loan default is purely a civil dispute governed by the Indian Contract Act. 1872. With zero risk of penal arrest or police action. Although automated NACH mandate returns may trigger formal demand notices under Section 25 of the Payments and closure Systems Act. 2007. These matters are systematically extinguished upon executing a formal OTS. Furthermore. The Reserve Bank of India Master Directions provide robust anti-threats safety against third-party agents. Making sure that clients can settle with dignity while establishing a structured pathway to rehabilitate their CIBIL score back above 750 within 12 to 24 months.
1. Can You Settle a ₹2 Lakh Personal Loan? The Mid-Ticket Debt Reality
Many clients in India mistakenly assume that debt closure is a mechanism reserved exclusively for massive firm insolvencies or multi-crore firm defaults. In reality, a ₹2 Lakh clean own loan falls into the prime mid-ticket retail bracket where trade banks and Non-Banking money Companies (NBFCs) actively settle One-Time closures (OTS) to avoid protracted legal expenses.
When an individual defaults on a ₹2 Lakh own loan due to legitimate hardship - such as unexpected job loss. Severe medical hospitalization. Salary reductions. small firm collapse - the loan follows a strict bank lifecycle governed by Reserve Bank of India (RBI) prudential norms:
When monthly EMI payments stop. The loan moves through a strictly regulated bank classification cycle established by the Reserve Bank of India. During the first 90 days of overdue status. The account is categorized as a Special Mention Account across SMA-0 (1 to 30 days). SMA-1 (31 to 60 days). SMA-2 (61 to 90 days) buckets. Throughout this preliminary phase. Automated dialers and branch claims desks apply heavy follow-up pressure in an effort to extract overdue EMIs alongside harsh late payment surcharges.
The bank dynamic changes fundamentally on Day 91. Once an account crosses 90 running days past due. RBI prudential norms mandate that the lender classify the loan as a Sub-Standard Non-Performing Asset (NPA). Under banking capital adequacy requirements. The institution must fast lock up between 15% to 100% of the loan value in mandatory balance-sheet provisioning. This provisioning requirement straight impairs the bank&apos. s quarterly liquidity and profitability metrics.
To initiate a formal claims suit under Order 37 of the Code of Civil Procedure or pursue arbitration under the Arbitration and Conciliation Act. 1996. The bank must engage external counsel. Deposit court stamp fees. Fund arbitral court sittings. handle process service expenses. These procedural costs quickly exceed ₹40,000 to ₹60,000 and tie up claims resources for two to four years without guaranteeing full asset realization. Consequently. When a clients presents authentic proof of hardship and offers an upfront cash deal of ₹60,000 to ₹85,000. The bank&apos. s closure desk recognizes that accepting an fast OTS is far more advantageous than spending fresh capital on uncertain litigation.
2. The Financial Breakdown: How Much to Pay for a ₹2 Lakh Settlement?
When you default on a ₹2,00,000 own loan. Banks automatically add harsh compound penal rates. Bounce charges. Cheque return fees. calls expenses. By the time 6 to 12 months pass. The lender&apos. S demand notice might claim ₹2,60,000 to ₹2,95,000.
grasp the mathematical dissection between main sum Balance, Contractual rates. Artificial Penal Add-ons is the key to settle the lowest possible closure figure:
Anatomy of a ₹2 Lakh own Loan Default Claim
Typical 180-Day NPA CaseTargeting 35% to 50% of the true main sum balance with 100% penal fee waiver.
3. Resolution Matrix: Settlement vs Restructuring vs Default
Evaluate the five primary legal and money routes available when managing a defaulted ₹1 Lakh own loan in India:
| Resolution Option | Upfront Cash Needed | CIBIL Status Impact | Legal Harassment Risk | Resolution Timeline | Strategic Verdict |
|---|---|---|---|---|---|
| One-Time closure (OTS) | ₹60,000. ₹85,000 (Lump-sum) | ". Settled". (-75 to -120 pts) | Eliminated (NDC Issued) | 30 to 60 Days | Best for fast money relief and closing bad debt |
| Loan Restructuring / Tenure Stretch | ₹2,00,000 + Extended rates | ". Restructured". (Mild dip) | Eliminated while EMIs paid | 24 to 48 Months | Suitable only if you have stable. Predictable monthly income |
| National Lok Adalat closure | ₹70,000. ₹95,000 (On the spot) | ". Settled via Lok Adalat". | by law Closed (Sec 21 LSA) | 1 Day (Sitting date) | Highly effective if your bank issues a Lok Adalat notice |
| Prolonged Default / Inaction | ₹0 upfront. claims grow | ". Written Off / Suit Filed". (-200 pts) | Severe (Calls. Notices. Visits) | Indefinite (Years) | Worst approach. destroys creditworthiness across all lenders |
| Sale to Asset Reconstruction Co. (ARC) | ₹50,000. ₹75,000 | ". Sold to ARC / Settled". | Moderate (ARC follow-ups) | 6 to 12 Months | High discount potential as ARCs buy debt at 20-30% face value |
4. CIBIL Scoring Math: Impact of ₹2 Lakh Settlement
How exactly does credit desk scoring work when a ₹2 Lakh loan is settled versus left in default? Credit bureaus in India (TransUnion CIBIL. Experian. CRIF High Mark. Equifax) compute credit scores using proprietary algorithms weighted across exact parameters:
Credit desk Algorithm Factor Weights
closure vs Default claims Timeline
The CIBIL Conversion Option: Under Credit Information Companies (rule) Act. 2005 (CICRA §21). You also retain the right to approach the bank in future (once your finances recover) to pay the balance waived amount and convert the CIBIL tag from ". Settled". to ". Closed". Permanently removing any closure stigma.
Visual Defense Blueprint: ₹2 Lakh Personal Loan Settlement Roadmap
Study this thorough 6-stage roadmap detailing the entire trajectory from first loan default to hardship evaluation. Deal talks. Formal sanction. Direct payment. credit rehabilitation:
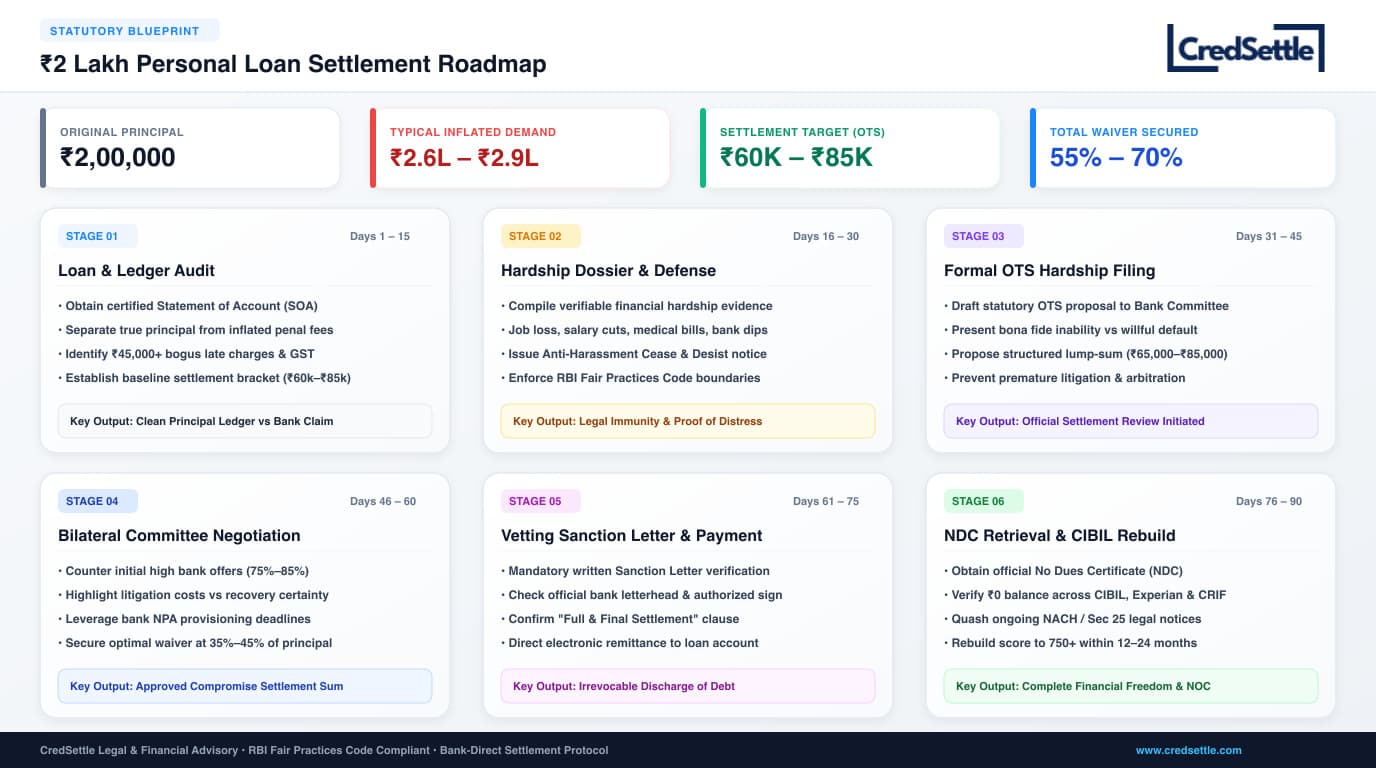
5. 6-Stage SOP: Settle a ₹2 Lakh Personal Loan Legally
Follow this sequential. Battle-tested standard operating procedure executed by CredSettle experts to ensure maximum waiver and complete legal safety:
Loan Audit &. Elimination of Bogus Penal Charges
Request a signed Statement of Account (SOA) from the lender. Reconcile all historical EMIs paid. Isolate the true remaining main sum balance from growing penal fees. calculate your target closure bracket (30% to 50% of the actual remaining main sum).
Hardship proof &. Anti-threats Notice
Compile authentic proof prove your money distress - such as pink slips. Medical discharge summaries. GST returns showing firm downturn. bank statements. If third-party agents engage in illegal contact or threats. Serve an anti-threats cease-and-desist notice under RBI Fair Practices Code.
Formal Hardship Letter &. OTS Proposal Submission
Submit a formal One-Time closure (OTS) proposal straight to the bank&apos. s Legal claims Desk and Credit board. Clearly outline that continuing default is due to genuine inability rather than willful default. Offer a exact lump-sum payout sum (e.g. ₹65,000 for a ₹2 Lakh loan).
Bilateral talks with Internal closure board
Engage in structured counter-talks. When the bank counter-offers 70% or 80%. Present your documented money insolvency. Negotiators leverage bank quarter-end pressure (March. June. September. December) to push the final approved closure figure down to 35%. 45% of main sum.
Vetting the Written closure note &. Direct Bank wire transfer
NEVER pay without a formal closure Sanction Letter. check that the letter is on valid bank letterhead. Signed by an authorized manager. Explicitly specifies your loan account number. States the exact payout sum. Mentions ". Full and Final closure". gives a clear payment deadline. Remit funds strictly into your loan account via RTGS/NEFT.
No Dues letter (NDC) Retrieval &. CIBIL Record Update
Collect the valid No Dues letter (NDC) or No Objection letter (NOC) within 21 to 30 days of payment. Check after 45 days that CIBIL. Experian. CRIF High Mark reflect an unpaid balance of ₹0 with the status updated from ". Default/Overdue". to ". Settled".
6. Formal Legal Notice Defense & Statutory Legal Framework
When a ₹2 Lakh own loan enters default. Lenders often dispatch alarming legal notices to create panic. grasp the exact legal frameworks governing these notices ensures you respond with composure and legal precision:
1. SECTION 25 PSSA 2007 (NACH / ECS DISHONOUR):
Quasi-penal notice issued when automated EMI auto-debit bounces due to insufficient funds.
Defensive Remedy: Reply within 15 days documenting money distress. Lack of mens rea (fraudulent intention). formal offer of deal OTS.
2. SECTION 138 NEGOTIABLE INSTRUMENTS ACT (CHEQUE BOUNCE):
Applicable only if a real security cheque was presented and returned dishonoured.
Defensive Remedy: Compoundable legal offense. Executing an OTS automatically quashes Section 138 complaints under Section 147 NI Act.
3. SECTION 21 ARBITRATION &. CONCILIATION ACT 1996:
Notice invoking arbitration clause.
Defensive Remedy: Supreme Court precedents in Perkins Eastman (2020) and TRF Ltd. (2017) prohibit unilateral arbitrator appointments by banks. Challenge arbitrator under Section 12(5).
4. SECTION 73/74 INDIAN CONTRACT ACT 1872:
Standard civil notice demanding main sum + rates.
Defensive Remedy: Pure civil dispute with zero arrest powers. grounds for direct bilateral closure talks.
legal Rights under RBI Fair Practices Code
Under the Reserve Bank of India Master Directions. Trade banks and NBFCs are strictly held accountable for the conduct of their agents. claims staff are by law prohibited from:
- Calling before 8:00 AM or after 7:00 PM in the evening.
- Accessing your phone contacts or calling family. Employers. friends.
- Using threaten, abusive. false language over phone or WhatsApp.
- Visiting your workplace or residence without prior written notice and valid bank ID.
- Misrepresenting themselves as police heads. Court bailiffs. penal investigators.
7. 3-Tier Escalation Matrix for Unfair Recovery Tactics
If the lending bank or its calls agents ignore your hardship notices or engage in coercive claims tactics for a ₹2 Lakh loan. Escalate through this structured 3-tier hierarchy:
Formal Written Grievance &. OTS Submission
Submit a formal email and speed post letter to the Branch Manager and the internal Grievance Redressal head (GRO) citing your loan account number. Documented hardship. formal deals.
Escalation for claims threats &. Excessive fines
If Level 1 fails to respond within 30 days or rejects reasonable closure terms while agents continue threats. File a formal complaint before the bank&apos. s main sum Nodal head (PNO).
legal RBI Complaint on cms.rbi.org.in
If the bank fails to resolve your grievance within 30 days or violates the RBI Fair Practices Code. Lodge a formal RBI complaint on the RBI Integrated RBI officer Portal (cms.rbi.org.in). The RBI officer has legal authority to award compensation up to ₹20 Lakhs for mental threats and direct fair closure terms.
8. Resolution Timelines & Milestone Table (Day 0 to Month 6)
grasp the chronological phases of a ₹2 Lakh loan default allows you to plan your defense. Manage cash reserves. time your closure talks for maximum discount:
| Timeline Phase | Institutional Status | Bank Recovery Action | Borrower Strategic Action |
|---|---|---|---|
| Day 1 to 30 | SMA-0 / Overdue | Automated SMS. Emails. Tele-calling reminders | Audit loan SOA and assess true money liquidity |
| Day 31 to 90 | SMA-1 &. SMA-2 | Intensified calls calls. Field agent visit notices | Compile hardship dossier. issue anti-threats notice if needed |
| Day 91 to 120 | NPA (Sub-Standard) | Loan recall notice / Section 25 NACH bounce notice | Submit formal OTS Hardship Proposal for 30%. 45% main sum |
| Months 4 to 5 | deal OTS Window | Bank closure board reviews deal proposal | Execute bilateral talks. secure written OTS Sanction Letter |
| Month 6 | Account Closed / Settled | Issuance of valid No Dues letter (NDC) | Remit agreed OTS sum straight. obtain NDC. initiate CIBIL rebuild |
9. Scenarios: Digital Fintech Apps, Credit Cards and ARCs
Small-ticket loan defaults manifest across various money structures with exact nuances:
Fintech NBFC Digital Instant Loan Apps (KreditBee. Navi. MoneyTap. PaySense)
Digital loan apps disburse smaller loans instantly but often deploy harsh automated calls bots. WhatsApp reminders. Online Dispute relief (ODR) notices. Because fintech NBFCs maintain high volume and rapid balance-sheet turnover. Their algorithms often generate automatic 40% to 60% closure discounts at the end of money quarters (March. September).
Multiple Small Micro-Loans Totaling ₹2 Lakh
clients often end up with 3 to 5 smaller loans (e.g. ₹30,000 + ₹50,000 + ₹60,000 + ₹60,000 across different apps). Attempting to juggle fragmented payments wastes scarce capital. A coordinated multi-loan debt closure strategy pools your funds. Prioritizes the most harsh lenders first. executes structured closures across all accounts simultaneously.
Credit Card own Loans vs. Standalone own Loans
If your ₹2 Lakh debt is a pre-approved ". Jumbo Loan". or ". Loan on Credit Card". The bank may block your underlying credit card and demand the full card limit plus the loan balance. During closure talks. The closure pacts must explicitly cover both the card and the loan to ensure total closure and issuance of an all-encompassing No Dues letter.
Loans Sold to Asset Reconstruction Companies (ARCs)
When traditional banks write off ₹2 Lakh own loans. They bundle them into portfolios and sell them to ARCs (such as CFM ARC. Phoenix ARC. ARCIL) at 20% to 30% of face value under Section 5 of the SARFAESI Act. ARCs possess enormous margin flexibility. Making them open to deep 60% to 75% deal closures.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions on Settling a ₹2 Lakh Personal Loan
Click on any question below to view detailed legal and money answers checked by our debt relief experts:
Official Regulatory Citations & Legal References
The legal frameworks. Dispute procedures. debt relief mechanisms referenced in this guide are straight anchored in valid Indian banking enactments and Reserve Bank of India Master Directions:
- Reserve Bank of India (RBI): Master Direction on Fair Practices Code for Lenders (Guidelines on agents and Grievance Redressal. Updated 2026).
- Reserve Bank - Integrated RBI officer Scheme. 2021: legal Grievance Redressal Mechanism for trade Banks and NBFCs (cms.rbi.org.in).
- Credit Information Companies (rule) Act. 2005 (CICRA): Section 21 regarding clients Rights. Credit Dispute relief. desk Reporting.
- Payments and closure Systems Act. 2007 (PSSA): Section 25 regarding Dishonour of online Funds Transfer and NACH Mandates.
- Indian Contract Act. 1872: Sections 73 and 74 regarding Breach of Contract and Civil Monetary Compensation.