High-Value Default: Settle a ₹25 Lakh Personal Loan
Defaulting on a ₹25 Lakh own loan requires strategic legal defense. Discover how to neutralize bank litigation. Handle DRT and Section 25 notices. Shield own assets. settle a formal One-Time closure (OTS) with substantial main sum waiver.
- closure Target: Settle ₹25 Lakh clean debt for 40% to 55% of true main sum balance (₹10,00,000 - ₹13,75,000 in full discharge).
- 100% Penal Waiver: fully eradicate ₹8 Lakh to ₹12 Lakh in growing penal rates and bounce charges.
- Strictly Civil Dispute: Loan default is a contractual dispute under Indian Contract Act with zero risk of police arrest.
- Notice Defense: Formally reply to and quash Section 25 PSSA and Section 138 NI Act notices within the 15-day legal window.
- DRT Strategy: Avoid 3 to 5 years of costly court litigation via fast out-of-court bilateral deal.
- Arbitration Shield: Quash unilateral sole arbitrator appointments under Supreme Court Perkins Eastman precedent.
- Asset safety: Lenders cannot attach home homes or freeze salaries without a conclusive judicial decree.
- Anti-threats: Enforce RBI Fair Practices Code to stop calls after 7 PM. Unannounced visits. workplace contacts.
- Direct Account wire transfer: Disburse funds straight into your loan account under bank sanction letter to secure an authentic NDC.
1. High-Value Debt Economics: Can You Settle a ₹25 Lakh Personal Loan?
Defaulting on an clean ₹25 Lakh own loan represents a major inflection point in retail banking. Unlike smaller micro-loans. High-value debt exposures of ₹25 Lakhs carry heavy monthly EMIs of ₹60,000 to ₹80,000. When severe life shocks occur. Such as firm layoffs. Enterprise cash-flow disruption. Medical emergencies. Continuing full debt servicing becomes mathematically impossible.
After 90 running days of missed installments. The loan transitions into a Non-Performing Asset (NPA). Under Reserve Bank of India prudential guidelines. Lenders must set aside mandatory Tier-1 capital provisioning. Scaling from 15% up to 100% of the loan value. Because clean own loans carry no attached mortgage pledge under the SARFAESI Act. Banks face prolonged claims timelines. While claims exceeding ₹20 Lakhs can be filed before the Debt claims court (DRT) under Section 19 of the RDB Act. Court trials often take 3 to 5 years. Consequently. Bank credit boards routinely prioritize an out-of-court One-Time closure (OTS) accepting 40% to 55% of main sum to fast release provisioning reserves and clear bad debt.
2. How Much to Pay to Settle a ₹25 Lakh Personal Loan?
Following default. Lenders rapidly inflate the claimed balance with compounded penal rates rates (24% to 36% per annum). Overdue late charges. mandate bounce fees. Within 12 months. An original main sum balance of ₹20.5 Lakhs escalates into an inflated claims demand claiming ₹33 Lakhs to ₹38 Lakhs. Strategic debt closure isolates the true net main sum and eliminates all non-contractual penal levies:
Anatomy of a Defaulted ₹25 Lakh own Loan Claim
180-Day NPA Case3. Resolution Matrix: Settlement vs DRT vs Default
clients confronting a defaulted ₹25 Lakh own loan have five primary relief pathways available under Indian law:
| Option | Outflow | CIBIL Impact | Litigation Risk | Timeline | Strategic Assessment |
|---|---|---|---|---|---|
| One-Time closure (OTS) | ₹10.0L. ₹13.75L | ". Settled". (-75 to -130 pts) | Eliminated (Withdrawn) | 45. 90 Days | Optimal path for debt relief and permanent legal release |
| Restructuring | ₹25L + Full rates | ". Restructured". | Paused during EMIs | 48. 84 Months | Viable only if substantial ongoing cash flow is certain |
| DRT Contest | ₹1.5L+ Legal Fees | ". Suit Filed / DRT". | High (court trials) | 3. 5 Years | Effective defensive defense to compel an out-of-court OTS |
| Lok Adalat OTS | ₹11.0L. ₹14.5L | ". Settled via Adalat". | Decree passed (Final) | 1 Day sitting | Binding judicial closure if pre-settle by counsel |
| Inaction / Default | Claims balloon | ". Written Off". | Severe (Notices, visits) | Indefinite | Severe risk of credit paralysis and persistent disputes |
4. CIBIL Score Impact of a ₹25 Lakh Loan Settlement
Credit bureaus calculate CIBIL scores across five weighted parameters: Payment History (35%). Credit Exposure (30%). Credit Longevity (15%). Credit Mix (10%). Recent Inquiries (10%).
Weight Distribution &. Default Impact
Credit Score Rehabilitation Path
Visual Defense Blueprint: ₹25 Lakh Personal Loan Settlement Roadmap
Study this 6-stage roadmap detailing the entire trajectory from first loan default to forensic audit. Legal notice defense. Credit board talks. Direct wire transfer. credit rehabilitation:
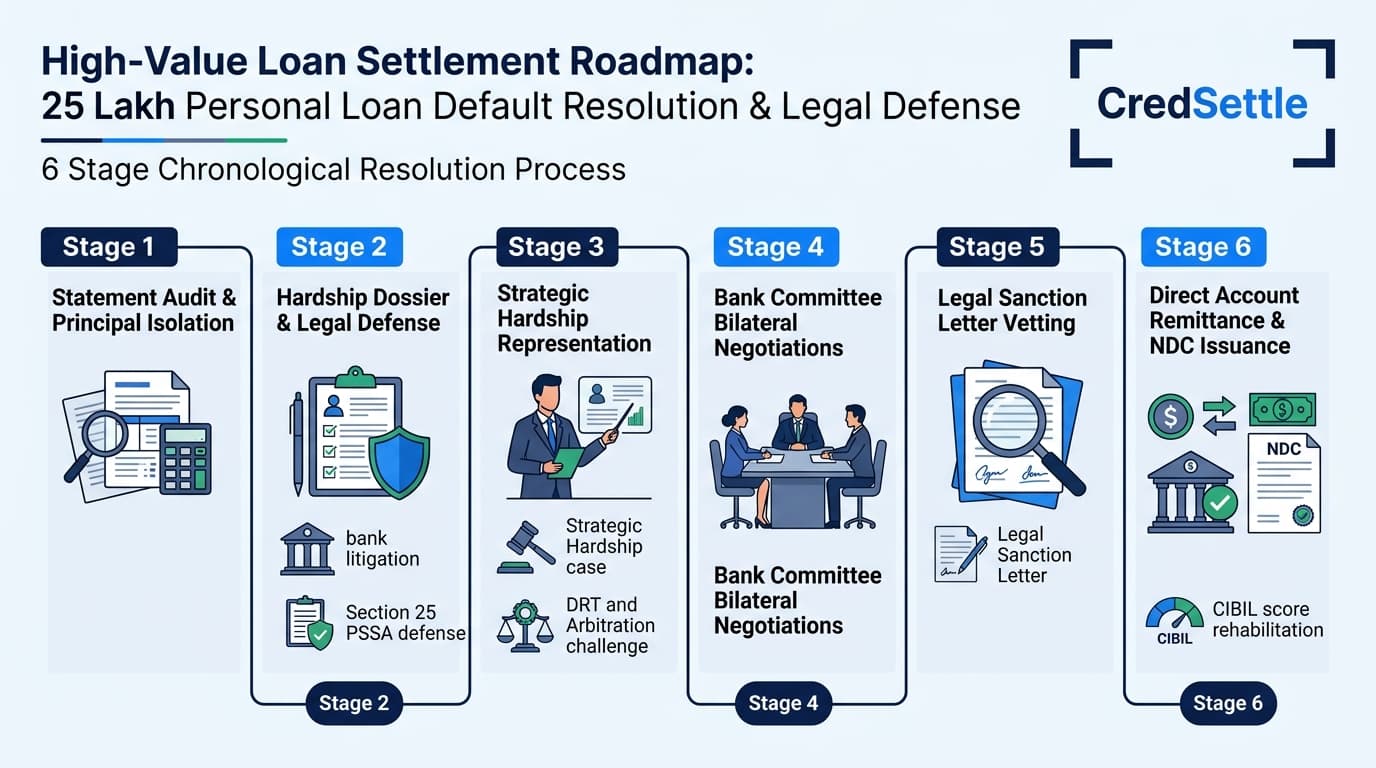
5. 6-Stage SOP to Settle a ₹25 Lakh Personal Loan
Settling a high-stakes ₹25 Lakh loan requires adhering to a structured 6-stage standard operating procedure to counter litigation. Eliminate threats. maximize main sum waiver:
Forensic Statement Audit &. Net main sum Isolation
Obtain a signed Statement of Account (SOA) from the lender. Audit all historical EMI payments. Deduct regular rates. Excise non-contractual 36% compound penal fees and mandate return charges. establish the true net main sum balance as the baseline for a 40% to 55% deals.
Hardship Dossier Compilation &. Legal Shielding
Assemble verifiable hardship records. Including firm layoff letters. Audited firm revenue declines. medical summaries. Concurrently. Serve a formal Cease-and-Desist notice under the RBI Fair Practices Code to halt illegal agents visits.
Formal Representation to Credit Risk board
Submit a thorough legal deal representation straight to the bank&apos. s Zonal Head of NPA claims and Credit board. Cite RBI deal closure directives. Demonstrate bona fide illiquidity. open talks with a structured 30% to 35% offer.
Bilateral talks &. Provisioning Leverage
Counter the bank&apos. S first demands by demonstrating the high cost of DRT court litigation. Highlighting the clients&apos. s lack of attachable assets. utilizing quarter-end provisioning write-down pressures to finalize the deal at 40%. 55% of main sum.
Legal Vetting of closure Sanction Letter
Conduct thorough legal due care on the formal closure Sanction Letter issued on valid bank letterhead signed by an authorized manager. Confirm exact closure figures. Complete waiver clauses. Payment installments. binding NDC commitments.
Direct wire transfer. Case Withdrawal &. NDC Issuance
Remit the agreed closure funds straight into your loan account via RTGS or NEFT. Secure the valid No Dues letter within 30 days. Ensure the bank withdraws all legal notices. check that credit bureaus report the account balance as zero.
6. Formal Legal Notice Defense & Statutory Legal Framework
When managing a ₹25 Lakh own loan default. Grasp legal defense frameworks is crucial to protecting your rights against bank bank notices:
1. SECTION 25 PSSA 2007 (NACH BOUNCE): Issued for online clearing bounce. Serve a formal 15-day legal reply proving lack of mens rea and submitting an OTS deal. steps are quashed upon closure.
2. SECTION 138 NI ACT 1881 (CHEQUE BOUNCE): Issued for dishonoured security cheques. Compoundable under Section 147. dismissed fast upon closure payment.
3. ARBITRATION &. CONCILIATION ACT (SECTION 21): Supreme Court rulings in TRF Ltd. and Perkins Eastman prohibit unilateral arbitrator appointments. Ineligibility is absolute under Section 12(5).
4. SECTION 19 RDB ACT (DRT claims): Applies to claims over ₹20L. File written statement contesting penal rates and petition for Lok Adalat referral to execute an out-of-court OTS.
clients Rights Under RBI Fair Practices Code
- No calls calls or home visits before 8:00 AM or after 7:00 PM.
- Strict prohibition against contacting employers. Workplace colleagues. relatives.
- Zero tolerance for threaten. Abusive. false language.
7. The 3-Tier Escalation Matrix for High-Value Loan Disputes
Submit a formal written OTS deal representation to the Branch Manager and GRO (7. 10 days turnaround).
Escalate to Bank PNO if unresolved within 30 days or for threats violations (14. 21 days turnaround).
Lodge RBI complaint at cms.rbi.org.in for legal action and binding closure direction.
8. Settlement Timelines & Milestone Table (Day 0 to Month 6)
| Phase | Status | Bank Action | Borrower Defense Action |
|---|---|---|---|
| Days 1. 30 | SMA-0 | SMS &. call reminders | Audit statement. Calculate net main sum. Preserve liquidity |
| Days 31. 90 | SMA-1 / SMA-2 | Demand notices | Compile hardship dossier. issue Cease-and-Desist notice |
| Days 91. 120 | NPA | Section 25 / DRT notice | Submit formal OTS proposal to Zonal Credit board |
| Months 4. 5 | deal Window | Credit board review | settle 40%. 55% waiver. secure written Sanction Letter |
| Month 6 | Settled &. Closed | Issue valid NDC | Remit funds straight. secure NDC. begin CIBIL rebuilding |
9. Special Scenarios: Multi-Lender Portfolios & ARCs
Multi-Lender Portfolios (₹10L + ₹8L + ₹7L)
Prioritize harsh lenders first and execute structured. Phased closures across each bank without depleting reserves on partial EMIs.
firm Executives Facing Layoffs
Present authenticated end letters and liquid asset exhaustion to secure maximum main sum haircuts from credit boards.
Proprietorship firm Working Capital
Submit audited balance sheets. GST revenue drops. creditor lists to check firm insolvency and obtain deep closure discounts.
Debts Sold to ARCs (CFM. Phoenix. ARCIL)
ARCs purchase bad loan portfolios at 70%. 80% discounts. Allowing substantial closure headroom of 60% to 75% total waivers.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions on Settling a ₹25 Lakh Personal Loan
Official Regulatory Citations & Legal References
- Reserve Bank of India (RBI): Master Direction on Fair Practices Code for Lenders (agents Conduct &. Grievance Redressal).
- RBI Integrated RBI officer Scheme. 2021: legal dispute mechanism on cms.rbi.org.in.
- CICRA 2005 (Section 21): Credit dispute relief and desk remark rectification.
- PSSA 2007 (Section 25): Dishonour of online funds transfer / NACH mandates.
- RDB Act 1993 (Section 19): Original Applications before Debt claims Tribunals (DRT).
- Indian Contract Act 1872: Sections 73 &. 74 regarding civil contractual damages.
- NI Act 1881 (Section 138 &. 147): Cheque dishonour defense and growing of offenses.