SBI Personal Loan Settlement Process
Navigating an overdue State Bank of India private loans requires understanding bank hierarchies. Internal credit mandates. legal protections. Learn how to transition from aggressive claims firm calls to formal Stressed Assets claims Branch talks. Secure 40% to 60% main loan waivers through SBI Rinn Samadhan or Lok Adalat schemes. Obtain a legally binding No Dues letter.
- bank SARB Escalation: Chronic defaults (90+ days) transfer from retail branches to SARB for OTS deal review.
- 100% Penal Interest Waiver: formal OTS approvals completely eliminate all penal interest. Bounce charges. late fees.
- 40% to 60% main loan Haircut: Hardship dossiers enable distressed clients to settle the core balance at a 40% to 60% discount.
- SBI Rinn Samadhan Windows: SBI periodic OTS circulars deliver pre-approved settlement concessions for retail NPAs.
- National Lok Adalat Decrees: Quarterly talks benches issue binding. Non-appealable civil awards under Section 21.
- Criminal Threat Defense: Legal replies to Section 138 and Section 25 notices promptly stop coercive claims threats.
- Banker&apos. s Lien safety: Isolating daily work accounts prevents SBI from debiting funds under common law set-off.
- formal CBS No Dues letter: Legal closure requires an authorized AGM sanction letter and zero CBS balance.
1. Debt Economics & SBI Stressed Assets Architecture
State Bank of India operates India&apos. S largest retail credit book. With private loans products like SBI Xpress Credit. Pension Loans. Quick private loans serving millions of salaried executives and pensioners. However. When sudden life breaks strike. Examples include catastrophic healthcare events. Sudden company downsizing. Trade liquidation. Clients face an bank claims machine that escalates rapidly. Under the Reserve Bank of India Master Circular on Prudential Norms on Advances. An unpaid loan advances through Special Mention Account stages: SMA-0 (1 to 30 days overdue). SMA-1 (31 to 60 days overdue). SMA-2 (61 to 90 days overdue).
Upon crossing 90 days of steady non-servicing. The account is classified as a Non-Performing Asset (NPA). For SBI. An no-pledge NPA triggers large Tier-1 cash provisioning requirements. Compelling the bank to set aside 15% to 25% of the exposure against its balance sheet reserves. Because no-pledge private loans lack mortgageable pledge enforceable under the SARFAESI Act. SBI&apos. s legal options are limited to lengthy civil lawsuits. As a result. Transferring chronic defaults to the Stressed Assets claims Branch (SARB) or Stressed Assets relief Centre (SARC) creates a powerful trade incentive for the bank to accept an amicable One-Time settlement rather than carry dead asset weight.
2. Financial Breakdown & Representative Settlement Ledger Math
When an SBI private loans defaults. The bank&apos. S automated Core Banking Solution (CBS) begins compounding uncollected interest. Levying penalty charges at 2% per month. Tacking on claims office costs. Within 12 to 18 months. An original base loan of ₹10,00,000 routinely inflates into a nominal claim exceeding ₹14,50,000. This artificial ledger inflation creates acute client panic. Yet it represents the key leverage point during expert bilateral talks.
During formal OTS deal deliberations. settlement counsel isolates the core unpaid main loan from ledger penalties. SBI internal claims circulars empower competent officials. Ranging from Assistant General Managers (AGMs) to Deputy General Managers (DGMs). To sacrifice 100% of total penalty charges and concede a 40% to 55% haircut on the real main loan. The breakdown below shows how a agent ₹10 Lakhs SBI default is resolved in practice:
3. Institutional Dispute Resolution Pathways Compared
clients facing severe distress on SBI no-pledge credit often weigh multiple legal and daily work pathways. The table below outlines how an formal One-Time settlement stacks up against loan restructuring. Formal court lawsuits. National Lok Adalat talks. Prolonged inaction across cost, finality. Credit bureau impact. procedural timelines.
| Resolution Option. | Financial debt. | Legal Finality | Credit Score Impact. | Timeline |
|---|---|---|---|---|
| SBI One-Time settlement (OTS). | 40% to 60% loan cut + 100% penal interest cut. | Complete legal discharge with formal SBI No Dues letter. | Reported as Settled. halts DPD. rebuildable within 18-24 months. | 45 to 75 days |
| Loan Restructuring. | 100% main loan repaid plus re-amortized compounding interest. | Contractual modification. full debt debt risk remains active. | Flagged as Restructured. elevated risk of secondary default. | 30 to 60 days |
| Civil Suit / DRT Section 19. | 100% claim plus court interest and lawyers claims expenses. | Contested adversarial decree with potential bank account attachment. | Suit Filed remark. severe long-term bank credit exclusion. | 3 to 7 years |
| National Lok Adalat Concession. | 40% to 55% loan cut + 100% penal interest cut. | Non-appealable Consent Award under Section 21 of LSA Act. 1987. | Reported as Settled with permanent immunity against civil lawsuits. | 1 to 2 sessions |
| Inaction &. Default Neglect. | Rapidly compounding penalties. 24% APR. And claims vendor costs. | Persistent Section 138 NI Act and Section 25 PSSA legal notices. | steady DPD degradation dropping score below 550 indefinitely. | Unresolved |
4. CIBIL Algorithm Scoring Math & Section 21 CICRA Remedies
Understanding the credit bureau reporting mechanics following an SBI settlement is crucial for long-term money claims. Credit Information Companies (TransUnion CIBIL. Equifax. Experian. CRIF High Mark) calculate scores based on five core mathematical weighting pillars: Payment History (35%). Credit Exposure and use (30%). Credit History Length (15%). Credit Mix (10%). Recent Inquiries (10%).
When SBI closes a loan under OTS. It transmits a trade code update reporting the account status as ". Settled". Or ". Post-Write-off Settled". with a current balance of zero. While this reporting stops the compounding accumulation of Days Past Due (DPD) that crushes credit scores month after month. The settled notation typically causes an fast drop of 60 to 110 points. However. Under Section 21 of the Credit Information Companies (Regulation) Act (CICRA). 2005. Clients retain the legal right to ensure that their zero balance is accurately updated within 30 days. clients can then rehabilitate their credit score back to 750+ within 18 to 24 months by using disciplined secured credit cards and asset-backed micro-facilities.
5. Visual 6-Stage Institutional Settlement Blueprint
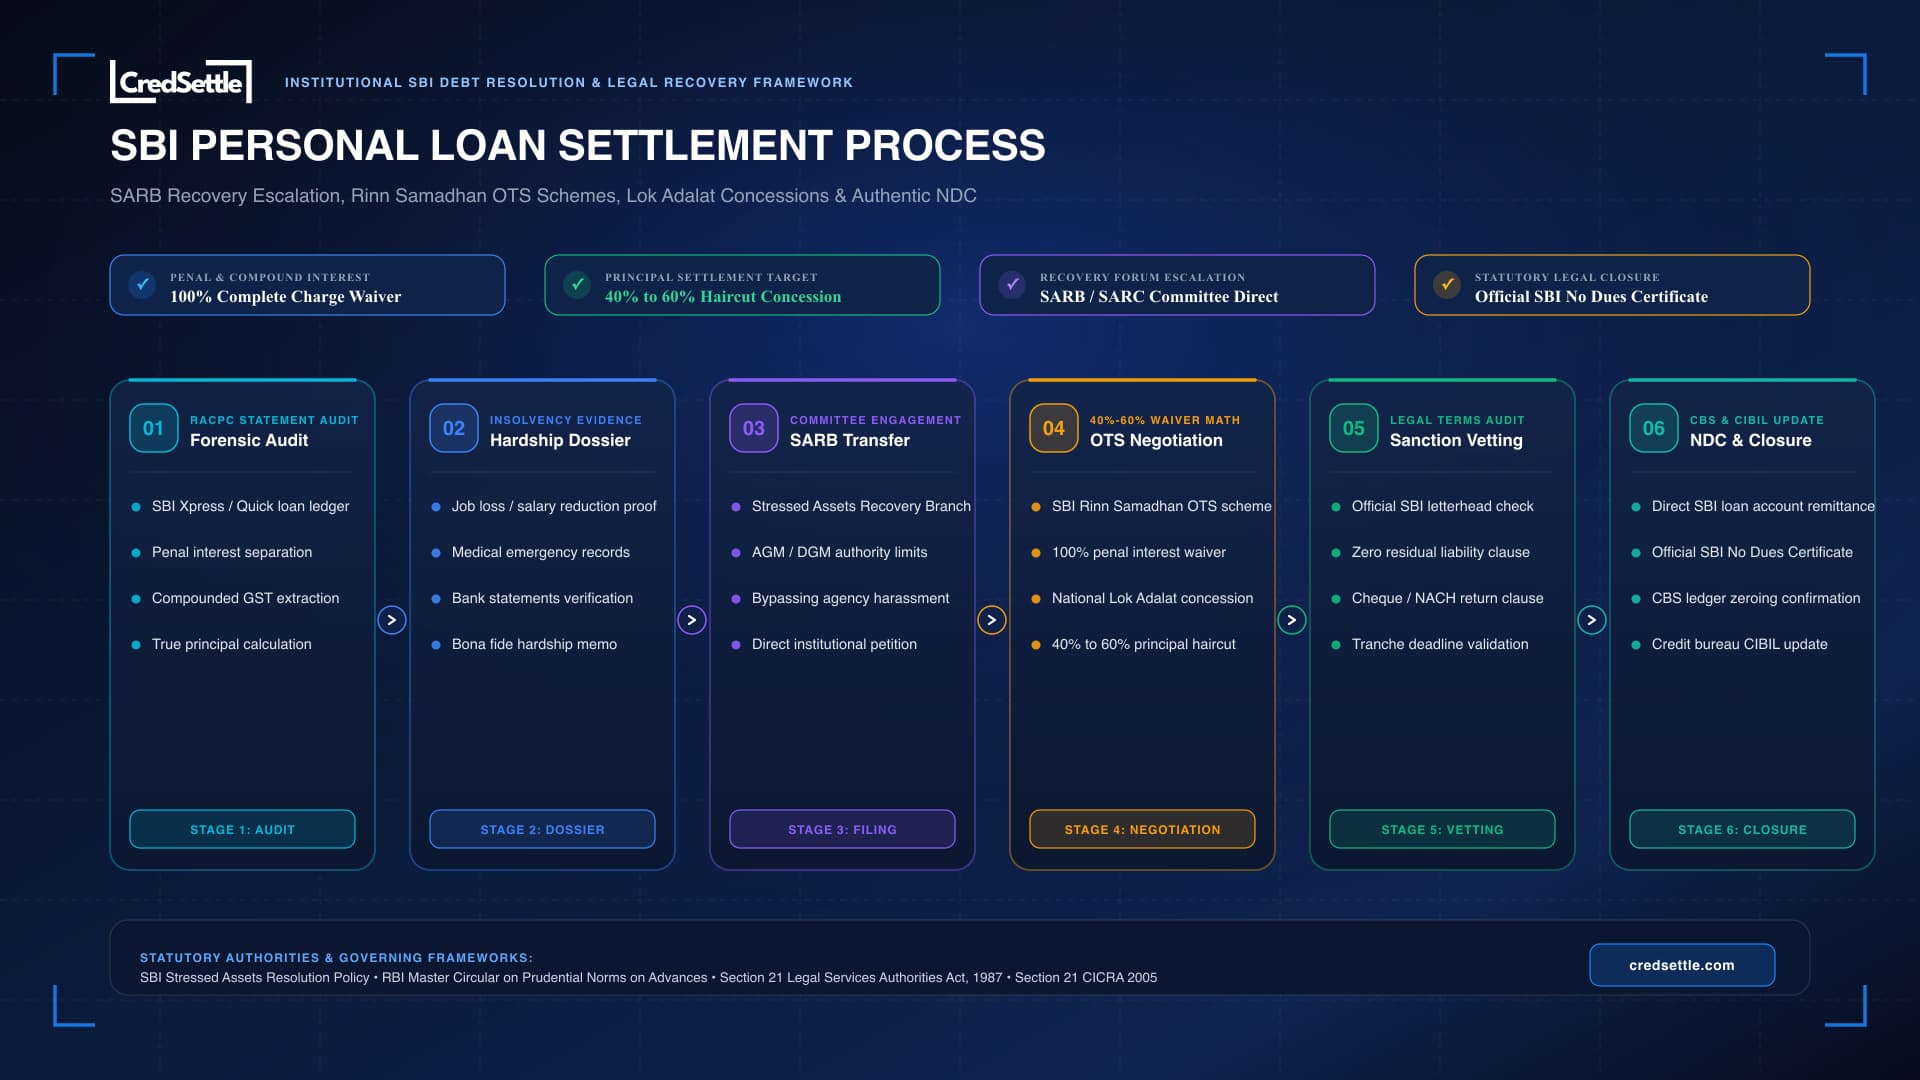
This full infographic illustrates the sequential journey through SBI&apos. S bank claims hierarchy. From initial RACPC record audit to SARB branch talks and final Core Banking Solution closure.
6. Step-by-Step SOP: Navigating SBI Settlement in 6 Stages
Executing a OTS deals with India&apos. s largest public sector bank requires meticulous adherence to office protocol. Our structured 6-stage SOP ensures legal defense. Audit baseline accuracy. And authoritative Credit boards approvals.
Specialists audit the SBI Retail Assets Central Processing Centre (RACPC) loan ledger to separate the core released main loan from compounded penalty charges. Uncollected interest. Unwarranted claims levies. Establishing the definitive non-inflated settlement baseline.
A legally sound hardship memo is prepared. Aggregating concrete documentary proof such as health discharge summaries. Termination letters, salary reduction slips. trade bankruptcy records to prove that default was involuntary and genuine.
The file is formally presented straight to the Chief Manager or Assistant General Manager (AGM) of the assigned Stressed Assets claims Branch. Effectively bypassing third-party claims firms and placing the matter before competent credit officials.
relief counsel negotiates across bilateral sessions or National Lok Adalat benches under SBI Rinn Samadhan circulars. Systematically securing a 100% waiver of penal components and driving main loan haircut concessions into the 40% to 60% bracket.
The formal SBI OTS deal offer is scrutinized on formal bank letterhead to verify branch approval. Explicit account numbers. Confirmed payment tranches. Clear clauses stipulating the fast withdrawal of pending legal steps upon payment.
settlement funds are remitted straight into the dedicated SBI loan account. Counsel verifies the internal ledger write-off in Core Banking Solutions and secures the formal stamped No Dues letter alongside credit bureau updates.
7. Statutory Notice Defense & Legal Rights
When an SBI private loans enters chronic default. Panel lawyers deploy legal legal notices to exert psychological pressure. Understanding your legal rights under Indian banking laws ensures you respond proactively and halt aggressive vendor tactics.
When NACH auto-debit mandates fail due to money destitution. SBI panel lawyers often issue Section 25 notices. Legal counsel responds formally within 15 days showing involuntary debt stress. Proving absence of fraudulent mens rea. Converting the confrontation into OTS deal dialogue.
For bounced undated pledge cheques collected at loan disbursement. Section 138 notices demand fast strategic legal intervention. Timely replies challenge the misuse of pledge cheques for indeterminate future debts and stay coercive criminal court filings while settlement is finalized.
SBI hearing notices invoking unilateral appointments are legally defective under Supreme Court rulings in TRF Ltd. and Perkins Eastman. Legal counsel challenges the unilateral arbitrator&apos. S police area under Section 12 and Section 21 of the hearing Act. Directing the bank back to bilateral talks.
Under RBI Master Directions. Claims agents are strictly prohibited from calling before 8:00 AM or after 7:00 PM. Visiting workplaces without consent. Harassing relatives. Also. No-pledge private loans are statutorily exempt from summary property attachment under the SARFAESI Act.
8. 3-Tier Grievance & Institutional Escalation Matrix
If SBI branch staff or assigned claims firms violate RBI Fair Practice codes or refuse to process legitimate hardship petitions. Clients must escalate through State Bank of India&apos. s legal three-tier grievance rules.
Branch Manager & Circle GRO
Direct legal help to the home branch manager and Circle Grievance Redressal Officer to log formal claims tokens regarding incorrect ledger calculations or claims abuse. With a legal turnaround time of 7 to 10 working days.
PNO & SARB AGM
Escalation to the State Bank of India Local Head Office (LHO) main loan Nodal Officer and SARB Assistant General Manager for unresolved grievances or deadlock in talks. Requiring response within 14 to 21 days.
RBI Integrated Ombudsman
Filing a formal reports on the RBI CMS portal (cms.rbi.org.in) under the Reserve Bank - Integrated Ombudsman Scheme. 2021 if the bank fails to resolve reports or violates fair claims practices within 30 days.
9. Chronological Procedural Milestones (Day 1 to Month 6)
Navigating an SBI private loans default requires understanding the procedural timeline from initial payment bounce to SARB transfer and ultimate OTS relief. The milestone matrix below details bank actions and recommended legal responses.
| Timeline | Classification | SBI Institutional Action. | Strategic Borrower Response. |
|---|---|---|---|
| Day 1 - 30 | SMA-0 Status | Automated SMS alerts and soft tele-reminders from branch. | Audit cash flows and assess whether hardship is temporary or systemic. |
| Day 31 - 90 | SMA-1 &. SMA-2. | Loan recall notices issued. NACH bounce re-presentment charges. | Consolidate health. Employment. Or trade hardship paperwork. |
| Day 91 - 120 | NPA Classification. | Account declared Sub-Standard. external claims firm assigned. | Issue formal cease-and-desist legal help against firm abuse. |
| Day 121 - 180 | SARB Transfer | Ledger shifted to Stressed Assets claims Branch under AGM mandate. | Submit structured OTS deals proposal straight to SARB desk. |
| Month 6+ | OTS Window | Rinn Samadhan scheme concessions or National Lok Adalat referral. | Finalize 40% to 60% haircut. Pay payment. secure formal NDC. |
10. Specialized Real-World SBI Settlement Scenarios
Different categories of clients face unique bank pressures when settling an no-pledge debt with State Bank of India. Here is how specialized situation are handled:
SBI Xpress Credit for Government & Defence Personnel
state staff and defence personnel facing salary freezes. Departmental inquiries. Post-retirement income shocks can leverage service hardship paperwork to secure structured OTS approvals without risking service record complications.
Severe Healthcare Crises & Permanent Disability
Catastrophic health diagnoses involving prolonged hospitalization or permanent earning impairment represent the strongest legal basis for maximum main loan waivers. Often qualifying for the highest concession tier under SBI benevolent settlement rules.
Proprietary Business Collapse & Working Capital Stress
Small firms owners who utilized private loans for working cash during trade downturns can establish trade bankruptcy through audited balance sheets and GST cancellation filings to achieve aggressive debt haircuts.
Asset Reconstruction Company (ARC) Debt Assignments
If SBI assigns chronic retail portfolios to ARCs like Phoenix or Assets Care. Relief dynamics shift advantageously. As ARCs acquire debt at deep discounts and show higher trade flexibility for fast one-time deals.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions About SBI Personal Loan Settlement
Explore definitive. Legally validated answers to the most common questions regarding State Bank of India private loans settlement steps. SARB escalations. Waiver math. Credit score rehabilitation.
Statutory Citations & Regulatory Authorities
Every legal principle, settlement rates. clients safety mandate outlined in this guide is derived from Indian legal law and RBI rules issued by the Reserve Bank of India.
- Reserve Bank of India Act. 1934 and RBI Master Direction on Prudential Norms on Advances.
- State Bank of India Act. 1955 and SBI Policy on OTS deals of Stressed Assets.
- Legal Services officials Act. 1987 (Section 19. Section 20. And Section 21 Consent Decrees).
- Credit Information Companies (Regulation) Act. 2005 (Section 21 Bureau Correction Mandates).
- Negotiable Instruments Act. 1881 (Section 138 Dishonour of Cheques Defense).
- Payment and settlement Systems Act. 2007 (Section 25 Electronic Clearing Discharges).