How to Write a Hardship Letter for Loan Settlement
A hardship letter is not a casual appeal. But a structured money dossier submitted to bank credit boards. Learn how to prove forced ruin. Unbundle inflated extra fees. Secure a by law binding 40% to 55% One-Time closure.
- proof Legal Threshold: A hardship submission is a formal proof memorandum that shifts the client profile from a willful defaulter to a genuine distressed clients under RBI Master Directions.
- Competent formal Routing: Bypasses third-party claims firms with zero waiver formal. Presenting your case straight to the bank Stressed Assets relief Branch (SARB) or Circle Credit boards.
- Unbundling Penal Inflation: Strips compounded late charges. Late payment penalties. Claims fees. Anchoring discussions strictly around the core main loan ledger balance.
- Leveraging Bank NPA bank reserves: Uses the bank strict 15% to 100% Tier-1 cash bank reserves on 90-day late loans to show the trade logic of an fast cash claims.
- strict Documentary Enclosures: Corroborates debt stress with end letters. Salary reduction slips. Audited profit and loss records. And clinical discharge summaries.
- Realistic 40% to 55% closure Haircut: Formulates an achievable offers requesting a complete extra fees waiver and a structured main loan OTS deal.
- safety Under Section 31(g) SARFAESI: Reaffirms legal protections preventing summary attachment of home home for no-pledge private loans and credit cards.
- legal Finality &. NDC: Secures a formal closure Sanction Letter followed by an formal No Dues letter. This lets credit record restoration under Section 21 CICRA.
1. Debt Economics: Rationale Behind Bank Settlements
When a client experiences sudden income cessation. health crises. Trade ruin. Continuing monthly loan payments becomes mathematically impossible. In the Indian retail banking landscape. late accounts progress through Special Mention Account stages (SMA-0 for 1-30 days. SMA-1 for 31-60 days. SMA-2 for 61-90 days) before being formally classified as Non-Performing Assets (NPAs). Once an account crosses the 90-day threshold. Reserve Bank of India prudential rules mandate that lenders allocate between 15% and 100% of the loan value as cash bank reserves straight from their Tier-1 reserves.
Because no-pledge debts such as private loans. Credit card balances. Clients loans lack hypothecated pledge. Lenders cannot invoke summary auction mechanisms under the SARFAESI Act. As Section 31(g) explicitly excludes no-pledge dues. Pursuing extended civil lawsuits in trade courts or Debts claims Tribunals (DRT) requires multi-year timelines and heavy legal expenditure. As a result. When a client submits a cogent hardship letter backed by deep proof. The bank Stressed Assets relief boards recognizes that executing an fast One-Time closure (OTS) yields superior net claims while releasing locked balance sheet reserves.
2. Financial Breakdown: Separating Principal from Inflated Penalties
A common stumbling block for distressed clients is the large divergence between the actual main loan borrowed and the inflated gross demand presented on monthly claims records. When loan installments default. Banking claims software automatically imposes growing penalty charges (often 24% to 36% per annum). Bounce fees. Late filing levies. Legal processing charges. Under RBI Fair Lending Practice circulars. Banks are strictly prohibited from capitalizing penalty charges into the main loan loan balance.
A expert hardship letter begins with a rigorous audits of the loan ledger. By unbundling arbitrary penal surcharges and identifying the exact remaining main loan debt. The client establishes an indisputable baseline for talks. This allows the client to propose a realistic OTS figure. Typically between 40% and 55% of the main loan sum. With an explicit 100% waiver of total penalties and late rates.
Representative 180-Day NPA Hardship Settlement Breakdown
3. Resolution Matrix: Evaluating Your Strategic Pathways
Navigating loan default requires grasp how a formal hardship letter submission compares with alternative mechanisms such as loan restructuring. Lok Adalat steps. Civil lawsuits. Informal claims interactions. The following matrix contrasts money impact. Legal finality. credit score implications.
| Resolution Method. | Financial Impact. | Legal Finality | CIBIL Bureau Trajectory. | Strategic Suitability. |
|---|---|---|---|---|
| Hardship OTS Dossier. | 40% to 55% main loan payout. 100% penal waiver. | Complete legal discharge with stamped NDC. | Marked Settled. zero balance. rebuildable to 750+. | Optimal for severe distress. |
| Informal firm Payment. | Full main loan plus compounded extra fees. | High risk of untracked funds and ongoing claims. | Default marks persist during staggered payments. | Avoid unrecorded deals. |
| Loan Restructuring. | Zero loan cut. increases total rates. | Contract renewed. default risks recur if income drops. | Reported as Restructured on CIBIL desk accounts. | Only if income is stable. |
| Court lawsuits (DRT). | Heavy legal fees. lawyers retainers. Court costs. | Adversarial multi-year contested lawsuits. | Marked Suit Filed or Wilful Default. | High stress. High cost. |
| Lok Adalat closure. | Modest 15% to 30% discount on total claim. | Non-appealable binding consent decree. | Marked Settled through Lok Adalat. | Useful for small claims. |
4. Technical CIBIL Algorithm & Section 21 CICRA Credit Restoration
Credit Information firms like TransUnion CIBIL. Experian. CRIF High Mark. Equifax compute credit scores using proprietary mathematical models weighted across five core parameters: Payment History (35%). Credit use Ratio (30%). Credit History Length and Mix (15%). Recent Inquiries (10%). Credit Exposure Leverage (10%). During active default. running 30-90-180 Days Past Due (DPD) entries cause a severe score contraction. Often dropping ratings from 780+ down into the 500-580 band.
Executing a formal closure through a hardship submission arrests this downward spiral. When the bank issues a closure sanction and updates the CIBIL desk record to 'Settled'. The unpaid dues is adjusted to zero. Permanently terminating monthly late notations. Under Section 21 of the Credit Information firms (rule) Act. 2005 (CICRA). Clients possess the legal right to ensure accurate reporting of debt discharge. By adopting a disciplined credit rebuilding plan. This includes secured credit cards backed by fixed deposits and flawless payment cycles. Clients regularly rebuild their CIBIL score back above 750 within 12 to 24 months.
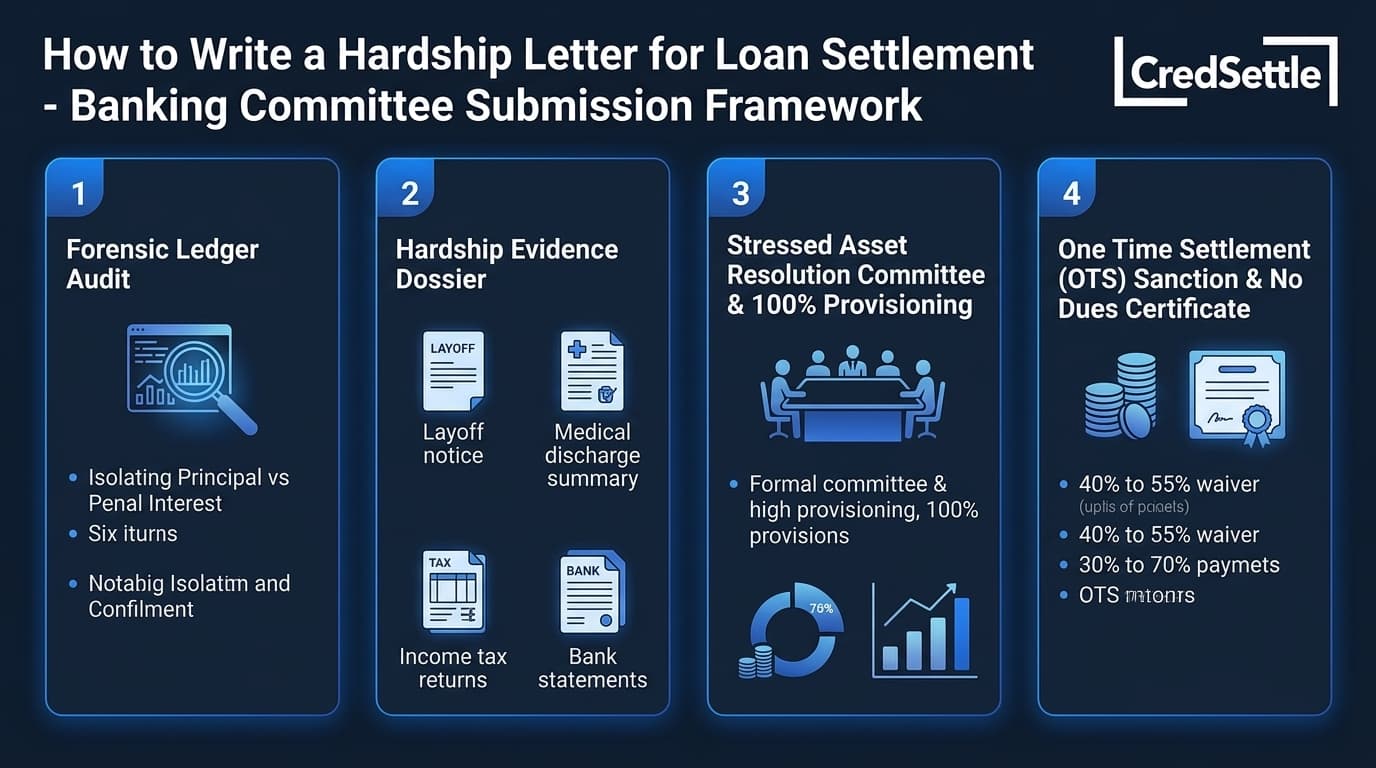
Visual Blueprint: Hardship Letter Submission Framework
5. Step-by-Step SOP: 6 Stages of Submitting a Stressed Assets Dossier
A successful OTS deal follows a disciplined office steps. Rather than sending informal emails or submitting casual letters to branch tellers. Clients must follow a standardized 6-stage protocol designed to satisfy bank banking audit standards.
Forensic Account Ledger Audit
Obtain signed loan records and unbundle excessive extra fees. Late fees. cover markups to determine the exact net main loan owed before initiating discussions.
Hardship Evidence Compilation
Assemble signed documentary proof including firm layoff letters. Revised jobs terms. Audited P&. L accounts. Hospital discharge papers. Bank records showing cash depletion.
Competent Authority Representation
Bypass commission-driven claims staff by submitting the formal hardship dossier straight to the bank Stressed Assets relief Branch (SARB) or Circle Credit boards via registered post and formal email.
Credit Committee Bilateral Talks
Engage with credit boards staff. Showing that an fast 40% to 55% OTS cash claims delivers higher net present value than protracted lawsuits on no-pledge exposures.
Sanction Letter Forensic Vetting
Thoroughly inspect the written deal sign-offs for formal bank letterhead. Precise OTS deal figures. Payment deadlines. Complete waiver clauses. Commitments for No Dues letter issuance.
Direct Remittance & NDC Issuance
Deposit the agreed closure funds straight into your loan account via RTGS or NEFT. Collect the stamped No Dues letter. Verify updated CIBIL desk records under Section 21 CICRA.
6. Statutory Notice Defense & Borrower Legal Safeguards
When clients miss debt installments. Banks often issue formal legal notices. grasp the legal anatomy of these notices ensures clients respond effectively without falling victim to unlawful threats or panic.
Section 25 PSSA: NACH Mandate Recall
clients can formally cancel automated NACH e-mandate deductions by serving written notice to their bank under Payment and closure Systems Act rules. Preventing repetitive bounce charges and reframing the matter as a civil debt claims.
Section 138 NI Act: Cheque Bounce Defense
Lenders cannot present undated pledge cheques for exaggerated claim amounts without providing checked account records. Documenting genuine hardship establishes lack of fraudulent intent. Helping pre-trial compoundable relief.
Arbitration: Perkins Eastman Precedent
Under Supreme Court rulings in TRF Limited and Perkins Eastman. Banks cannot unilaterally appoint sole arbitrators. Any unilateral hearing invocation can be formally challenged under Section 12(5) of the hearing and talks Act.
DRT Thresholds & Fair Practices Code
Debts claims Tribunals have legal police area only for claims exceeding ₹20 Lakhs. Also. The RBI Fair Practices Code strictly bans abusive claims tactics. Unannounced workplace intrusions. Contacting third-party references.
7. 3-Tier Grievance & Regulatory Escalation
If branch staff or claims firms ignore your hardship submission or violate fair debt claims rules. Clients can invoke the formal multi-tiered grievance redressal mechanism established by the Reserve Bank of India.
Grievance Redressal Officer
Submit a formal written reports regarding staff misconduct and request office review of your hardship dossier.
Principal Nodal Officer
Escalate unresolved requests to the bank main loan Nodal staff and Zonal Stressed Assets boards for executive OTS deal appraisal.
RBI Integrated Ombudsman
Lodge an enforceable legal reports through cms.rbi.org.in if the bank fails to provide a satisfactory relief within 30 days.
8. Chronological Timeline: 180-Day Resolution Path
grasp the lifecycle of stressed retail debt helps clients time their hardship submissions for maximum strategic leverage. Transitioning from initial default to complete debt discharge.
| Timeline | Account Status | Bank & Recovery Action. | Borrower Strategic Action. |
|---|---|---|---|
| Days 1 to 30 | SMA-0 default. | Automated payment reminders. Tele-calling alerts. | Conduct debt audit. evaluate restructuring vs closure. |
| Days 31 to 90 | SMA-1 / SMA-2 Stage. | outside to claims firms. intensive calls. | Compile hardship proofs. revoke NACH mandate in writing. |
| Days 91 to 120 | NPA Classification. | cash bank reserves allocated. file sent to SARB. | Submit full hardship dossier to SARB leadership. |
| Days 121 to 150 | boards Review. | Credit boards reviews hardship proofs and haircut. | settle 40% to 55% closure with full penal waiver. |
| Days 151 to 180 | OTS Sanction &. Closure. | Issuance of formal closure Sanction Letter. | Vet sanction terms. Pay payout sum. Secure NDC. |
9. Specialized Real-World Hardship Scenarios
debt stress manifests in various forms. Adapting your hardship presentation to match local underlying factors ensures bank credit boards quickly validate and approve OTS deal proposals.
Corporate Layoffs & Salary Cuts
Submit end notices. Severance closure records. Updated bank records illustrating sustained zero-income or pay cuts to secure rapid main loan waivers without lawsuits.
Medical Emergencies & Critical Illness
Provide signed hospital discharge summaries. Work invoices. And ongoing treatment estimates showing complete depletion of crisis savings reserves.
Business Collapse & Proprietorship Losses
Enclose audited balance sheets. GST surrender letters. Vendor default proofs to prove trade ruin while safeguarding own assets under SARFAESI Section 31(g).
Multi-Lender Portfolio Consolidation
Coordinate a synchronized hardship relief plan across multiple banking institutions. Preventing cross-lender reports and securing fair. Phased deals.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".