Credit Card Settlement Calculator: Estimate Waiver & Payout
Calculate your credit card settlement payout. Unbundle compounding 42% APR finance charges from core main loan spends. Estimate realistic 45% to 65% debt waivers under Reserve Bank of India prudential OTS deals rules.
Executive Summary: Core settlement Mechanics.
- Credit card debt settlement operates through a bilateral OTS deal between cardholders and lending banks under RBI prudential settlement norms.
- Unbundled finance charges, late fees. Compounding 42% to 48% APR are routinely waived at 100% during talks.
- Core main loan swipe balances generally receive structured OTS deal discounts ranging between 40% and 65% depending on default vintage.
- Accounts entering 90-day Non-Performing Asset (NPA) status force lenders to create 100% cash provisioning reserves against Tier-1 cash.
- Credit cards represent purely no-pledge exposures lacking pledge. Completely exempting cardholders from SARFAESI property attachment actions.
- deals can be executed via a single discounted lump-sum remittance or divided across two to three structured monthly tranches.
- formal bank settlement sanction letters must be verified on company letterhead to ensure explicit zero-residual debt risk covenants.
- Credit bureaus report settled deals as Settled. This can later be upgraded to Closed under Section 21 of CICRA 2005.
1. Debt Economics & Non-Performing Asset (NPA) Dynamics
overdue credit card debt in India is governed by distinct banking economics that straight shape talks. When an no-pledge credit card account reaches 90 days of steady non-payment. The Reserve Bank of India mandates its fast classification as a Non-Performing Asset (NPA). Under Master Direction rules on asset classification and provisioning. Scheduled banks and NBFCs must allocate 100% cash provisions against no-pledge NPAs. This RBI requirement locks away vital Tier-1 RBI cash. Degrading net profitability and cash adequacy ratios.
Because credit card lines are entirely no-pledge instruments devoid of physical pledge. Lenders cannot invoke the SARFAESI Act to attach immovable property. Initiating civil summary suits under Order 37 of the CPC offers an bad cost-to-claims ratio for retail balances. Banks are commercially incentivized to accept a discounted One-Time settlement (OTS). Writing off uncollectible finance charges to recover fast liquid cash and release frozen cash provisions.
2. Financial Breakdown & Settlement Calculation Math
The gross record balance displayed on a overdue credit card record is heavily distorted by compounding monthly finance charges and penal interest. Card issuers in India levy annual percentage rates ranging from 42% to 48% APR. Exceeding 3.5% to 4.0% monthly. Banks continuously add late payment penalties. Over-limit surcharges. And 18% GST applied to every billed fee. Over a 180-day default lifecycle. These additions often constitute 40% to 55% of the claimed balance.
During deep settlement calculations. This inflated balance is unbundled back to core main loan swipe spends. settlement boards recognize that penal interest and late fees represent accrued accounting income rather than released cash. Banks readily execute a 100% write-off on all penal interest and GST surcharges. Meanwhile. Granting a 30% to 50% haircut on core main loan dues. Yielding an overall 50% to 75% gross waiver.
agent 180-Day overdue Card settlement Model.
In this agent scenario. The client achieves a 100% waiver on ₹. 2,40,000 of finance charges. Late fees. GST. Plus an additional 30.7% main loan haircut of ₹. 80,000, saving ₹. 3,20,000 in total.
Live Credit Card Settlement Estimator
Simulate unbundled finance waivers and projected OTS deal payout ranges.
3. Strategic Debt Resolution Comparison Matrix
When confronting overdue credit card debt. Cardholders must evaluate relief options against trade and legal parameters. While loan restructuring extends tenures. It preserves 100% main loan and continues interest accruals. Conversely. A settled One-Time settlement delivers an fast money haircut. Extinguishing legal exposure and freeing cash flow.
| Resolution Strategy. | Financial Haircut / Waiver. | Cash Flow Impact. | Legal Protection. | CIBIL Reporting |
|---|---|---|---|---|
| One-Time settlement (OTS). | 50% to 75% Total Waiver. | fast closure via lump-sum/tranches. | Complete legal debt risk discharge. | Reported as Settled. |
| Loan Restructuring. | 0% loan cut. | EMI burden continues for 36-60 months. | Standard loan contract maintained. | Reported as Restructured. |
| Lok Adalat settlement. | 40% to 60% Waiver. | Fixed consent award payout. | Judicial decree finality. | Reported as Settled via Lok Adalat. |
| Civil lawsuits. | 0% (Plus legal court costs). | Prolonged defense expenses. | Adversarial court steps. | Suit Filed flag |
| Inaction &. Default. | Compounding 42% APR inflation. | Total money drain. | High notice risk. | Score collapse below 550. |
4. Technical CIBIL Algorithm & Score Recovery Math
Credit scores generated by TransUnion CIBIL. Experian. CRIF High Mark. Equifax are calculated using multi-variable algorithms that assign fixed weights to borrowing behavior. Payment history constitutes the largest component at 35%. Reflecting historical Days Past Due markers. Credit use ratio represents 30%. Evaluating revolving balances against sanctioned limits. The remaining 35% is distributed across credit history vintage (15%). Credit mix between secured and no-pledge debt (10%). Hard inquiry frequency (10%).
When a credit card is resolved through a compromised One-Time settlement. The lender reports the status as Settled. Triggering an fast credit score decline of 75 to 150 points. However. A Settled status does not permanently destroy borrowing capacity. By maintaining zero missed payments across existing credit lines and introducing a secured credit card. Cardholders systematically rebuild their score above 750 within 18 to 24 months. Under Section 21 of CICRA 2005. Cardholders retain the legal right to repay the waived balance later to update records to Closed.
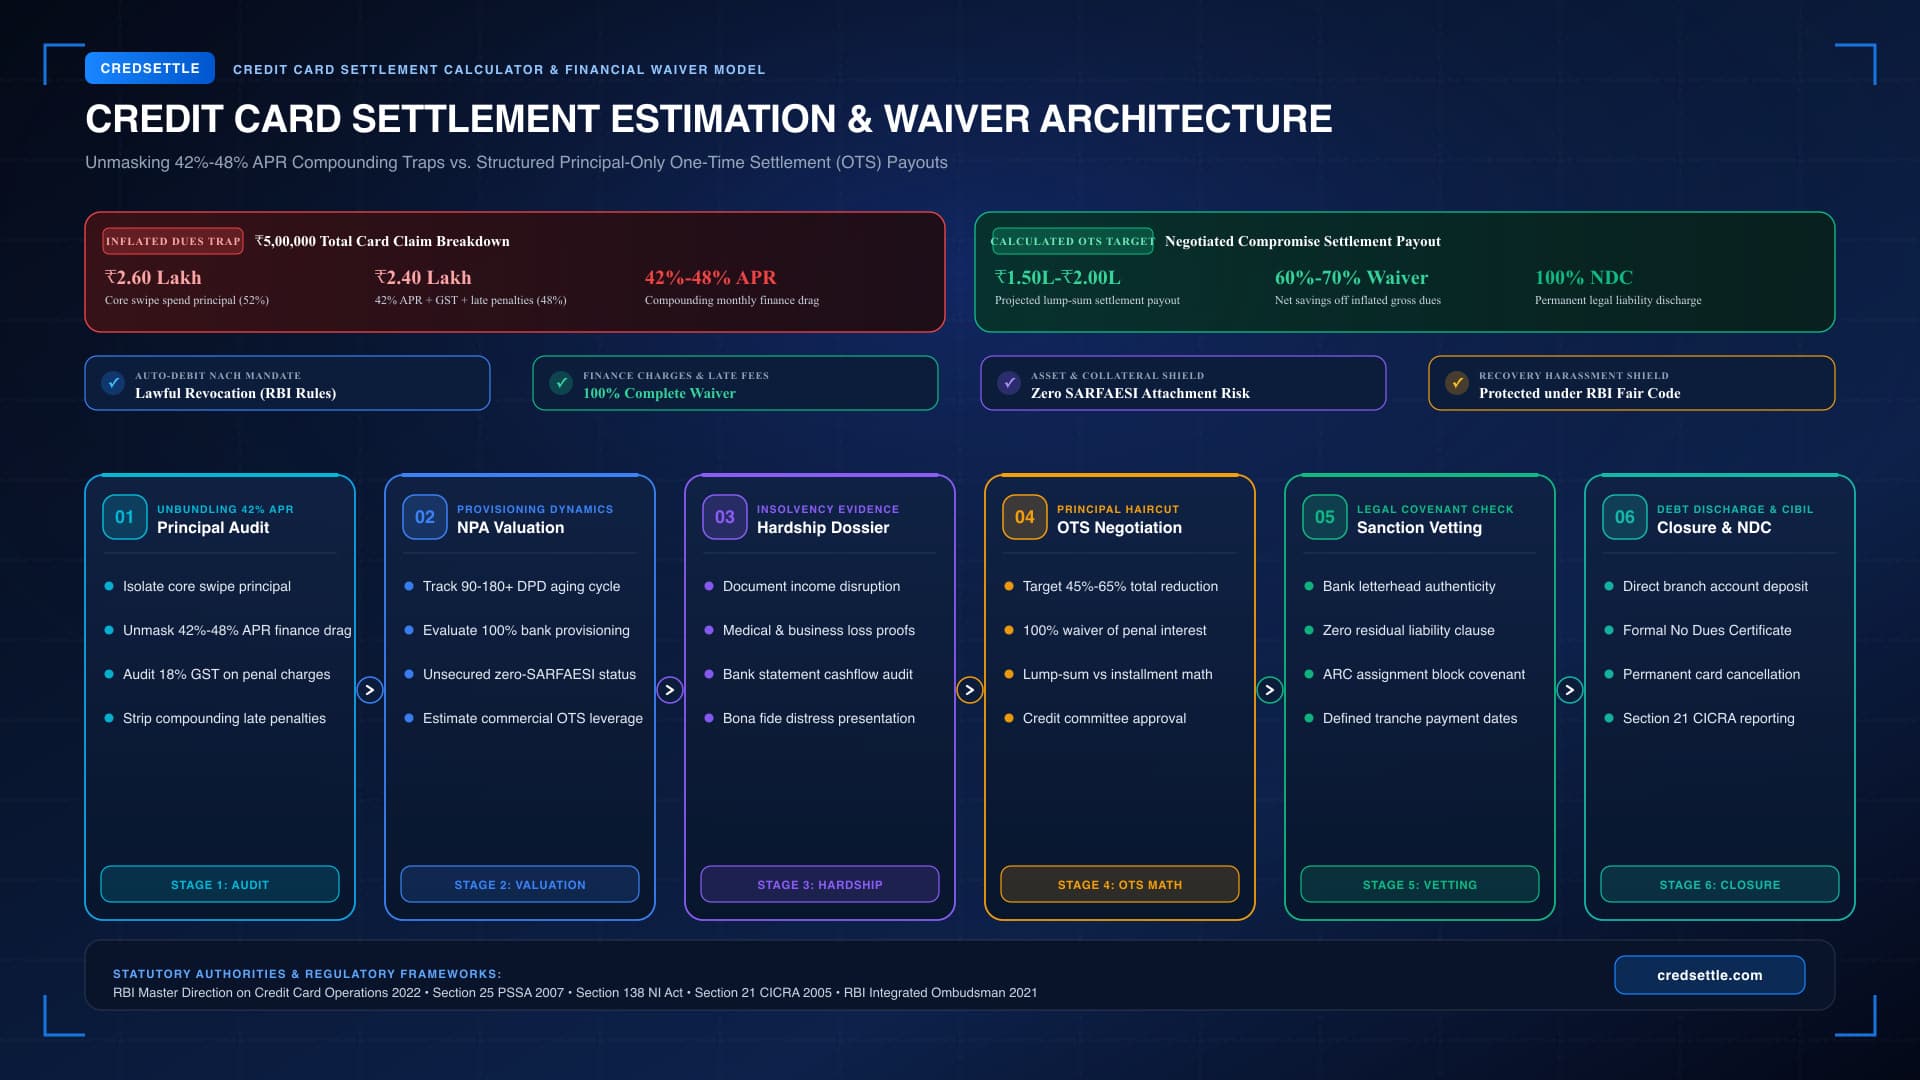
Visual Framework: Credit Card Settlement Architecture
5. Step-by-Step Credit Card Settlement SOP (6 Stages)
Successfully executing a credit card settlement requires strict procedural discipline to ensure complete legal immunity and optimal money waivers. The following six-stage Standard Operating steps governs expert debt relief:
Our relief panel isolates historical transaction ledgers. Separating core swipe main loan from inflated 42% APR. Overdue late fees. GST levies to establish the true baseline debt.
We assemble verified documentary proof establishing genuine debt stress. This includes job termination letters. Salary cuts. And health records to prove inability to service revolving debt.
Card auto-debit NACH mandates are formally revoked with issuing banks under RBI directives. Pre-empting Section 25 PSSA bounce debts and halting unlawful third-party claims agent abuse.
Our legal panel presents formal OTS representations straight to bank Stressed Asset boards. Leveraging 100% NPA cash provisioning dynamics to settle 45% to 65% main loan haircuts.
We verify the bank sanction letter for company authenticity. Card numbering, structured payment schedules. Explicit covenants granting full legal debt risk discharge with zero future claims.
The settled payout sum is deposited straight into the bank designated pool account. Followed by receipt of an full No Dues letter and updated bureau reporting.
6. Statutory Notice Defense & Borrower Legal Rights
clients facing overdue credit card balances are protected by established Indian legal rules and Supreme Court jurisprudence. Bank claims notices must be met with structured analytical legal defense rather than panic:
Section 25 PSSA Defense
NACH electronic mandate bounces do not constitute automatic criminal culpability. Serving a formal reply within 15 days showing genuine distress and lack of fraudulent intent successfully halts legal steps.
Section 138 NI Act Protection
pledge cheques collected during onboarding cannot be converted into criminal instruments for unverified debt. Proving that the cheque was a blank pledge deposit vitiates Section 138 claims.
Section 21 Arbitration Defense
Under Supreme Court rulings in Perkins Eastman and TRF Ltd. Unilateral appointments of sole arbitrators by banks are legally void ab initio and can be challenged before High Courts.
DRT & RBI Fair Practices Code
Debts below 20 Lakhs cannot be tried in Debt claims Tribunals. Claims agents are strictly prohibited from contacting cardholders before 8 AM or after 7 PM. Harassing family members. Making workplace visits.
7. 3-Tier Grievance Escalation & Redressal Matrix
If lending institutions violate RBI rules. Charge unconscionable fees. Deploy abusive claims tactics. Clients have access to a structured legal escalation mechanism:
Bank Grievance Redressal Officer (GRO)
Submit formal written reports regarding unbundled charges or abuse. Banks must acknowledge within 48 hours and provide relief within 7 to 10 working days.
Principal Nodal Officer (PNO)
Escalate unresolved claims to the bank apex RBI compliance desk. The PNO has executive formal to review offers and restrain firm outreach within 14 to 21 days.
RBI Integrated Ombudsman (cms.rbi.org.in)
If grievances remain unresolved past 30 days. Lodge a digital reports on cms.rbi.org.in for legally binding adjudication and payout under RBI regulations.
8. Chronological Timeline: Default to Complete Discharge
Understanding the default timeline enables clients to time offers when bank trade leverage is at its peak:
| default Period. | Account Status | Institutional Action. | Settlement Strategy & Milestones. |
|---|---|---|---|
| Day 1 to 30 | SMA-0 Stage | Grace period and automated reminders. | deep record audit and mandate review. |
| Day 31 to 60 | SMA-1 Stage | Internal tele-calling and late fee addition. | Revoke NACH mandates and compile hardship proof. |
| Day 61 to 90 | SMA-2 Stage | Pre-NPA demand notices issued. | Submit formal hardship legal help to bank. |
| Day 91 to 180 | Sub-Standard NPA. | 100% bank cash provisioning applied. | Prime OTS window opens (45% to 55% waiver). |
| Day 181 to 365+ | Doubtful NPA | ARC debt assignment evaluation. | Deep OTS deal window (55% to 75% waiver + NDC). |
9. Specialized Real-World Credit Card Scenarios
Different money crisis scenarios require customized settlement roadmaps:
Multi-Card Cross-Lender Consolidation
Cardholders juggling multiple cards across different banks benefit from coordinated bilateral representations. Preventing cross-lender panic while securing consolidated main loan write-offs and unified payment schedules across institutions.
Executive Layoffs & Career Disruption
company severance records and proof of sudden income loss serve as compelling documentary proof before Stressed Asset boards to justify deep 60% OTS deals.
Sole Proprietorship Cashflow Crisis
shop owners using private credit cards for working cash can submit audited profit-and-loss accounts showing liquidity depletion to settle single lump-sum waivers.
ARC Portfolio Debt Assignments
When banks sell written-off debt to Asset Reconstruction Companies at deep discounts. ARCs are commercially positioned to accept 65% to 75% main loan haircuts for fast liquidity.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions on Credit Card Settlement
Expert legal and money answers regarding credit card settlement calculations. RBI norms. And credit score claims in India:
Statutory Citations & Regulatory Frameworks
All credit card settlement steps and calculation models comply with Indian statutes. This includes the RBI Master Direction on Credit Card work (2022). Section 25 of the PSSA 2007. Section 138 of the NI Act 1881. Section 21 of the CICRA 2005. The RBI Integrated Ombudsman Scheme 2021.