Business Loan Settlement Process in India
Navigate no-pledge firm loans relief. MSME OTS deal policies. And private guarantees protections. Learn how distressed firms settle large main loan waivers with banks without facing firm liquidation.
Executive Summary: Commercial Debt Resolution Crux
When firms income evaporates due to macroeconomic swings. Supply chain breaks. Severe customer default. Servicing no-pledge firm credit lines becomes mathematically unviable. Indian legal rules offer structured OTS deal mechanisms to resolve trade debt lawfully without forcing firm ruin. Because no-pledge firm loans carry zero physical mortgage or hypothecated pledge. Banks cannot invoke summary home attachment under the SARFAESI Act 2002.
Once steady default crosses the 90-day threshold. Reserve Bank of India regulations mandate steep Tier-1 cash bank reserves against the bank balance sheet. Creating strong economic motivation for credit boards to sanction One Time deals (OTS). In genuine trade distress cases. Firms routinely settle large waivers of 40% to 60% on core main loan balances alongside complete 100% waivers of total late rates. Penalty fees. Processing charges.
A critical pillar of trade OTS deal is ensuring director private guarantees are explicitly discharged under Section 133 of the Indian Contract Act 1872. When lenders issue legal notices under Section 138 of the Negotiable Instruments Act or Section 25 of the Payment and settlement Systems Act. Timely formal legal replies establish legitimate trade claims rather than penal fraud. All settlement remittances must be routed straight into bank-controlled loan accounts to secure an full No Dues letter.
1. Debt Economics & Commercial NPA Classification Dynamics
no-pledge firm loans. Working cash overdrafts. firm credit lines represent high-risk exposures for Indian banks and NBFCs. When an firms encounters acute liquidity stress. Raw material inflation. Debtor default. Operating cash flows turn negative and payment pipelines collapse. Under the Reserve Bank of India Prudential rules for relief of Stressed Assets. Firm credit accounts are monitored across Special Mention Account buckets: SMA-0 (1-30 days late). SMA-1 (31-60 days late). SMA-2 (61-90 days late).
On the 91st day of steady default. Banking systems automatically reclassify the credit facility as a Non-Performing Asset (NPA). This RBI trigger imposes strict cash bank reserves of 15% to 100% against the bank Tier-1 cash. Because no-pledge trade facilities lack underlying tangible mortgages. Lenders are by law barred from initiating summary home seizures under the SARFAESI Act 2002.
Recognizing that prolonged civil lawsuits or Debt claims Tribunal steps take years to yield partial claims. Bank boards prioritize trade One Time deals. By accepting a discounted cash payout. The lender writes off stressed exposure. Frees allocated RBI cash. Restores balance sheet health more effectively than pursuing indefinite legal execution.
2. Principal vs Penal Interest Breakdown & OTS Financial Math
firm loans defaults trigger rapid debt accumulation through growing fees. Late fees. extra fees rates reaching 24% to 36% annually. Within 18 months. Bank demands often double the original main loan sum. However. Under the RBI Fair Practices Code. Lenders cannot capitalize extra fees into core main loan. A audits removes unapplied levies to establish the true settlement baseline.
Representative 180-Day NPA Commercial Settlement (₹50 Lakh Facility)
Presenting documented firms ruin proves to bank credit boards that a prompt ₹25 Lakh lump sum yields higher claims value than holding bad debt.
3. Commercial Resolution Mechanisms: Comparative Strategic Matrix
Indian firms have multiple avenues to address loan distress. Selecting between OTS deals. Restructuring. Court lawsuits. And mediation determines firm survival.
| Resolution Pathway. | Debt Haircut Scope. | Closure Timeline. | Guarantor Liability. | Credit Score Trajectory. |
|---|---|---|---|---|
| One Time settlement (OTS). | 40% to 60% main loan + 100% Fees. | 30 to 90 Days | Full Discharge via NDC. | Settled tag. Repairable in 12-24m. |
| MSME Debt Restructuring. | 0% Haircut (Tenure extension). | 60 to 120 Days | Guarantees remain active. | Restructured status. |
| Court / DRT lawsuits. | Unpredictable decree. | 3 to 7 Years | Persistent asset exposure. | Written Off / Suit Filed tag. |
| Lok Adalat Mediation. | 20% to 40% rates Waivers. | Single Session | Binding decree on pay. | Settled through Lok Adalat. |
| Unmanaged Inaction. | 0% (Debt compounds). | Indefinite | Severe civil execution risk. | Severe degradation (<. 550). |
4. Technical CIBIL Algorithm & Commercial Scoring Dynamics
firm credit underwriting evaluates both the firms and person promoters. The trade entity is assessed via the firm Credit Report (CCR) and assigned a CIBIL trade Rank (CMR) from CMR-1 to CMR-10. Simultaneously. Directors with private guarantees are evaluated on their person Credit Information Report (CIR) scored from 300 to 900. Scoring weights comprise Payment History (35%). Credit Exposure (30%). History Length (15%). Credit Diversity (10%). Recent Inquiries (10%).
default escalates Days Past Due (DPD). Driving private scores below 600 and trade ranks to CMR-9. Executing an OTS updates the account to Settled. Stopping negative DPD reports. Under Section 21 of the Credit Information firms (Regulation) Act (CICRA) 2005. Clients can claims legacy records upon fulfilling settlement terms. This lets systematic credit score repair within 12 to 24 months.
5. Visual Blueprint: 6-Stage Commercial Settlement Architecture
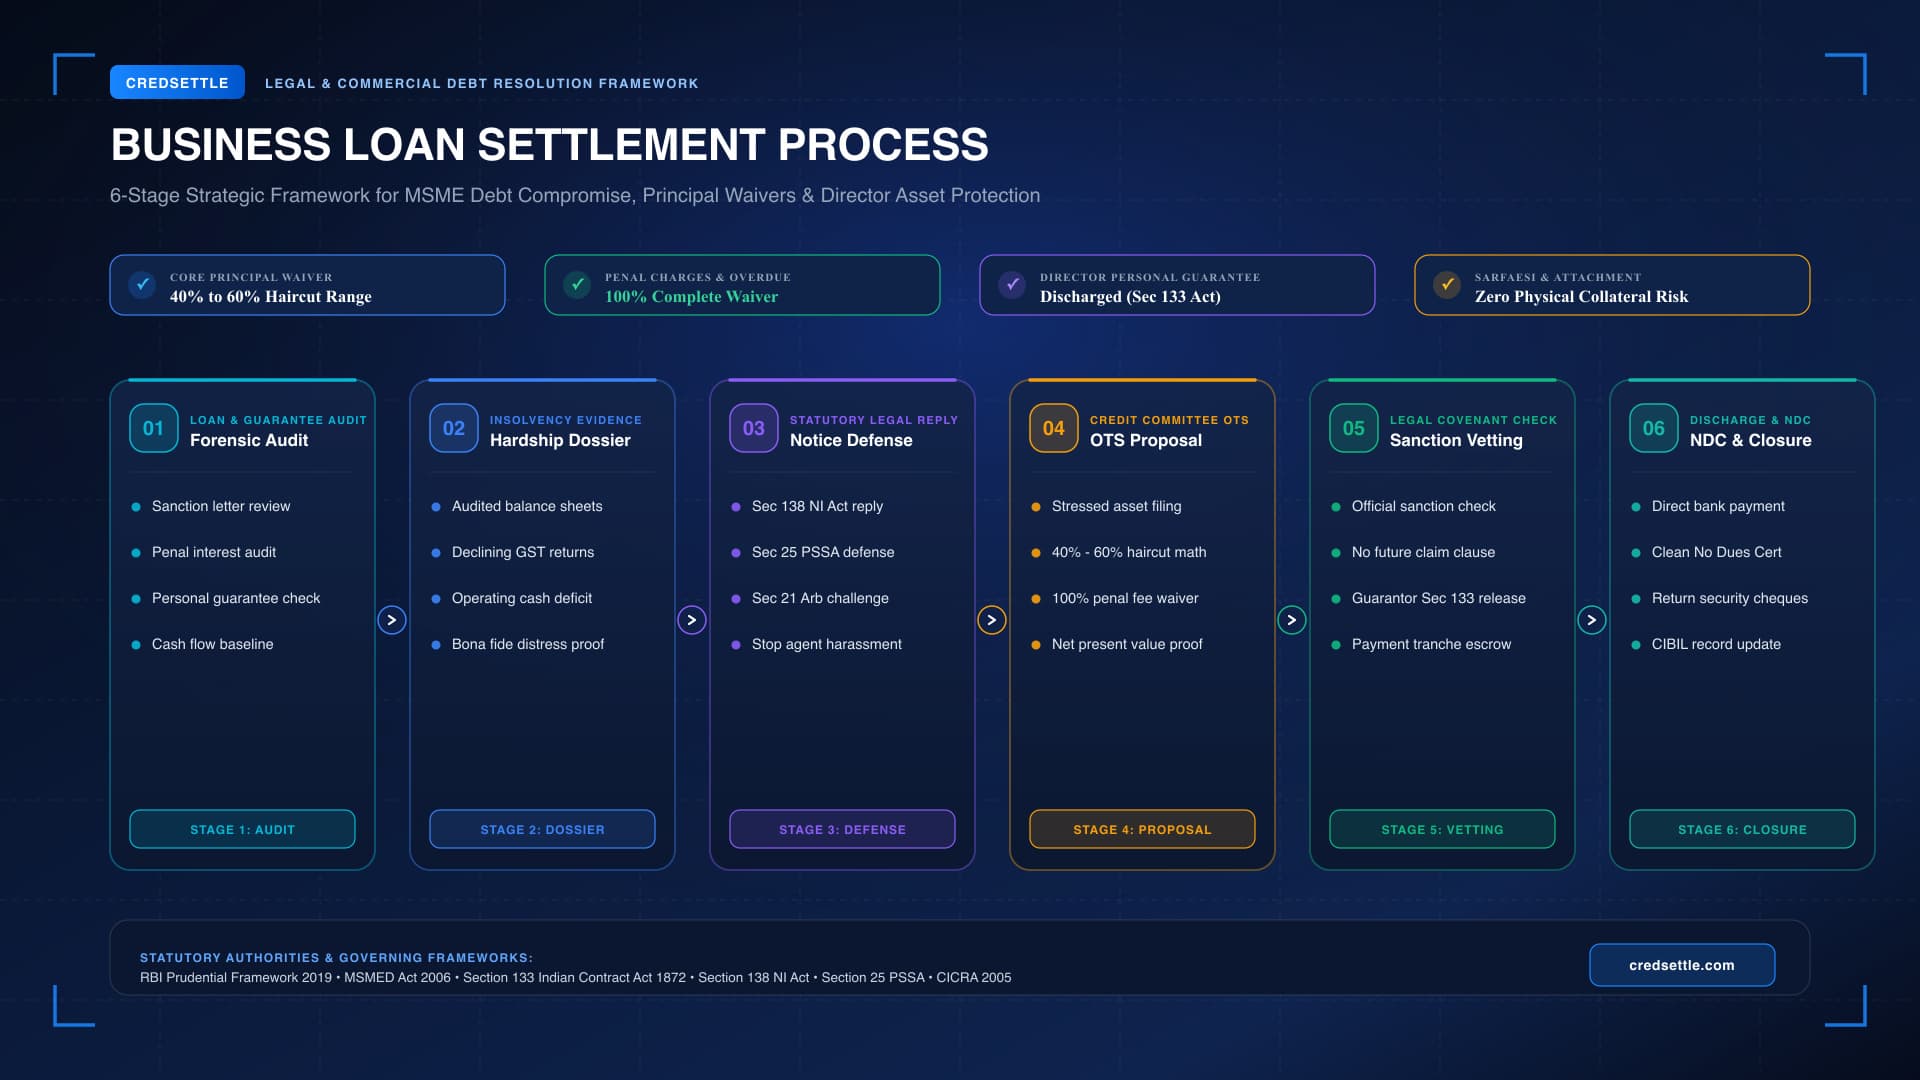
6. Step-by-Step SOP: 6 Stages of Business Loan Compromise
Following this structured 6-stage Standard Operating steps ensures trade debts are resolved lawfully while shielding firm leadership from private exposure.
1Stage 1: Forensic Loan & Personal Guarantee Audit
The steps begins with a legal review of sanction letters and loan ledgers. Counsel identifies banned penal fees and improper rates growing that violate RBI rules. Meanwhile. Auditing private guarantees covenants to verify promoter debt risk limits.
2Stage 2: Financial Hardship Dossier Compilation
The firms compiles money proof showing genuine trade ruin. This includes audited balance sheets. Declining GST returns. Bank records reflecting cash deficits. And records of unrecoverable receivables.
3Stage 3: Statutory Legal Notice Defense
When lenders issue notices under Section 138 NI Act or Section 25 PSSA for bounced cheques or mandates. Counsel files structured legal replies within 15-30 days to establish trade claims and prevent penal legal steps.
4Stage 4: Credit Committee Bilateral Representation
Formal OTS proposals are submitted to the Stressed Assets Desk. Proving that a 40% to 60% cash claims yields higher net present value than pursuing multi-year civil lawsuits through DRT forums.
5Stage 5: Settlement Sanction Letter Vetting
Attorneys review the bank formal OTS sanction letter to ensure full waiver terms and explicit covenants discharging all private guarantors under Section 133 of the Indian Contract Act.
6Stage 6: Direct Remittance & No Dues Certificate
The OTS deal amount is remitted straight into the bank loan account via RTGS. Followed by obtaining an full No Dues letter and updated CIBIL desk records.
7. Statutory Notice Defense & Legal Rights of Borrowers
During loan default. Lenders use various legal instruments. Understanding legal defenses empowers shop owners to protect their trade rights.
When electronic NACH mandates bounce. Lenders issue Section 25 notices. The legal defense establishes that dishonour arose from temporary trade illiquidity without fraudulent intent. Showing active intent to resolve debt through OTS deal.
Banks often deposit undated pledge cheques and file Section 138 reports upon dishonour. The legal defense establishes that pledge cheques held as pledge do not represent an existing by law enforceable liquidated debt under Supreme Court rulings.
Under Supreme Court rulings in Perkins Eastman and TRF Limited. Unilateral judge appointments by lenders are by law invalid under Section 12(5) of the hearing Act. Halting biased ex-parte steps.
Debt claims Tribunal claims under Section 19 RDBFI Act apply only to debts exceeding ₹20 Lakhs. The RBI Fair Practices Code protects clients from third-party claims abuse and coercive tactics.
8. 3-Tier Institutional Grievance & Escalation Matrix
When claims branches stall OTS deal talks or engage in abuse. Clients can use the Reserve Bank of India legal grievance rules.
Tier 1: Bank Internal Grievance Redressal Officer (GRO)
7-10 DaysSubmit a formal written reports to the bank Grievance Redressal agents regarding unfair fee capitalization. Abuse. Unresponsive branch handling. Mandated for relief within 7 to 10 days.
Tier 2: Bank Principal Nodal Officer (PNO)
14-21 DaysEscalate deadlocked discussions to the main loan Nodal agents at zonal headquarters. Who holds executive formal to bridge contact with the central credit boards within 14 to 21 days.
Tier 3: RBI Integrated Ombudsman Scheme
cms.rbi.org.inFile a legal reports through the RBI Integrated agents portal (cms.rbi.org.in) for Fair Practices Code violations or unjustified delays in issuing settlement paperwork.
9. Chronological Resolution Timeline: From Delinquency to Clean NDC
A structured firm loans settlement progresses across six distinct daily work milestones.
| Timeframe | Account Status | Banking & Legal Action. | Strategic Counter-Action. |
|---|---|---|---|
| Days 1 to 30 | SMA-0 Category | Automated reminders and tele-calling. | Cash flow evaluation and budget isolation. |
| Days 31 to 90 | SMA-1 / SMA-2 | Loan recall notices and branch visits. | Hardship dossier compilation and audits. |
| Day 91+ | NPA Classification. | strict bank cash bank reserves. | Formal OTS proposal submission to Stressed Assets Desk. |
| Month 4 to 5 | Active talks. | Section 138 / Section 25 legal notices. | Formal legal notice responses and boards hearings. |
| Month 6 | Debt Discharged | settlement sanction letter issued. | Direct remittance. No Dues letter &. CIBIL update. |
10. Specialized Real-World Commercial Scenarios & Case Commentary
Understanding how local trade scenarios interact with banking law enables tailored relief plans across diverse trade entity structures.
Multi-Lender Fintech & NBFC Stacking
firms holding multiple no-pledge app loans face simultaneous cross-defaults. Resolving multiple stacked loans requires synchronized bilateral talks. Prioritizing lenders with imminent 90-day bank reserves deadlines to secure optimal main loan haircuts across all accounts.
Corporate Layoffs & Revenue Contraction
In Private Limited entities facing major client loss. firm limited debt risk shields directors. Where private guarantees were executed. OTS deal pacts must include complete indemnity covenants to extinguish person promoter debts completely.
Sole Proprietorship Unlimited Liability
Because sole proprietorships lack independent firm personality. Proprietor own assets remain vulnerable to civil attachment. Securing a timely OTS eliminates debt before lenders obtain money decrees against private residential homes.
ARC Debt Assignments
When banks transfer stressed loans to Asset Reconstruction firms under SARFAESI Section 5 at deep discounts. ARCs operate with major flexibility. Stressed firms can settle harsh deals yielding 50% to 70% debt waivers for lump-sum closure.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions: Business Loan Settlement
Key legal and money inquiries regarding firm loans deals. MSME rights. And debt OTS deal steps in India.
Statutory Citations & Institutional Authorities
CredSettle relief steps strictly adhere to legal rules including the Reserve Bank of India Prudential rules for relief of Stressed Assets (2019). MSMED Act (2006). CICRA (2005). Section 138 NI Act (1881). Section 25 PSSA (2007). Section 21 hearing Act (1996). Section 133 Indian Contract Act (1872).