Kotak Mahindra Bank Loan Settlement
bank legal plan for resolving late Kotak private loans and 811 online credit lines. Learn how to counter unilateral hearing notices. Avert Phoenix ARC debt assignments. settle 40% to 55% main loan haircuts with an formal No Dues letter.
- bank police area: Adjudicated by Kotak Stressed Assets handling Group (SAMG) after 90 days of default (NPA).
- no-pledge pledge Immunity: private loans and 811 online credit carry zero mortgage rights under SARFAESI Section 31(g).
- Complete Surcharge Waiver: 100% legal waiver on growing extra fees. Late payment penalties. bounce fees.
- main loan Haircut Benchmark: Realistic OTS deal figures target 40% to 55% discounts on core remaining main loan.
- Phoenix ARC Assignment Risk: Delinquencies past 120-180 days risk assignment to Phoenix ARC. Requiring preemptive OTS intervention.
- Sole hearing Counter: Unilateral judge appointments by Kotak are by law invalid under Supreme Court Perkins Eastman rulings.
- Section 25 PSSA Defense: E-mandate bounce notices are compoundable matters routinely defused through formal legal replies.
- Definitive Legal Closure: Remittance straight to Kotak CBS loan account followed by an authentic No Dues letter within 30-45 days.
Kotak Mahindra Debt Economics and NPA Classification Dynamics
Kotak Mahindra Bank manages a vast no-pledge portfolio spanning private loans. Express credit. 811 online facilities. When a client faces money breaks. The account advances through Special Mention Account stages: SMA-0 (1-30 days). SMA-1 (31-60 days). SMA-2 (61-90 days). Escalating from automated reminders into telecalling claims firm contact.
At 90 days of default. RBI prudential norms mandate classifying the facility as a Gross Non-Performing Asset (NPA). Because no-pledge private loans carry zero mortgage pledge under SARFAESI Act Section 31(g). Kotak cannot seize home or freeze assets without protracted lawsuits. Faced with strict 100% Tier-1 cash bank reserves. Kotak&apos. s Stressed Assets handling Group (SAMG) prefers settling a trade One-Time settlement to clear bad debt off its balance sheet.
Understanding Kotak Mahindra Loan Charges & Settlement Options
late Kotak loan balances swell rapidly beyond borrowed main loan due to 24%-36% growing extra fees. Recurring NACH bounce surcharges. GST. bank talks begin with a audits to strip away these artificial levies and isolate the core remaining main loan baseline.
For accounts past 90-180 days of NPA classification. Kotak routinely sanctions a 100% waiver on all penal and office charges. Alongside a 40% to 55% haircut on the core base loan.
Gross Bank Claim.
₹8,50,000
Includes extra fees & bounce fees.
Penal Surcharges Stripped.
₹2,10,000
100% full bank waiver.
Core remaining main loan.
₹6,40,000
checked baseline exposure.
Sanctioned OTS Figure.
₹3,20,000
50% main loan haircut (62% total relief).
Kotak Settlement vs Restructuring & Alternate Pathways
clients facing persistent loan distress often consider loan restructuring or Lok Adalat referrals without evaluating the long-term money results. Restructuring merely extends the tenure while growing base rates. In contrast. Outright default neglect triggers legal notices and potential assignment to private debt buyers. The comparative matrix below outlines the critical parameters governing each relief route.
| Resolution Route. | Waiver Potential. | Settlement Timeline. | Legal Immunity | Credit Impact |
|---|---|---|---|---|
| One-Time settlement (OTS). | 100% penal + 40%-55% main loan haircut. | 45 to 90 days | Complete withdrawal of all notices & suits. | Reported as Settled. rebuildable in 18-24 mos. |
| Tenure Restructuring. | 0% waiver. higher overall rates debt risk. | 3 to 5 extended years. | Conditional upon strict monthly EMI compliance. | Marked as Restructured. score suppresses. |
| Civil Court lawsuits. | Determined by decree. high lawyers costs. | 3 to 7 years | Ongoing court appearances & summons risks. | Severe derogatory suit-filed entries. |
| National Lok Adalat. | Full penal waiver + 20%-35% main loan cut. | Quarterly sittings. | Final award under Legal Services officials Act. | Reported as Settled under Lok Adalat. |
| Inaction & Default Neglect. | 0% waiver. growing penal ballooning. | Indefinite distress. | Sec. 25, Sec. 138 & ARC assignment risks. | Score drops below 600. total credit freeze. |
Kotak Default Impact on CIBIL & Section 21 CICRA Relief
TransUnion CIBIL scores depend heavily on payment history (35%) and credit exposure (30%). Consecutive default triggers an fast 80-130 point drop. Once an authorized OTS concludes. Kotak updates CIBIL desk records to ". Settled". With zero balance. Promptly arresting further negative monthly reporting marks.
clients can rebuild a 750+ score within 18 to 24 months through disciplined use on a secured fixed-deposit card. Also. Under Section 21 of the Credit Information firms (Regulation) Act. 2005 (CICRA). Clients retain the right to petition credit bureaus for claims rectification. Converting records to ". Closed". Upon settling residual OTS deal balances.
Kotak Mahindra Bank Loan Settlement Institutional Roadmap
The visual rules below summarizes CredSettle&apos. S proven six-stage process for navigating Kotak Mahindra Bank private loans defaults. Countering hearing threats. Preventing Phoenix ARC transfers. Securing enforceable OTS deal sanctions.
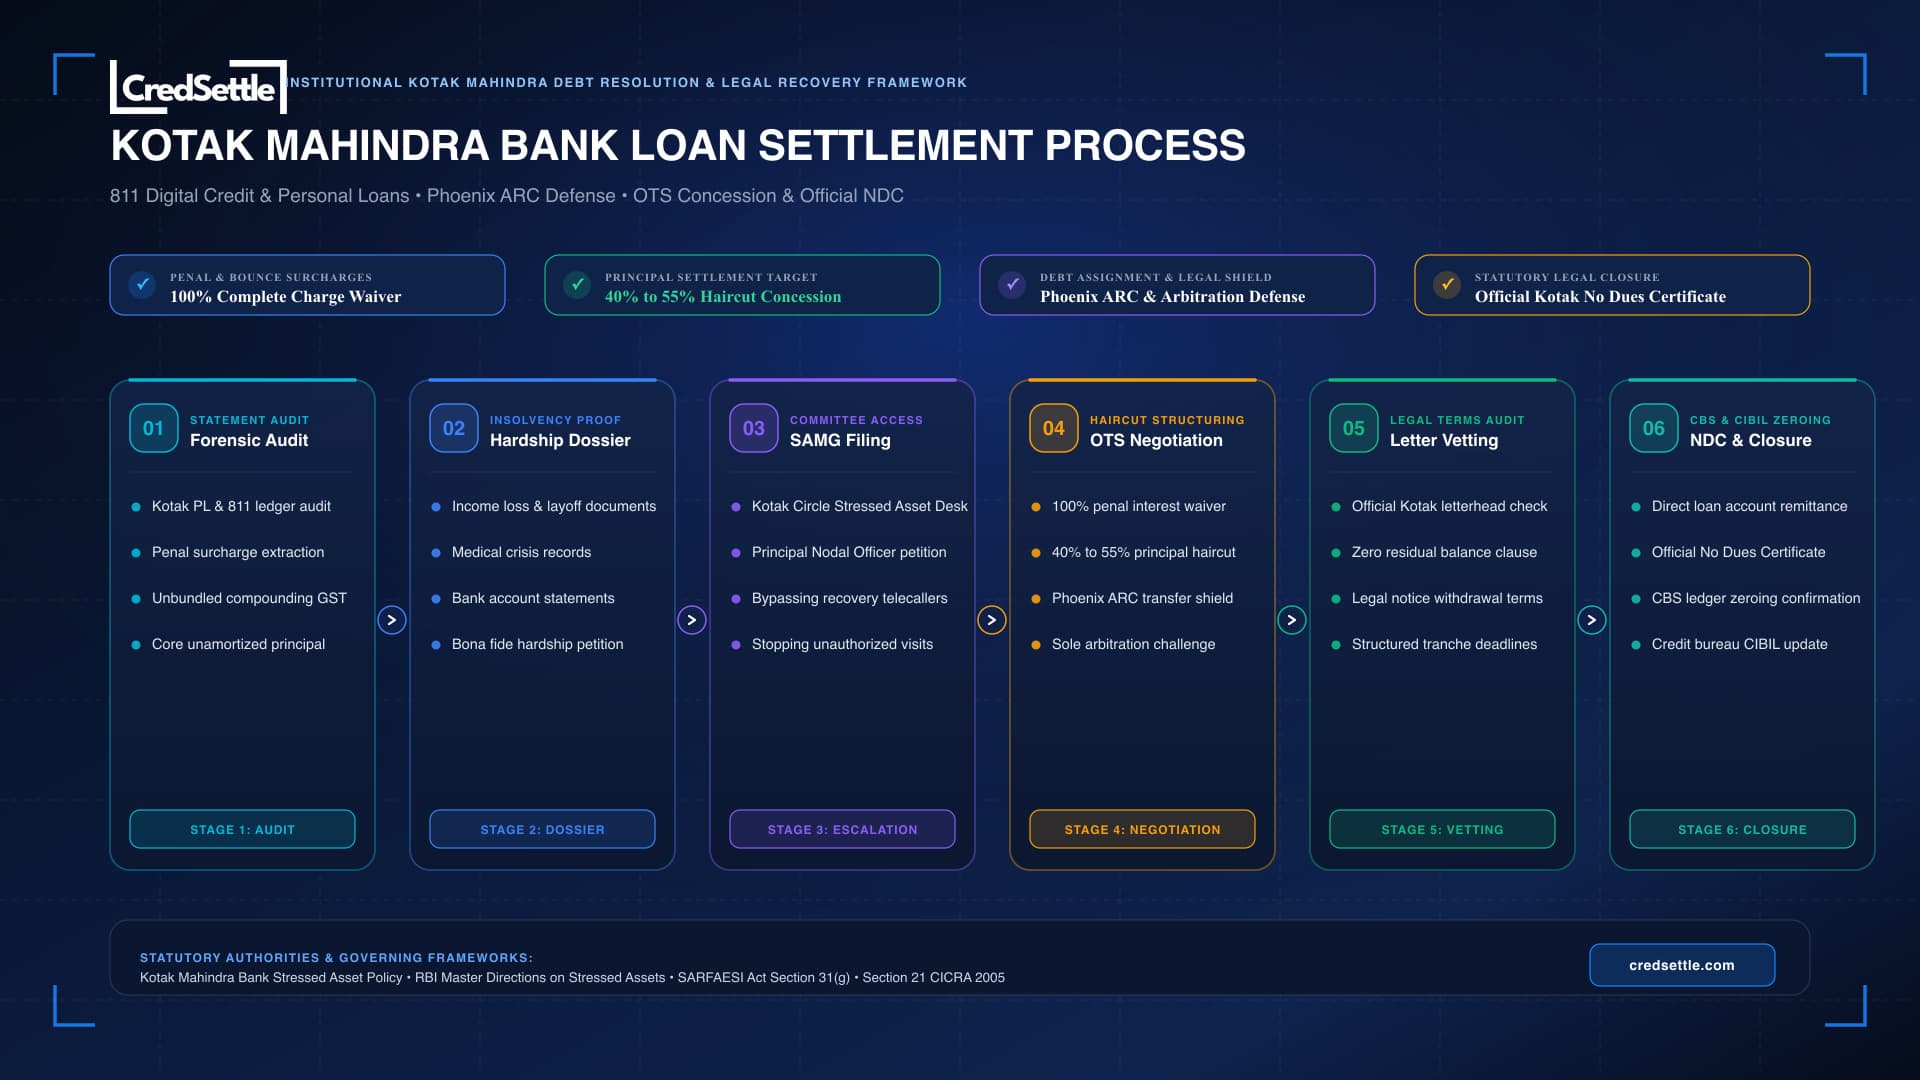
Step-by-Step Institutional SOP for Kotak Mahindra Loan Settlement
Stage 1: Forensic Statement and 811 Ledger Audit
We audit your Kotak record or 811 ledger to strip total extra fees. GST debits. Bounce fees. Isolating the true remaining main loan baseline.
Stage 2: Comprehensive Hardship Dossier Compilation
We assemble checked hardship proof. This includes layoff letters. health hospitalization bills. Or trade closure accounts. Establishing genuine ruin to the credit boards.
Stage 3: Stressed Assets Management Group (SAMG) Representation
We bypass third-party claims telecallers. Serving formal legal legal help to Kotak&apos. s Stressed Assets handling Group and main loan Nodal agents to halt abuse.
Stage 4: Bilateral Compromise Negotiations and Haircut Structuring
Senior negotiators engage circle boards to secure a 100% penal surcharge waiver and a 40% to 55% main loan haircut. Preventing portfolio transfer to Phoenix ARC.
Stage 5: Official Settlement Sanction Letter Vetting
Our legal counsel vets Kotak&apos. S formal sanction letter on bank letterhead. Verifying account numbers. settlement figures. Payment deadlines. Unambiguous debt risk release clauses.
Stage 6: Direct Remittance, CBS Zeroing, and No Dues Certificate
settlement funds are remitted straight into your Kotak loan account. We oversee internal CBS ledger zeroing and enforce delivery of your formal No Dues letter within 30-45 days.
Kotak Legal Notices Defense & Borrower Rights in India
Defaulting on no-pledge private loans is strictly a civil claims. Not a crime. CredSettle ensures strict legal defense against automated notices and claims firm overreach.
Section 25 PSSA (NACH / E-Mandate Bounce)
Automated debits returned for insufficient funds trigger Section 25 notices. We issue formal legal replies rebutting penal intent. Documenting genuine hardship. And directing matters toward amicable OTS deals.
Section 138 Negotiable Instruments Act
Deposited pledge cheques trigger legal 15-day demand notices. Our replies challenge pledge instrument misuse under Section 139 presumptions. Proposing an OTS OTS deal before magistrate filings.
Sole Arbitration under Section 21 & Section 12(5)
Under Supreme Court rulings in. Perkins Eastman and TRF Ltd.Unilateral sole judge appointments by lenders are void. We file Section 12(5) objections to halt hearing and compel bilateral settlement.
DRT Section 19 & RBI Fair Practices Code
DRT steps require claims exceeding ₹20 Lakhs. Concurrently. RBI Fair Practices Code strictly prohibits claims agent contact before 8 AM or after 7 PM. Abuse of kin. banned visits.
3-Tier Grievance Escalation Matrix for Kotak Loans
clients facing unlawful abuse or unresponsiveness must navigate RBI&apos. s established three-tier reports hierarchy to secure prompt bank relief:
Level 1: Grievance Redressal agents (GRO): reports are submitted to Kotak&apos. S local GRO. Who must provide an formal relief within 7 to 10 trade days.
Level 2: main loan Nodal agents (PNO): If unresolved. The issue escalates to Kotak&apos. s main loan Nodal agents for executive review and settlement help within 14 to 21 days.
Level 3: Reserve Bank of India agents: If 30 days elapse without relief. A legal petition is filed on the RBI CMS portal (cms.rbi.org.in). Invoking powers under the Integrated agents Scheme. 2021.
Kotak Loan Default Milestones & Resolution Timeline
Navigating loan relief requires understanding the sequential phases through which Kotak Mahindra Bank processes defaulted retail debt. The table below delineates the critical daily work and legal milestones from initial missed installment to final CIBIL desk closure.
| default Phase. | Banking Milestone. | Recovery & Legal Action. | Optimal Strategy. |
|---|---|---|---|
| Days 1. 30 (SMA-0). | First missed installment. | Automated SMS. Email reminders & soft telecalling. | Audit cashflow. preserve cash for lump-sum OTS. |
| Days 31. 90 (SMA-1/2). | Consecutive default period. | External claims firms assigned. intense telecalling. | Compile hardship dossier. prepare anti-abuse shield. |
| Day 90+ (NPA Classification). | Gross NPA declaration. | strict 100% Tier-1 bank reserves. legal desk transfer. | Initiate formal settlement petition to Stressed Asset Group. |
| Days 91. 150 (Legal Window). | Pre-lawsuits reports. | Section 25 NACH notices. Sole hearing intimations. | Issue legal replies. challenge unilateral hearing. |
| Days 151. 180+ (OTS Closure). | OTS deal or ARC assignment. | Final OTS sanction issued or portfolio sale to Phoenix ARC. | Verify sanction letter. pay payment & secure NDC. |
Case Scenarios: Resolving Kotak Mahindra Loan Defaults
1. Kotak 811 Digital Credit & Micro-Personal Loans
Defaulted 811 online facilities face harsh automated claims algorithms. CredSettle unbundles growing app surcharges. Halts claims scripts via formal representations. And settles balances via lump-sum OTS.
2. Salaried Executive Layoffs & Income Stoppage
workers facing firm layoffs receive structured advocacy. By submitting severance exhaustion records and income cessation proof. CredSettle shows genuine distress to secure up to 55% haircuts.
3. Small Business Proprietorship Cashflow Collapse
founders using no-pledge loans for working cash receive trade defense. Audited GST filings establish liquidity failure. This lets multi-tranche OTS deals that protect own assets.
4. Debt Assignment to Phoenix ARC Pvt Ltd
When Kotak sells non-performing accounts to Phoenix ARC. CredSettle audits the underlying Deed of Assignment under SARFAESI Section 5. Settling deep concessions based on Phoenix ARC&apos. s discounted portfolio acquisition cost.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions on Kotak Mahindra Bank Loan Settlement
Authoritative legal and procedural answers to the most common queries regarding Kotak private loans. 811 online credit. Claims notices. CIBIL desk remediation.
Statutory Citations & RBI Regulations for Kotak Borrowers
Every settlement legal help. Notice reply. hearing objection prepared by CredSettle is grounded in authoritative legal acts and court rulings governing the Indian money system:
- Reserve Bank of India Master Circular on Prudential Norms on Advances and Asset Classification (DOR.No.STR.REC.55/21.04.048/2021-22).
- Reserve Bank of India Master Direction - Non-Banking money firm and Bank Fair Practices Code on claims agents.
- Securitisation and Reconstruction of money Assets and Enforcement of pledge rates Act. 2002 (SARFAESI Act Section 31(g)).
- hearing and talks Act. 1996 (Section 12(5). Section 21. Supreme Court rulings in Perkins Eastman and TRF Ltd.).
- Payment and settlement Systems Act. 2007 (Section 25 quasi-penal defense and growing provisions).
- Credit Information firms (Regulation) Act. 2005 (CICRA Section 21 claims rectification protocols).
formal legal Repositories.
Related Debt relief Topics.