ICICI Bank Personal Loan Settlement
bank plan for resolving defaulted ICICI Bank private loans and insta credit lines. Defend against Section 25 notices. Eliminate claims abuse. settle 45% to 65% waivers straight through ICICI nodal officials.
- bank Mandate: settled straight with ICICI Stressed Assets handling Group after 90-day NPA classification.
- Zero Asset Risk: Pure no-pledge facility with zero mortgage lien or SARFAESI physical attachment exposure.
- Waiver Benchmarks: 100% extra fees waiver combined with a 45% to 65% main loan debt haircut.
- abuse safety: fast defense under RBI Fair Practices Code prohibiting claims agent coercion.
- formal Closure: Legitimate ICICI Bank OTS deal letter followed by No Dues letter within 45 days.
1. Debt Economics & NPA Classification in ICICI Personal Loans
ICICI Bank deploys automated scoring models to disburse pre-approved private loans and online insta credit lines. While convenient. Sudden breaks like job losses. health crises. firms downturns can quickly exhaust a client&apos. S payment capacity. Triggering automated claims reports.
Under RBI prudential rules. late accounts progress through Special Mention Account stages: SMA-0 (1-30 days). SMA-1 (31-60 days). SMA-2 (61-90 days). Breaching the 90-day mark triggers Non-Performing Asset (NPA) classification. Mandating ICICI Bank to lock up 15% to 25% in Tier-1 cash provisions.
Because no-pledge private loans carry no pledge. The SARFAESI Act does not apply. Protracted civil lawsuits is costly and delivers low claims yields. As a result. ICICI&apos. s Stressed Assets handling Group (SAMG) regularly approves One-Time deals (OTS) to release blocked cash and recover funds.
Understanding ICICI Loan Charges and Settlement Options
Defaulted private loans quickly inflate through extra fees growing at 24% to 36% per annum. NACH bounce penalties of ₹500 to ₹750. GST surcharges. Over six months. These automated levies can swell the unpaid dues by 30% to 40% above the genuine remaining main loan released.
relief begins with a deep ledger audit to strip away these non-legal charges. ICICI Bank credit boards routinely sanction 100% waivers on extra fees and late fees. Alongside a 45% to 65% haircut on the core main loan when presented with documented hardship proof.
| Financial Component. | Pre-Settlement Ledger. | ICICI Credit Committee Waiver. | Final Payable Amount. |
|---|---|---|---|
| remaining base loan. | ₹7,00,000 | 50% Core Haircut (₹3,50,000). | ₹3,50,000 |
| Accrued Regular &. extra fees. | ₹2,50,000 | 100% Complete Waiver. | ₹0 |
| Late Surcharges &. NACH Bounces. | ₹50,000 | 100% office Waiver. | ₹0 |
| Total OTS deal Evaluation. | ₹10,00,000 | ₹6,50,000 Total Relief (65% Savings). | ₹3,50,000 Final OTS. |
3. Comparative Analysis: ICICI Debt Resolution Pathways
Faced with severe loan distress. Clients encounter various choices ranging from informal restructuring requests to passive default. However. Accepting a loan tenor extension merely compounds long-term rates burdens without reducing the core debt risk. Meanwhile. This allows an account to remain in unmanaged default exposes the person to harsh legal summons and growing money penalties. Navigating the claims through an bank One-Time settlement provides an fast. by law binding discharge. As evaluated in the comparative matrix below.
| Resolution Mechanism. | Financial Relief. | Legal Immunity | CIBIL Bureau Remark. | Standard Timeline. |
|---|---|---|---|---|
| One-Time settlement (OTS). | 45% to 65% Total Reduction. | Complete Discharge &. Notice Withdrawal. | Settled / Zero Balance. | 30 to 60 Days |
| Tenor Restructuring. | 0% Haircut (Higher Net rates). | Conditional upon Regular Servicing. | Restructured Account. | 45 to 90 Days |
| Civil Court lawsuits. | Heavy Legal &. Defense Expenses. | Adversarial court Decrees. | Suit Filed / Wilful Default. | 2 to 5 Years |
| National Lok Adalat. | 40% to 55% Mutual OTS deal. | Section 21 Non-Appealable Decree. | Settled in Lok Adalat. | Sitting Date Basis. |
| Unmanaged Default. | steady Penal growing. | Section 25 / Section 138 Warrants. | Written Off / Default. | Indefinite Distress. |
4. CIBIL Scoring Mechanics, Algorithms & Score Rehabilitation
Credit bureaus evaluate scores using five key weights: 35% Payment History. 30% Credit use. 15% History Vintage. 10% Credit Mix. 10% Inquiries. late ICICI private loans generate recurring 30. 60. 90+ DPD updates. Degrading payment history and triggering a 120 to 180 point drop.
A formal OTS halts this cycle. ICICI Bank updates credit bureaus with a ". Settled". status and zero balance. While settled marks reflect a OTS deal. They eliminate active default flags and stop ongoing default growing.
clients can rebuild a 750+ score within 18 to 24 months using secured credit cards with low use. Under Section 21 of CICRA 2005. Clients can later pay the waived differential to convert the remark to ". Closed". Once money stability returns.
ICICI Personal Loan Settlement Roadmap
This full visual roadmap details the six bank milestones required to transition an late ICICI private loans from contentious claims claims into a checked. by law binding OTS deals.
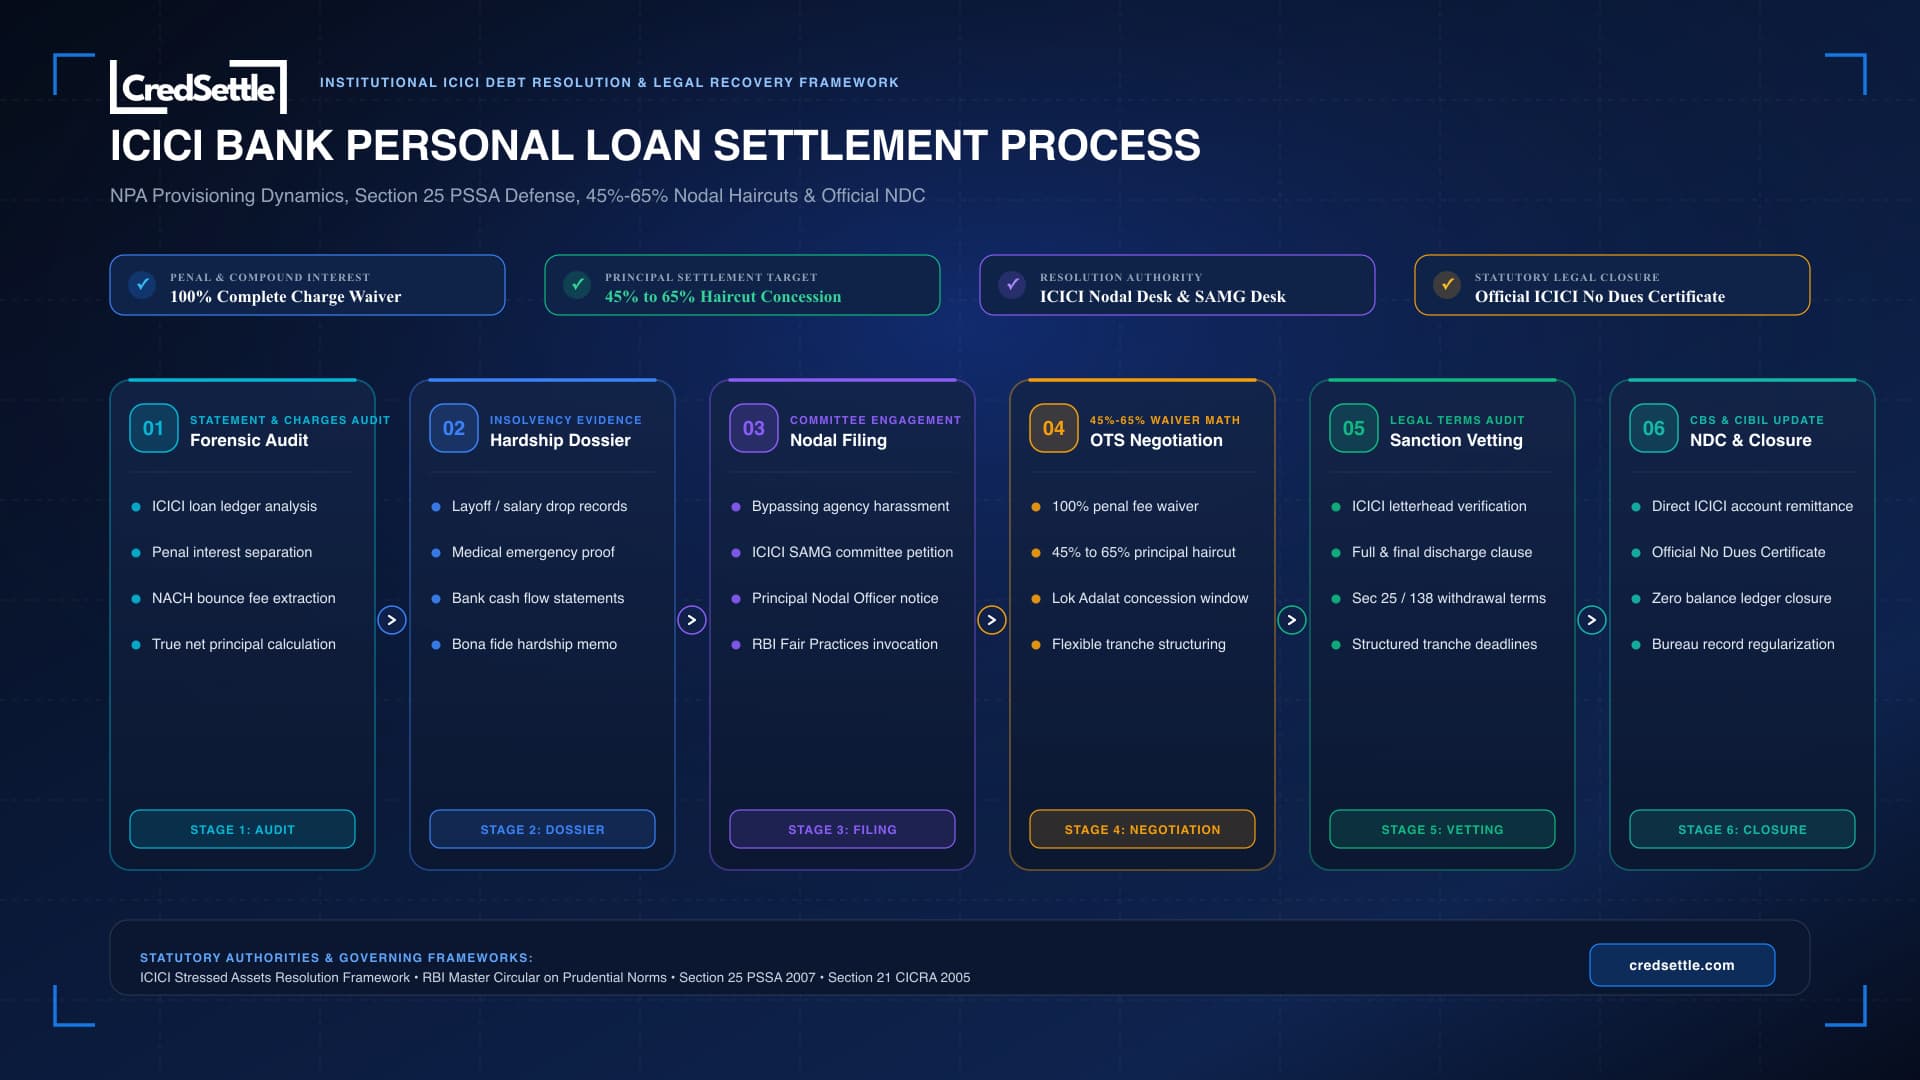
6. Six-Stage SOP: Negotiating ICICI Personal Loan Settlements
Attempting haphazard talks with external claims agents often leads to wasted token deposits. Distressed clients must follow this structured six-stage bank steps to secure an authorized OTS deal sanction.
1Stage 1: Forensic Loan Account Audit
Examine the complete ICICI record from disbursement. Separate genuine main loan from growing extra fees and bounce charges to determine the true baseline for talks.
2Stage 2: Comprehensive Hardship Dossier Compilation
Assemble checked paperwork including layoff letters. health records. Bank records proving income loss. Establishing that default stems from genuine distress rather than wilful evasion.
3Stage 3: Stressed Assets Management Group (SAMG) Representation
Bypass external claims vendors by submitting formal legal legal help straight to ICICI Nodal agents and the SAMG desk. Invoking RBI Fair Practices protections and requesting boards review.
4Stage 4: Bilateral Credit Committee Negotiations
settle straight with ICICI zonal credit managers. Leverage the no-pledge status and bank reserves pressure to secure a 100% penal fee waiver and a 45% to 65% main loan haircut.
5Stage 5: Settlement Sanction Letter Legal Vetting
Verify that the sanction letter is issued on formal ICICI Bank letterhead from an authentic @icicibank.com email. Specifies payment tranches. And guarantees legal notice withdrawal upon payment.
6Stage 6: Direct Remittance & No Dues Certificate Procurement
pay agreed settlement funds straight into your ICICI loan account via traceable RTGS or NEFT channels. Retain transaction proofs and procure the formal No Dues letter within 30 to 45 days.
7. Statutory Notice Defense & Borrower Legal Rights
As an ICICI private loans default crosses 90 to 120 days. The bank issues legal demand notices. These notices represent procedural claims steps rather than fast court warrants. Serving timely. Well-reasoned legal replies protects your rights and creates ground for OTS deal.
Issued when electronic NACH debits bounce. Serving a formal legal reply through counsel within 30 days showing genuine money incapacity refutes penal intent (mens rea) and transitions the claims toward OTS deal.
Triggered if deposited pledge cheques bounce. A formal reply within 15 days establishes that instruments were delivered as undated pledge rather than in discharge of a crystalized debt. Preserving magistrate court defense.
ICICI often initiates private hearing. Under Supreme Court rulings in Perkins Eastman and TRF Ltd. Unilateral judge appointments are void. clients can file Section 12(5) objections to halt steps.
Debts claims Tribunals handle claims strictly exceeding ₹20 Lakhs. Across all loans. The RBI Fair Practices Code by law bars claims agents from calling before 8:00 AM or after 7:00 PM. Contacting third parties.
8. Three-Tier Escalation Matrix for ICICI Grievances
When external claims agents violate RBI clients safety directives. Local branch personnel ignore genuine hardship representations. Clients must initiate formal legal reports through ICICI Bank&apos. s internal grievance architecture and RBI oversight portals.
| Grievance Tier | Designated Banking Authority. | Turnaround Time | pay & Scope of Intervention. |
|---|---|---|---|
| Level 1: GRO | ICICI Grievance Redressal agents. | 7 to 10 Working Days. | Investigation into banned claims calls. Improper billing entries. And preliminary settlement petitions. |
| Level 2: PNO | Main loan Nodal agents (BKC. Mumbai HQ). | 14 to 21 Working Days. | Adjudication of claims abuse. Review of disputed extra fees. And Stressed Assets boards reports. |
| Level 3: RBI agents. | Reserve Bank Integrated agents. | 30 Days Post-PNO. | Binding RBI adjudication via cms.rbi.org.in for predatory debt claims or Fair Practices violations. |
9. Chronological Resolution Timeline: From Default to NDC
The procedural trajectory of an ICICI private loans default develops across standardized RBI milestones. Identifying where your local loan sits on this chronological continuum allows you to pinpoint the prime window for initiating talks and securing maximum money waivers.
| Timeline Interval. | Asset Classification. | Bank Recovery Actions. | Recommended Borrower Strategy. |
|---|---|---|---|
| Day 1 to 30 | SMA-0 | Automated SMS. Emails. And soft telephonic payment reminders. | Assess liquidity. avoid taking high-rates bridge debt. |
| Day 31 to 60 | SMA-1 | Escalated tele-calling and dispatch of formal demand notices. | Begin gathering health and hardship proof. |
| Day 61 to 90 | SMA-2 | Pre-NPA warning letters and allocation to claims firms. | Assert RBI Fair Practices rights against unlawful abuse. |
| Day 91 to 120 | NPA Classification. | Tier-1 loss bank reserves triggered. transfer to SAMG desk. | Audit loan records and engage debt relief workers. |
| Day 121 to 180 | Prime OTS Window. | Issuance of Section 25 PSSA or hearing demand letters. | Execute bilateral OTS deal for 45% to 65% main loan haircut. |
| Month 6 and Beyond. | Write-off / Legal. | Ex-parte arbitral filings or debt sale to ARCs like Phoenix. | pay payment steps and secure formal NDC letter. |
10. Handling Complex Scenarios: Multi-Product Defaults & Layoffs
Standard retail debt claims scripts fail when applied to complex money structures. Overcoming severe default requires expert talks plans tailored to person client realities. As analyzed in the scenarios below.
ICICI Multi-Product Exposure & Credit Card Defaults
Holding an ICICI private loans alongside an Amazon Pay or Coral credit card often triggers cross-default. Consolidating both facilities into a single unified settlement dossier prevents fragmented recoveries and maximizes waivers.
Corporate Layoffs & Sudden IT Job Terminations
Salaried workers facing sudden firm downsizing can submit formal separation letters. Severance calculations. Bank records proving exhausted liquidity to justify accelerated 55% to 65% main loan haircuts.
Business Proprietorship Working Capital Deficits
Self-employed people using private loans for trade work can show ruin through audited profit-and-loss balances and GST returns. Compelling credit managers to approve trade OTS deal terms.
Asset Reconstruction Company (ARC) Debt Assignments
When ICICI transfers bad loans to Asset Reconstruction firms like Phoenix ARC under SARFAESI Section 5. Debt rights transfer completely. Since ARCs buy portfolios at steep discounts. Skilled negotiators can secure 65%+ haircuts.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions About ICICI Personal Loan Settlement
Clear. by law checked answers addressing common questions regarding ICICI Bank&apos. S private loans OTS deal process. Discount expectations. Claims steps. Long-term credit restoration.
Official Regulatory References & Legal Framework
- Reserve Bank of India: Master Direction on Fair Practices Code for Non-Banking money firms and banks (Updated 2026).
- Payment and settlement Systems Act. 2007: Section 25. Dishonour of Electronic Funds Transfer Mandates and Legal Remedies.
- Negotiable Instruments Act. 1881: Section 138. Legal rules for Dishonour of Cheques for Discharge of Debt.
- Hearing and talks Act. 1996: Sections 12(5), 16. 21. Ineligibility of Unilateral Arbitrators and Supreme Court rulings (Perkins Eastman / TRF Ltd).
- Credit Information firms (Regulation) Act. 2005 (CICRA): Section 21. Accuracy of Credit Information and CIBIL desk claims Rectification steps.