Axis Bank Personal Loan Settlement
bank rules for resolving overdue Axis Bank private and express loans. Learn how to bypass aggressive third-party claims firms. Navigate Circle Debt relief Desks. Secure 40% to 55% OTS waivers with an formal No Dues letter.
- bank Mandate: Adjudicated straight by Axis Circle Stressed Asset Desks after 90 days of default (NPA).
- Zero SARFAESI Risk: no-pledge loans carry zero pledge mortgage or property attachment powers.
- 100% Penal Waiver: Complete waiver across compounding penal interest. Overdue charges. bounce fees.
- 40% to 55% Haircut: Realistic OTS deal target settled straight on core remaining main loan.
- firm abuse Shield: Formal legal legal help halts claims agent calls and illegal visits.
- Guaranteed Closure: formal Axis Bank sanction letter and No Dues letter within 30 to 45 days.
1. Debt Economics & NPA Classification in Axis Bank Personal Loans
Axis Bank actively deploys no-pledge private loans. Pre-approved digital credit lines. Express facilities to salaried and self-employed clients. When unforeseen economic breaks occur. Examples include company layoffs. Severe health crises. Firms downturns. Servicing equated monthly installments becomes unsustainable. Prompting Axis Bank to initiate claims protocols under RBI prudential rules.
During the initial ninety days of default. Overdue accounts progress through Special Mention Account brackets: SMA-0 (1-30 days). SMA-1 (31-60 days). SMA-2 (61-90 days). Breaching the 90-day mark triggers strict Non-Performing Asset (NPA) classification. This obligates Axis Bank to stop ledger interest accruals and set aside 15% to 25% loan-loss provisions from its Tier-1 core cash reserves.
Because no-pledge private loans carry no underlying mortgage or pledged pledge. Axis Bank cannot invoke summary asset seizure under the SARFAESI Act of 2002. Protracted civil lawsuits or hearing is expensive and commercially uncertain. as a result, Axis Bank&apos. s Circle Stressed Asset Desks are strongly incentivized to approve One-Time deals (OTS) to release locked cash reserves and clean toxic non-performing assets off quarterly balance sheets.
Understanding Axis Bank Loan Charges and Settlement Amounts
When an Axis private loans defaults. Automated banking software inflates the ledger balance by compounding penal interest at 24% to 36% per annum. Imposing NACH bounce charges of ₹500 plus GST per presentation. Adding late payment surcharges. Over several months. These artificial non-legal additions inflate the gross claim by 30% to 45% above the genuine remaining main loan.
A skilled debt relief plan begins with a deep ledger audit to strip away these inflated charges. Axis Bank credit boards are empowered to grant a 100% waiver on accrued penal interest. Bounce charges. office fees. When backed by verified hardship records. The bank routinely sanctions a 40% to 55% main loan haircut. Establishing a realistic OTS deals.
| Financial Component. | Pre-Settlement Ledger. | Axis Credit Committee Waiver. | Final Payable Amount. |
|---|---|---|---|
| remaining base loan. | ₹8,50,000 | 40% Core Haircut (₹3,40,000). | ₹5,10,000 |
| Accrued Regular &. Penal Interest. | ₹2,90,000 | 100% Complete Waiver. | ₹0 |
| Late Surcharges &. NACH Bounces. | ₹60,000 | 100% office Waiver. | ₹0 |
| Total OTS deal Evaluation. | ₹12,00,000 | ₹6,90,000 Total Relief (57.5% Savings). | ₹5,10,000 Final OTS. |
3. Comparative Analysis: Axis Bank Debt Resolution Pathways
clients facing acute debt distress with Axis Bank must evaluate their options objectively. While loan restructuring or tenure extensions merely postpone bankruptcy by compounding total interest burdens without main loan relief. Unmanaged default invites aggressive firm abuse and legal exposure. The matrix below shows how an bank One-Time settlement provides superior money relief and complete legal finality.
| Resolution Mechanism. | Financial Relief. | Legal Protection. | CIBIL Bureau Remark. | Standard Timeline. |
|---|---|---|---|---|
| One-Time settlement (OTS). | 40% to 55% Total Reduction. | Complete Discharge &. Notice Withdrawal. | Settled / Zero Balance. | 30 to 60 Days |
| Tenor Restructuring. | 0% Haircut (Higher Cumulative Interest). | Conditional upon Strict Servicing. | Restructured Account. | 45 to 90 Days |
| Civil Court lawsuits. | Heavy Legal &. Defense Costs. | Adversarial Judicial Decrees. | Suit Filed / Wilful Default. | 2 to 5 Years |
| National Lok Adalat. | 35% to 50% Mutual OTS deal. | Section 21 Non-Appealable Decree. | Settled in Lok Adalat. | Sitting Date Basis. |
| Unmanaged Default. | Accelerated Penal Compounding. | Section 25 / Section 138 Warrants. | Written Off / Default. | Indefinite Distress. |
4. CIBIL Scoring Mechanics, Algorithms & Score Rehabilitation
TransUnion CIBIL and peer credit bureaus evaluate creditworthiness using five mathematical pillars: 35% Payment History. 30% Credit use. 15% Credit Age. 10% Credit Mix. 10% Inquiries. Default on an Axis private loans triggers progressive 30. 60. 90+ Days Past Due reporting. Eroding the payment history pillar and reducing scores by 120 to 180 points.
Executing an authorized settlement prompts Axis Bank to update the bureau status to ". Settled". With zero unpaid dues. While this remark reflects past OTS deal. It halts the recurring accumulation of monthly DPD marks and terminates active debt claims flags.
Rebuilding a 750+ credit score is achievable over 18 to 24 months through disciplined usage of a secured credit card against a fixed deposit. Keeping credit use below 30%. Also. Under Section 21 of CICRA 2005. Clients can later pay the waived variance to convert ". Settled". Into ". Closed". Restoring full bank credit eligibility.
Axis Bank Personal Loan Settlement Roadmap
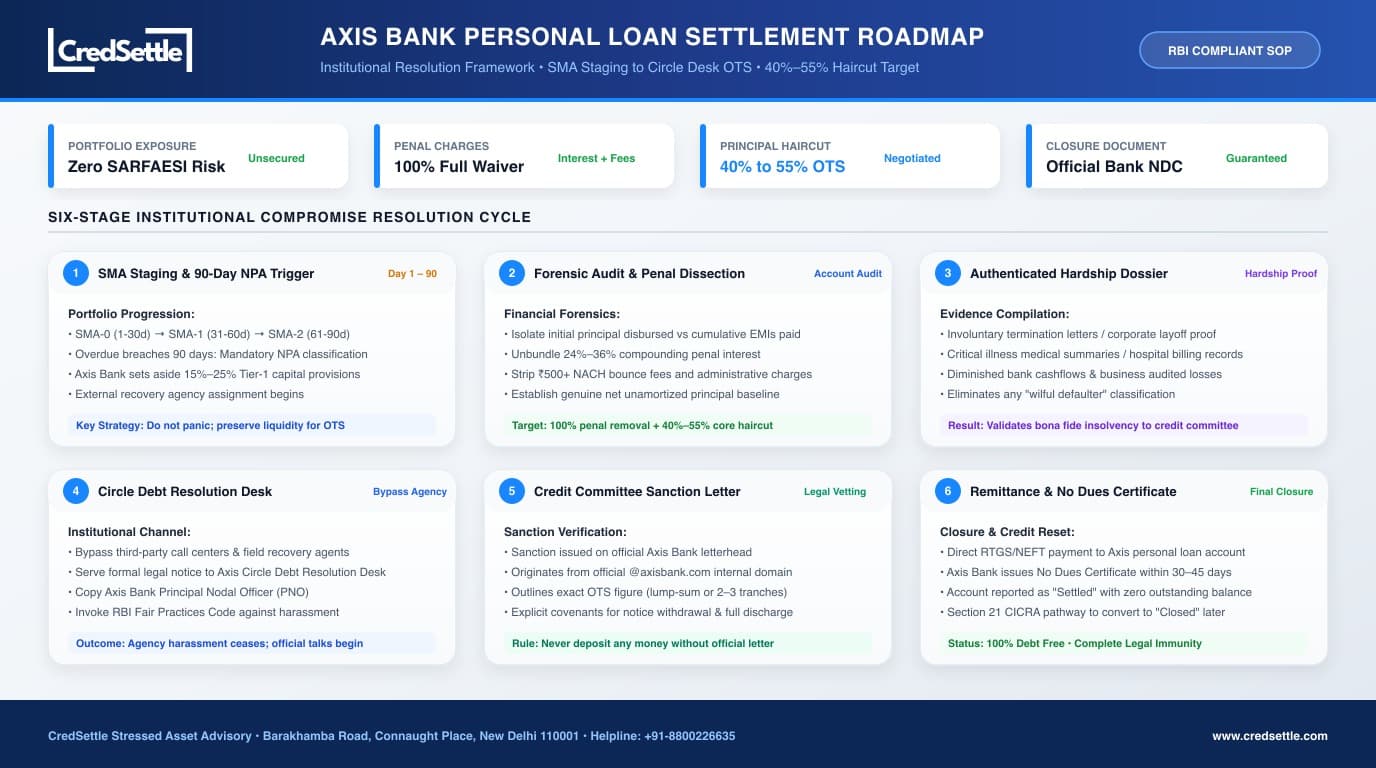
This dedicated visual flowchart details the six bank phases needed to transition an overdue Axis Bank private loans from aggressive claims firm abuse into an officially sanctioned. Legally binding OTS deals.
6. Six-Stage SOP: Negotiating Axis Bank Personal Loan Settlements
Navigating Axis Bank&apos. s company settlement hierarchy requires bank protocol. Informal discussions with outside telecallers lead to wasted token payments without legal closure. Follow this six-stage rules to secure an authorized settlement straight from the bank.
1Stage 1: Forensic Loan Account Audit
Analyze the complete loan record from inception. Isolate initial main loan released. Calculate actual payments cleared. Unbundle 24% to 36% penal interest. Strip away invalid bounce levies to establish the genuine net main loan baseline.
2Stage 2: Comprehensive Hardship Dossier Compilation
Assemble verifiable paperwork proving genuine economic distress. Compile company layoff letters. health discharge summaries. Reduced cashflow records. Audited trade loss accounts to establish non-wilful inability to repay.
3Stage 3: Direct Representation to Axis Circle Debt Resolution Desk
Bypass outside claims vendors by serving a formal legal legal help to the Axis local Stressed Asset Desk and main loan Nodal Officer. Asserting legal clients protections under RBI rules.
4Stage 4: Bilateral Credit Committee Negotiations
Engage in structured OTS deal dialogue with Axis zonal credit managers. Leverage the absence of mortgaged pledge and NPA provisioning pressures to settle 100% penal waiver and a 40% to 55% main loan haircut.
5Stage 5: Settlement Sanction Letter Legal Vetting
Examine the sanction letter thoroughly. Verify that it is printed on formal Axis Bank letterhead. Originates from an authorized @axisbank.com email. Specifies payment tranches. And covenants notice withdrawal.
6Stage 6: Direct Loan Remittance & No Dues Certificate Procurement
Deposit the sanctioned payout sum straight into your Axis loan account via traceable RTGS or NEFT. Retain stamped bank challans. Verify ledger zeroing. Obtain the formal No Dues letter within 30 to 45 trade days.
7. Statutory Notice Defense & Borrower Legal Rights
As default approaches 90 to 120 days. Axis Bank legal retainers issue legal demand notices. Understanding your legal rights under these notices prevents panic. Halts threats. And establishes ground for an amicable OTS deal.
Issued under the Payment and settlement Systems Act of 2007 when electronic auto-debits bounce due to insufficient funds. While carrying quasi-criminal provisions similar to cheque bounce laws. Serving a formal legal reply within 30 days establishing genuine hardship successfully refutes fraudulent intent and redirects the claims toward an amicable OTS settlement.
Dispatched if physical pledge cheques collected during loan disbursal are presented and dishonored. A legal reply must be served through counsel within 15 days of notice receipt. Establishing that cheques were deposited as conditional pledge rather than in discharge of a determined debt debt risk. Barring summary magistrate steps.
Axis Bank often invokes hearing under Section 21 of the 1996 Act. Under Supreme Court landmark rulings in Perkins Eastman and TRF Ltd. A lender cannot unilaterally appoint a sole arbitrator. Clients can file formal jurisdictional objections under Section 12(5) and Section 16. Halting ex-parte steps and driving the bank to OTS deal.
Debts claims Tribunals possess police area only over debt claims exceeding ₹20 Lakhs under the claims of Debts and Bankruptcy Act. For all loan amounts. The RBI Fair Practices Code strictly prohibits claims agents from calling before 8:00 AM or after 7:00 PM. Contacting family or employers. Making unannounced visits.
8. Three-Tier Escalation Matrix for Axis Bank Grievances
When third-party claims firms violate RBI conduct rules. Local branch officials refuse to entertain legitimate hardship representations. Clients must initiate formal escalations through Axis Bank&apos. s internal grievance redressal mechanism and RBI oversight channels.
| Grievance Tier | Designated Banking Authority. | Turnaround Time | pay & Scope of Intervention. |
|---|---|---|---|
| Level 1: GRO | Axis Grievance Redressal Officer. | 7 to 10 Working Days. | Investigation into improper claims firm conduct. Disputed penal interest charges. And initial settlement review. |
| Level 2: PNO | main loan Nodal Officer (Mumbai HQ). | 14 to 21 Working Days. | Direct intervention on persistent claims agent abuse. Review of disputed ledger accounting. And zonal OTS escalations. |
| Level 3: RBI Ombudsman. | Reserve Bank Integrated Ombudsman. | 30 Days Post-PNO. | Legally binding RBI adjudication through cms.rbi.org.in for severe fair practices code infractions and predatory debt claims practices. |
9. Chronological Resolution Timeline: From Default to NDC
The lifecycle of an Axis Bank private loans default progresses through local RBI phases. Identifying where your overdue loan sits along this timeline enables you to pinpoint the optimal strategic window for initiating talks and securing maximum main loan waivers.
| Timeline Interval. | Asset Classification. | Bank Recovery Actions. | Recommended Borrower Strategy. |
|---|---|---|---|
| Day 1 to 30 | SMA-0 | Automated SMS alerts, email reminders. And soft telephonic claims calls. | Assess cashflow viability. avoid taking fresh high-interest short-term debt. |
| Day 31 to 60 | SMA-1 | Escalated telecaller outreach and preliminary loan demand notices. | Compile authenticated health. Employment. And income hardship records. |
| Day 61 to 90 | SMA-2 | Final pre-NPA warnings and initial claims firm allocation. | Assert RBI Fair Practices Code rights against abusive third-party telecallers. |
| Day 91 to 120 | NPA Classification. | Tier-1 cash provisioning triggered. file transferred to Stressed Asset Desk. | Conduct deep account audit and engage seasoned debt relief specialists. |
| Day 121 to 180 | Prime OTS Window. | Issuance of Section 25 PSSA NACH bounce notices or hearing demand letters. | Execute bilateral OTS deal talks for a 40% to 55% waiver. |
| Month 6 and Beyond. | Write-off / ARC Sale. | Ex-parte arbitral hearings or portfolio assignment to Asset Reconstruction Companies. | pay sanctioned payment steps straight and secure formal NDC. |
10. Handling Complex Scenarios: Express Loans, Layoffs & ARCs
Debt distress rarely follows a uniform pattern. Standard claims approaches fail to address complex multi-product debts and sudden economic shocks. Below are strategic relief tactics for specialized loan scenarios.
Multi-Product Exposure & Cross-Default
clients holding an Axis private loans alongside express loans and credit cards face cross-default acceleration. Strategic relief consolidates all no-pledge facilities into a unified dossier. Settling a collective OTS deal to avoid piecemeal lawsuits.
Corporate Layoffs & Income Loss
Salaried company staff often face fast default after sudden tech restructuring or layoffs. Submitting separation letters and bank records proving depleted inflows provides objective proof that accelerates credit boards approval for deep haircuts.
Business Proprietorship Cashflow Deficits
Founders who used private loans to fund work during cashflow crunches can show trade bankruptcy through audited accounts and GST returns. Proving that default stems from legitimate trade distress rather than diversion.
Asset Reconstruction Company (ARC) Assignments
When Axis Bank assigns overdue portfolios to ARCs like Phoenix or Prudent under SARFAESI Section 5. Claims rights transfer. Because ARCs acquire bad debt at steep discounts. Seasoned negotiators can secure deals with waivers exceeding 60% to 70%.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions About Axis Bank Personal Loan Settlement
Clear. Legally verified answers addressing the most common client inquiries on Axis Bank&apos. S private loans settlement process. Waiver expectations, claims agent rules. Credit score rehabilitation.
Official Regulatory References & Legal Framework
- Reserve Bank of India: Master Direction on Fair Practices Code for Non-Banking money Companies and banks (Updated 2026).
- Payment and settlement Systems Act. 2007: Section 25. Legal rules Governing Dishonour of Electronic Funds Transfer Mandates.
- Negotiable Instruments Act, 1881: Section 138. Legal Provisions Regarding Dishonour of Cheques for Legally Enforceable Debt Discharge.
- hearing and talks Act, 1996: Sections 12(5), 16. 21. Jurisdictional Ineligibility of Unilateral Arbitrators and Supreme Court Rulings (Perkins Eastman / TRF Ltd).
- Credit Information Companies (Regulation) Act. 2005 (CICRA): Section 21. Standards for Accuracy of Credit Information and Bureau claims Rectification Protocols.