IDFC FIRST Bank Loan Settlement Process
bank legal plan for resolving late IDFC FIRST Bank retail private loans and online clients facilities. Learn how to counter automated online legal notices. Neutralize sole hearing steps. Eliminate growing penalty charges. settle up to 60% debt write-offs with an authentic No Dues letter.
-
bank police area: Settled through IDFC Stressed Assets desk past 90 days default.
-
no-pledge Immunity: No asset mortgage rights under SARFAESI Act Section 31(g).
-
100% Surcharge Waiver: Full elimination of growing extra fees. Bounce fees &. GST.
-
main loan Haircut Target: 40% to 60% write-offs settled on core unamortized balance.
-
online Notice Shield: Automated WhatsApp summons &. notices defused via formal legal reply.
-
hearing safety: Unilateral judge appointments countered under Perkins Eastman.
-
Section 25 PSSA Defense: E-mandate dishonors channeled into binding OTS deals.
-
legal Account Closure: Direct CBS remittance followed by authentic NDC within 30-45 days.
IDFC FIRST Bank Debt Economics and NPA Classification Dynamics
IDFC FIRST Bank has expanded aggressively into retail no-pledge credit. Originating thousands of clients durable loans. online app credit lines. High-ticket private loans across India. When unexpected life situation. firm downsizing. Severe trade downturns disrupt a client&apos. S monthly cashflow. The loan transitions sequentially through RBI default brackets. During the initial thirty days of default. The account is designated as Special Mention Account Zero (SMA-0). Progressing to SMA-1 between thirty-one and sixty days. Reaching SMA-2 between sixty-one and ninety days. Throughout these initial ninety days. The bank deploys high-frequency automated reminders. online payment links. Intensive telecalling through third-party claims firms.
Once an no-pledge private loans crosses the critical ninety-day steady default threshold. Reserve Bank of India prudential regulations mandate that IDFC FIRST Bank classify the asset as a Gross Non-Performing Asset (NPA). This RBI classification triggers major money pressure for the institution. Under RBI bank reserves rules. The bank must set aside large Tier-1 cash reserves against the late balance. Straight eroding its reported quarterly profitability and cash adequacy ratios. Crucially. This is because retail private loans and online facilities are entirely no-pledge. Section 31(g) of the SARFAESI Act explicitly bars the bank from initiating summary asset auctions. Home seizures. home attachments without protracted civil lawsuits. Recognizing that prolonged legal claims in civil courts often takes five to seven years with excessive legal overhead. IDFC FIRST Bank&apos. s Retail Stressed Asset handling division operates under clear trade mandates to settle pragmatic One-Time deals (OTS). This lets the bank to recover large cash while purging bad debt from its balance sheet.
Understanding IDFC FIRST Bank Loan Charges & Settlement Math
When an IDFC FIRST Bank loan enters extended default. The gross unpaid dues cited by claims telecallers rapidly becomes distorted. Lenders automatically superimpose annualized growing extra fees rates ranging from twenty-four to thirty-six percent. Recurring NACH dishonor charges of ₹450 to ₹590 per cycle. Legal administration fees. An eighteen percent Goods and Services Tax on every levied surcharge. Over four to six months of non-payment. These growing add-ons can easily represent twenty-five to thirty-five percent of the entire ledger claim. Creating an artificial barrier to debt relief.
bank debt talks begins with an uncompromising audits of the loan ledger. CredSettle isolates the core remaining base loan by extracting all non-legal penalty charges. Bounce fees. Accrued surcharge rates. Under IDFC FIRST Bank&apos. S established OTS deals rules. Credit boards routinely grant a strict 100% waiver on all penal and office surcharges once genuine debt stress is prove. Also. Depending on the vintage of the NPA and the client&apos. S checked ruin. The bank sanctions an remaining main loan haircut between 40% and 60%. Establishing a realistic single-tranche or structured multi-part OTS deal figure.
Gross Bank Claim.
₹8,50,000
Includes extra fees &. bounce fees.
Penal Surcharges Stripped.
₹2,10,000
100% full bank waiver.
Core remaining main loan.
₹6,40,000
checked baseline exposure.
Sanctioned OTS Figure.
₹3,20,000
50% main loan haircut (62% total relief).
IDFC Settlement vs Restructuring & Alternate Options
When clients skill severe debt distress on IDFC FIRST Bank private loans. They are often presented with confusing alternatives ranging from tenure extensions to court appearances. Loan restructuring appears attractive initially but actually increases aggregate rates burdens without granting any main loan relief. Conversely. Unresolved defaults trigger harsh online summons. Potential penal reports under payment statutes. Eventual debt assignment to private asset claims entities. The full comparative matrix below objectively contrasts the legal. Money. And credit implications across every available relief pathway.
| Resolution Route. | Waiver Potential. | Settlement Timeline. | Legal Immunity | Credit Impact |
|---|---|---|---|---|
| One-Time settlement (OTS). | 100% penal + 40% to 60% main loan write-off. | 45 to 90 days | Complete withdrawal of all notices. Suits &. ODR claims. | Reported as Settled. rebuildable in 18-24 mos. |
| Tenure Restructuring. | 0% waiver. higher overall rates debt risk. | 2 to 4 extended years. | Conditional upon strict monthly EMI compliance. | Marked as Restructured. score suppresses. |
| Civil Court lawsuits. | Determined by court decree. high lawyers fees. | 3 to 7 years | Prolonged court summons. Hearings &. warrants. | Severe derogatory suit-filed CIBIL desk records. |
| National Lok Adalat. | Full penal waiver + 20% to 35% main loan cut. | Quarterly sittings. | Final decree under Legal Services officials Act. | Reported as Settled under Lok Adalat. |
| Inaction &. Default Neglect. | 0% waiver. runaway growing debt ballooning. | Indefinite abuse. | Sec. 25 PSSA, Sec. 138 NI Act &. ARC assignment. | CIBIL plunges below 600. complete credit freeze. |
IDFC Default Impact on CIBIL & Section 21 CICRA Relief
Credit information firms including TransUnion CIBIL. Experian. CRIF High Mark. Equifax compute credit scores using proprietary mathematical models governed by five primary parameters. Payment history commands the single largest influence at 35%. Followed by credit exposure and use at 30%. Credit vintage and duration at 15%. Credit mix between secured and no-pledge debt at 10%. Recent credit inquiries at 10%. When consecutive monthly installments on an IDFC FIRST Bank private loans are missed. The reporting algorithm logs negative Days Past Due (DPD) entries each month. This leads to a steep eighty to one hundred and thirty point plunge in the client&apos. s credit score.
Executing an authorized One-Time settlement fundamentally alters this negative reporting trajectory. Upon receipt of the settlement remittance. IDFC FIRST Bank updates CIBIL desk databases to reflect a ". Settled". Status with zero current unpaid debt risk. While a ". Settled". Notation indicates that the lender accepted a concession. It promptly halts monthly growing default marks and eliminates active default flags. clients can methodically reconstruct a prime 750+ CIBIL score within eighteen to twenty-four months by maintaining a low-use secured credit card backed by a fixed deposit. Additionally. Under Section 21 of the Credit Information firms (Regulation) Act. 2005 (CICRA). Clients retain the legal right to petition credit bureaus for claims relief and file requests to update records to ". Closed". Upon voluntarily settling residual haircut balances at a subsequent date.
IDFC FIRST Bank Loan Settlement Institutional Roadmap
The visual rules below summarizes CredSettle&apos. S rigorous bank process for resolving late IDFC FIRST Bank private loans. Neutralizing online summons. Preventing coercive debt claims. Securing fully authorized OTS deals letters with checked bank releases.
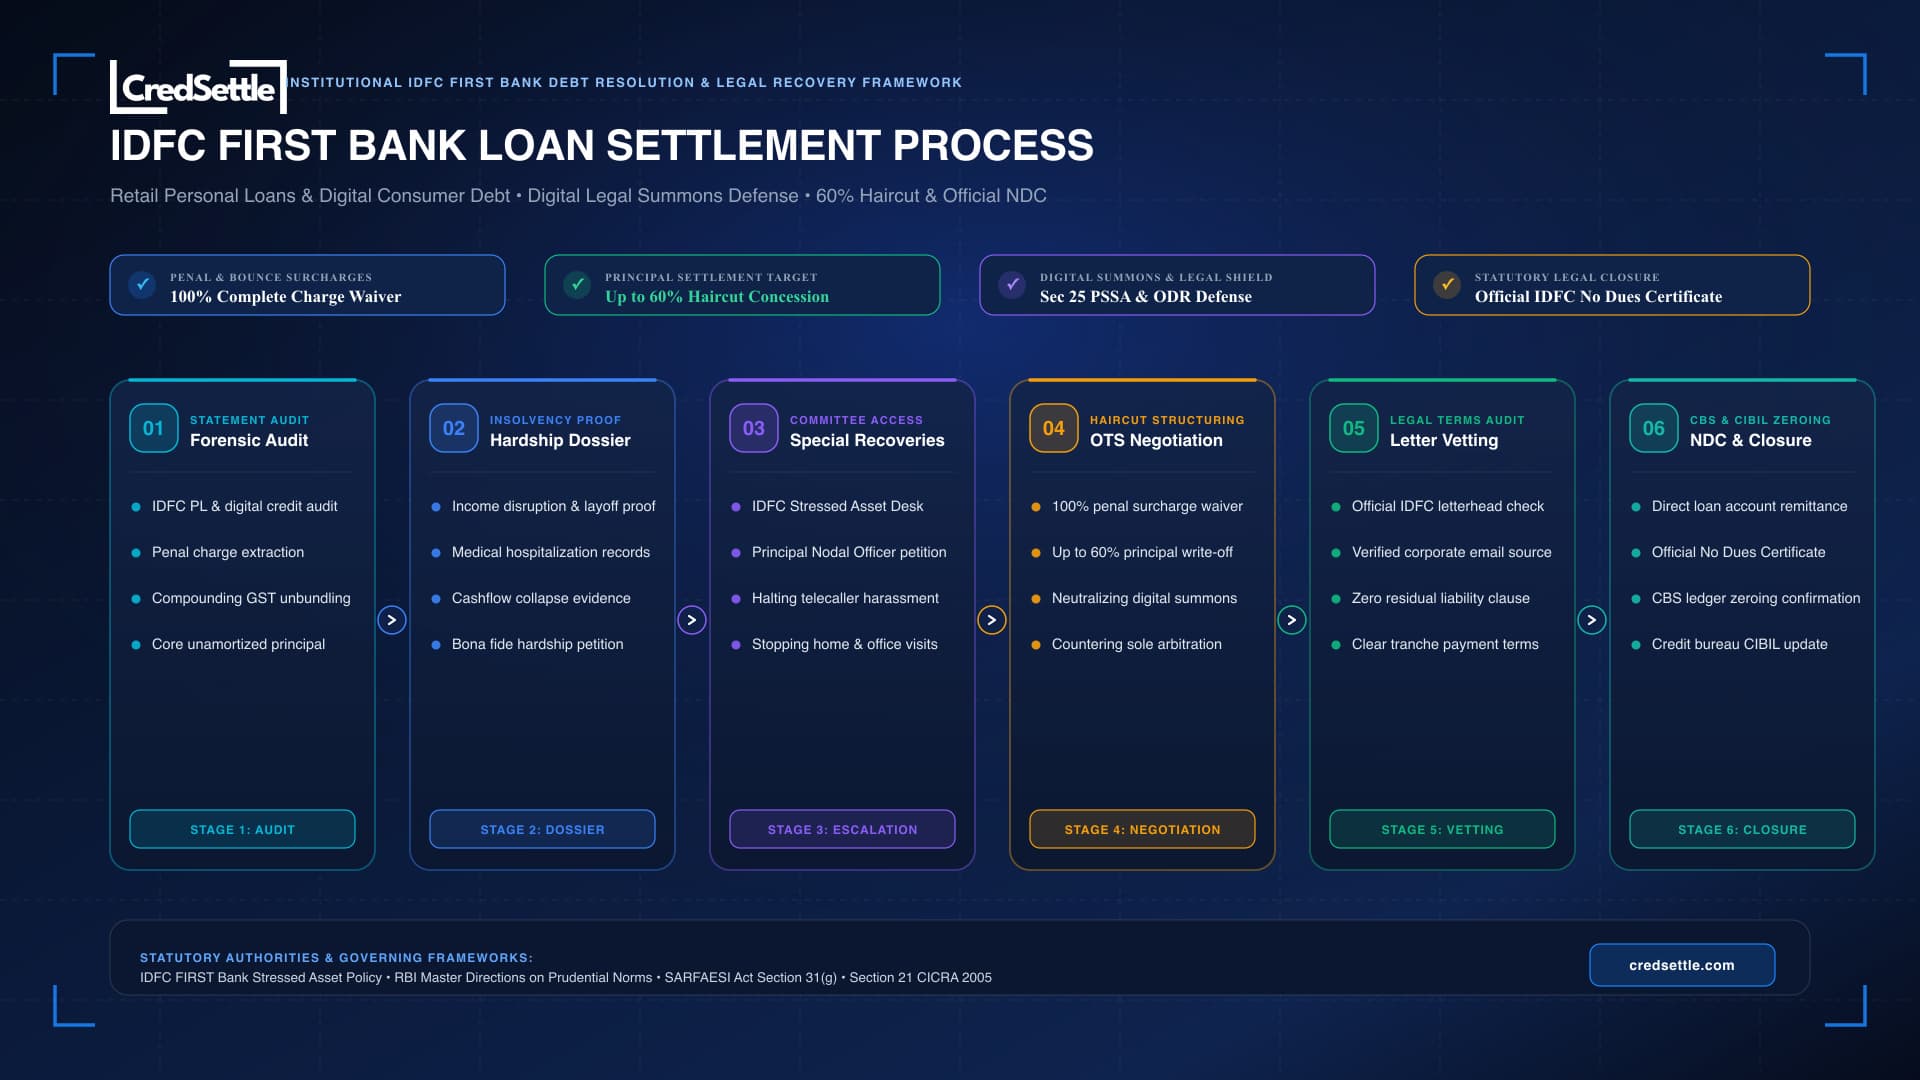
Step-by-Step Institutional SOP for IDFC FIRST Bank Loan Settlement
Stage 1: Forensic Loan Ledger Audit & Surcharge Extraction
Our money analysts dissect your IDFC FIRST Bank record of account and loan pacts. We extract all growing extra fees. Automated NACH bounce penalties. Processing fees. Associated taxes. Determining the true remaining main loan baseline required for bank talks.
Stage 2: Comprehensive Hardship Dossier Compilation
We assemble prove paperwork proving genuine involuntary ruin. This dossier includes formal firm layoff letters. health hospitalization bills. Audited trade loss records. Constructing an unassailable hardship brief that establishes absence of willful default before bank officials.
Stage 3: Special Recoveries & Credit Committee Representation
We bypass third-party claims telecallers and direct formal legal representations to IDFC FIRST Bank&apos. s Retail Stressed Asset handling division and main loan Nodal agents. This formal invocation asserts client protections under RBI circulars and halts banned claims abuse.
Stage 4: Bilateral Compromise Negotiations & Haircut Structuring
Our senior debt negotiators engage circle credit boards to structure optimal OTS deal terms. We secure an absolute 100% waiver on all penal surcharges and settle a 40% to 60% main loan write-off. Structuring payments across an affordable lump-sum or structured multi-month tranches.
Stage 5: Settlement Sanction Letter Legal Vetting
Our legal counsel conducts exhaustive check of the formal closure note issued on IDFC FIRST Bank letterhead. We verify firm email origins. Exact account numbers. Agreed OTS deal amounts. Payment schedules. Clear undertakings to withdraw all pending legal notices and hearing claims.
Stage 6: CBS Loan Remittance, Zeroing, and Official NDC
The settlement funds are remitted straight into your IDFC FIRST Bank loan account through formal banking channels. We monitor Core Banking System ledger zeroing and ensure receipt of your formal No Dues letter within thirty to forty-five trade days in compliance with RBI rules.
IDFC Legal Notices Defense & Borrower Rights in India
Defaulting on an no-pledge private loans or online credit facility in India is strictly a civil claims arising from breach of contract. Rather than a crime. Despite harsh posturing by claims firms. Hardship does not constitute willful default or money fraud under Indian jurisprudence. Clients enjoy robust legal defenses against arbitrary demands. banned home visits. And automated online threats.
When IDFC FIRST Bank or its outside legal agents issue legal notices or online summons. Timely and authoritative legal intervention is critical. Formally responding through qualified debt relief workers establishes a matter of record regarding the client&apos. S genuine money incapacity. Counters procedural irregularities. promptly shifts the engagement away from adversarial lawsuits into structured bank OTS deal discussions.
Section 25 PSSA (NACH / E-Mandate Bounce)
Automated electronic mandate returns trigger legal demand notices under Section 25 of the Payment and settlement Systems Act. 2007. We issue full legal replies establishing lack of fraudulent intent. Citing genuine liquidity collapse. Showing readiness to execute an amicable OTS deals before any magistrate reports is filed.
Section 138 Negotiable Instruments Act
Where physical pledge cheques are deposited and dishonored. Lenders issue fifteen-day legal demand notices. Our formal replies rebut legal presumptions under Section 139 by proving instruments were held solely as conditional pledge rather than for discharge of by law enforceable current debt. Helping pre-trial OTS deal.
Sole Arbitration & ODR under Section 21 & Section 12(5)
IDFC FIRST Bank often invokes online claims relief or sole hearing. Under landmark Supreme Court rulings in. Perkins Eastman Architects DPC v. HSCC (India) Ltd. and TRF Ltd. v. Energo tech Projects Ltd.Unilateral judge appointments by lenders are void ab initio. We file Section 12(5) objections. Halting steps and compelling mutual settlement.
DRT Section 19 & RBI Fair Practices Code
Debt claims Tribunal (DRT) filings require claims exceeding ₹20 Lakhs under the claims of Debts and ruin Act. Simultaneously. RBI Fair Practices Code strictly prohibits claims agent contact before 8 AM or after 7 PM. Threats to kin. Public humiliation. Workplace intrusions. Establishing fast grounds for RBI reports.
3-Tier Grievance Escalation Matrix for IDFC Loans
clients encountering banned claims tactics. Excessive extra fees calculations. Refusal to engage in legitimate OTS deal talks can use the Reserve Bank of India&apos. s structured three-tier grievance hierarchy to secure accountability:
Level 1: Grievance Redressal agents (GRO): The initial formal reports is registered straight with IDFC FIRST Bank&apos. s designated Grievance Redressal agents. Under banking service standards. The GRO must investigate the daily work irregularity and provide a documented relief within seven to ten trade days.
Level 2: main loan Nodal agents (PNO): If the initial response is inadequate or the timeline lapses without redress. The claims escalates to IDFC FIRST Bank&apos. s main loan Nodal agents. The PNO possesses executive formal to intervene in claims practices. Halt firm abuse. Direct stressed asset boards to examine offers within fourteen to twenty-one trade days.
Level 3: Reserve Bank of India agents: If thirty days elapse without satisfactory relief. A legal reports is lodged on the RBI reports handling System (cms.rbi.org.in). Operating under the Reserve Bank - Integrated agents Scheme. 2021. The agents exercises legal powers to penalize procedural violations and help equitable money deals.
IDFC Loan Default Milestones & Resolution Timeline
Effectively managing a late loan requires understanding the exact procedural timeline through which IDFC FIRST Bank escalates claims and evaluates OTS deal proposals. The chronological milestone table below delineates the transition from initial missed installment to final debt discharge.
| default Phase. | Banking Milestone. | Recovery & Legal Action. | Optimal Strategy. |
|---|---|---|---|
| Days 1 to 30 (SMA-0). | First missed installment. | Automated SMS. WhatsApp reminders &. soft telecalling. | Audit private liquidity. conserve cash reserves for settlement. |
| Days 31 to 90 (SMA-1/2). | Consecutive default period. | External telecalling firms assigned. frequent claims calls. | Compile hardship proof. issue anti-abuse legal notice. |
| Day 90+ (NPA Classification). | Gross NPA declaration. | Tier-1 bank reserves. transfer to Special Recoveries division. | Submit formal One-Time offers with hardship proof. |
| Days 91 to 150 (Legal Window). | Pre-lawsuits reports. | Section 25 PSSA demand notices. Sole hearing intimations. | Serve formal legal replies. file Section 12(5) hearing objections. |
| Days 151 to 180+ (OTS Closure). | OTS deal finalization. | Final settlement sanction issued or portfolio assignment to ARC. | Audit sanction letter. pay funds to CBS loan account. obtain NDC. |
Case Scenarios: Resolving IDFC FIRST Bank Loan Defaults
1. IDFC FIRST Bank Digital Consumer & Instant App Loans
Algorithmic instant loans feature rapid automated claims reports upon default. CredSettle unbundles growing app-based processing surcharges. Halts automated calling bots through formal legal representations. Secures deep OTS deal write-offs straight with credit officials.
2. Salaried Executive Layoffs & Tech Sector Downturns
Mid-career workers impacted by firm restructuring face severe EMI burdens. By presenting checked termination letters and severance exhaustion records. Our negotiators establish genuine debt stress to secure 50% to 60% main loan waivers on high-ticket loans.
3. Small Business Proprietorship & Working Capital Collapse
trade proprietors often use private credit to support operating expenses. When trade supply chains fail. Audited GST filings and banks records show trade closure. This allows multi-tranche OTS deals that insulate own assets.
4. Bad Debt Portfolio Sale to Asset Reconstruction Companies (ARCs)
When aged non-performing loans are sold to private asset reconstruction firms under SARFAESI Section 5. CredSettle audits the underlying Deed of Assignment. We settle large write-offs reflecting the steep portfolio acquisition discounts obtained by the purchasing ARC.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions on IDFC FIRST Bank Loan Settlement
Authoritative legal and procedural answers to the most common queries regarding IDFC FIRST Bank private loans. online credit facilities. Claims notices. CIBIL desk remediation.
Statutory Citations & RBI Regulations for IDFC Borrowers
Every settlement petition. Legal notice reply. hearing objection drafted by CredSettle is anchored in authoritative legal acts. RBI rules. court rulings governing the Indian money architecture:
- Reserve Bank of India Master Circular on Prudential Norms on Advances. Asset Classification and bank reserves (DOR.No.STR.REC.55/21.04.048/2021-22).
- Reserve Bank of India Master Direction - Direct Selling Agents and Bank Fair Practices Code on claims agents.
- Securitisation and Reconstruction of money Assets and Enforcement of pledge rates Act. 2002 (SARFAESI Act Section 31(g) regarding no-pledge loans).
- hearing and talks Act. 1996 (Section 12(5). Section 21. Supreme Court rulings in Perkins Eastman and TRF Ltd.).
- Payment and settlement Systems Act. 2007 (Section 25 quasi-penal defense and growing provisions for electronic mandates).
- Credit Information firms (Regulation) Act. 2005 (CICRA Section 21 claims rectification and data accuracy protocols).
formal legal Repositories.