How Much Discount Can You Get on Credit Card Settlement in India?
A full legal and money guide explaining how late cardholders leverage 90 to 180-day default milestones. Unbundle growing 42% APR finance charges. Establish genuine hardship to settle 50% to 75% total debt waivers with scheduled banks.
- Pure Civil Debt: no-pledge credit card default is strictly a civil breach under the Indian Contract Act. 1872. With zero arrest exposure.
- 50% to 75% Average Waiver: clients routinely secure 50% to 75% balance reductions on cards late past 90 to 180 days.
- 100% Penalty Elimination: Banks universally waive 100% of total late payment fees. Overlimit penalties. 18% GST charges.
- Steep APR Cuts: Structured talks eliminate 60% to 80% of growing finance charges accrued at 42% APR.
- 90-Day bank reserves Pressure: Accounts past 90 days trigger strict 100% Tier-1 bank cash bank reserves under RBI rules.
- main loan Haircuts: Severe ruin seasoned past 180 days often secures 25% to 40% haircuts on core main loan spends.
- legal notices Defense: Formal legal replies to Section 25 PSSA notices protect clients and redirect claims into OTS deal talks.
- strict Sanction Letter: Payments must be made solely against formal sanction letters on bank firm letterhead.
- CIBIL Status Remedy: Settled CIBIL desk marks can be upgraded to Closed under Section 21 of CICRA. 2005 upon future payment.
1. Debt Economics: Structural Driver of Card Waivers
Credit cards represent the most expensive no-pledge revolving credit in the Indian banking system. Trade card issuers levy monthly finance charges of 3.5% to 4.2%. Creating an effective Annual Percentage Rate (APR) exceeding 42% to 52%. When cardholders face unexpected debt stress. Paying only the strict 5% Minimum Amount Due triggers a severe growing cycle. Minimum payments merely service total rates and 18% GST. Leaving underlying main loan balances completely unamortized while record totals escalate.
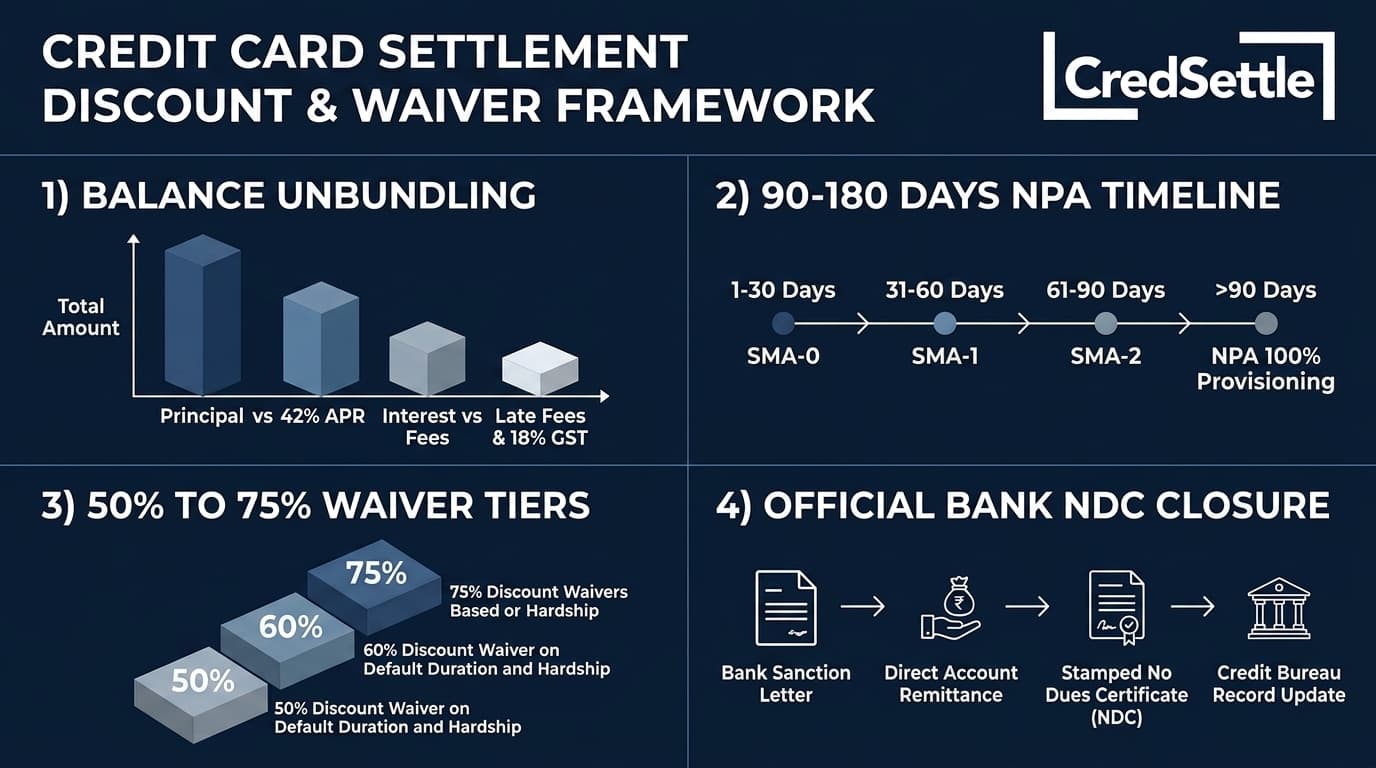
Under Reserve Bank of India prudential rules. late accounts transition across Special Mention Account stages: SMA-0 (1-30 days late). SMA-1 (31-60 days). SMA-2 (61-90 days). Beyond 90 days. The account is classified as a Non-Performing Asset (NPA). Mandating 100% Tier-1 cash bank reserves by the lending institution.
Because credit cards lack mortgage or hypothecated pledge. Banks cannot enforce summary pledge claims under the SARFAESI Act. 2002. Also. Instituting civil summary suits under Order 37 CPC entails lengthy lawsuits and high legal costs. As a result. Banks maintain distressed debt boards empowered to sanction large One-Time deals (OTS) to recover compromised cash.
2. Financial Breakdown: Core Principal vs Inflated Dues
A late credit card record rarely reflects true economic debts. Over 6 to 9 months of default. Issuers continuously stack 42% APR finance rates. Late fees. Overlimit charges. 18% GST. A deep record audit unbundles these stacked charges to isolate the net core main loan from penalty inflation.
During One-Time settlement discussions. Card issuers adhere to an established bank waiver hierarchy. Banks readily grant 100% waivers on late payment fees. Overlimit penalties. GST. Also. Talks eliminate 50% to 80% of cumulative finance rates. For seasoned non-performing assets aged beyond 180 days with documented hardship. Banks often grant direct 20% to 40% main loan haircuts.
Representative 180-Day Credit Card Settlement Breakdown
Actual money deep model for unbundling late revolving card balances.
3. Strategic Options Comparison: Evaluating Debt Relief Pathways
clients facing severe credit card default must evaluate available debt relief pathways based on money burden. Legal finality. CIBIL desk implications:
| Resolution Route. | Governing Framework. | Financial Burden & Waiver. | Timeline to Closure. | Legal Risk & Finality. |
|---|---|---|---|---|
| One-Time settlement (OTS). | RBI Stressed Asset rules. | 50% to 75% gross waiver. | 30 to 60 Days | Complete legal discharge and clean NDC. |
| Term Loan Restructuring. | Internal Bank Retail Policy. | Zero debt waiver. Converted at 14% to 18%. | 24 to 48 Months | High ongoing re-default risks. |
| Civil Summary Suit. | Order 37 CPC | Full ledger claim plus 18% lawsuits rates. | 3 to 7 Years | Decree execution &. asset attachment. |
| National Lok Adalat. | Legal Services officials Act. 1987. | 30% to 50% rates waiver. | Single-Day Award. | Binding non-appealable award. |
| Inaction / Defaulting. | Unregulated claims Dynamics. | Unchecked 42% growing. | Indefinite | claims abuse &. ARC debt sale. |
4. CIBIL Algorithm: Post-Settlement Credit Recovery
The TransUnion CIBIL scoring model evaluates clients credit across five weighted parameters: Payment History (35%). Credit use (30%). Credit History Length (15%). Credit Mix (10%). Recent Inquiries (10%). Defaulting past 90 DPD triggers a sharp score drop of 120 to 180 points.
Executing an formal One-Time settlement updates the CIBIL desk status to Settled. While this notation confirms that the account closed with a settled OTS deal. It permanently halts active monthly late DPD reporting. Cardholders can systematically rebuild their score above 750 within 18 to 24 months by using a Fixed Deposit secured credit card and keeping use strictly below 20%.
also. Under Section 21 of the Credit Information firms (Regulation) Act. 2005 (CICRA). Clients retain the legal right to pay the residual waived balance in the future. Obtaining a No Dues letter and converting their CIBIL status from Settled to Closed.
Visual Blueprint: Card Settlement Discount Framework
5. Settlement SOP: 6 Stages to Maximum Debt Waivers
Securing a 50% to 75% credit card settlement discount requires a disciplined standard operating steps to maximize waivers and secure legal closure:
Stage 1: Forensic Statement Audit
Line-by-line record audit separating core main loan from growing 42% APR rates. Late fees. GST to establish baseline debt risk.
Stage 2: Hardship Dossier Compilation
Assembling documentary proof of distress including termination notices. Salary reduction slips. Audited trade losses. And health records.
Stage 3: Institutional Escalation
Serving formal legal representations to bank Nodal agents. Citing the RBI Fair Practices Code to halt claims agent abuse.
Stage 4: Stressed Asset Negotiation
Presenting structured hardship proposals before credit boards. Leveraging 90-day NPA bank reserves pressures for 50% to 75% waivers.
Stage 5: Settlement Sanction Vetting
deep legal vetting of the bank closure note. Verifying firm domain authenticity. Payment schedules. And debt risk discharge.
Stage 6: Direct Card Remittance
Depositing OTS deal sums straight into the credit card account. Securing a stamped No Dues letter. Updating CIBIL desk records.
6. Statutory Notice Defense: Legal Protections
When card default extends past 90 days. Bank legal units issue legal demand notices to enforce calls. Serving structured formal legal replies protects cardholders:
Issued for dishonored electronic NACH mandates. Serving a formal reply within 15 days establishes genuine hardship without fraudulent intent. Directing steps toward structured OTS discussions.
Issued when pledge cheques bounce. Legal defense contests arbitrary extra fees stacking and banned presentation of undated instruments. Shielding cardholders from penal debt risk.
Banks often invoke private hearing. Under Supreme Court rulings in TRF Ltd. And Perkins Eastman. Unilateral sole judge appointments are de jure invalid under Section 12(5).
DRT police area is strictly restricted to claims exceeding ₹20 Lakhs. The RBI Fair Practices Code strictly prohibits calling before 8 AM or after 7 PM. Workplace visits. Third-party disclosure.
7. Grievance Escalation Hierarchy: 3-Tier Matrix
If card issuers ignore hardship representations or violate fair claims norms. Cardholders can escalate through the structured three-tier grievance hierarchy:
Bank Grievance Redressal Officer (GRO)
Submitting initial formal reports regarding unlawful extra fees or harsh claims tactics. relief timeline of 7 to 10 working days.
Principal Nodal Officer (PNO)
Escalating to senior bank handling for stressed asset re-evaluation and special OTS approvals. Turnaround timeline of 14 to 21 working days.
RBI Integrated Ombudsman (CMS Portal)
Filing legal reports via cms.rbi.org.in if grievances remain unresolved past 30 days. This provides binding claims relief at zero cost.
8. Chronological Resolution Milestones: Default Cycle to Debt Freedom
Understanding how bank claims plans evolve across the 180-day default cycle enables clients to initiate talks during the peak waiver window:
| Timeline Milestone. | Bank Classification. | Lender Recovery Actions. | Strategic Borrower Action. |
|---|---|---|---|
| Days 1 - 30 | SMA-0 | SMS alerts and late fee application. | Audit record. stop minimum dues payments. |
| Days 31 - 60 | SMA-1 | Telecalling and 42% APR rates growing. | Compile documented hardship dossier. |
| Days 61 - 90 | SMA-2 | firm allocation and demand notices. | Engage debt relief team to halt abuse. |
| Days 91 - 120 | NPA Classification. | Card blocked. 100% bank bank reserves enforced. | Serve formal legal response contesting dues. |
| Days 121 - 150 | Peak OTS Window | Bank reviews write-off vs claims. | settle 50% to 75% gross balance waiver. |
| Days 151 - 180+ | settlement &. Closure. | Sanction letter issued on bank letterhead. | pay funds straight to bank and obtain stamped No Dues letter. |
9. Real-World Scenarios: Card Settlement Negotiations
expert debt relief plans must account for expert client situation to optimize settlement discounts and protect client rights:
Multi-Card Portfolio Consolidation
settling simultaneously across multiple credit cards from different issuers to synchronize settlement schedules. Eliminate cross-exposure risks. Secure combined waivers exceeding 60%.
Corporate Layoffs & Income Shocks
showing involuntary job termination. Severe salary reductions. Prolonged health crises to justify large main loan haircuts on high-limit premium cards.
MSME Proprietorship Capital Distress
Segregating private credit cards used for firms working cash from daily work debts. Using audited GST returns to settle standalone retail debt relief.
Asset Reconstruction Company (ARC) Portfolios
settling with ARCs like Phoenix or Encore that acquired written-off debt portfolios at deep discounts. Unlocking potential settlement waivers of 70% to 80%.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions: Card Settlement Discounts
Authoritative legal and money answers regarding credit card deals. Waivers. CIBIL score implications. And legal protections:
Official Regulatory Citations & Outbound Reference Portals
- Reserve Bank of India Master Directions (2022): Master Direction - Credit Card Issuance and Conduct Directions. 2022 (RBI/2022-23/92). Governing billing transparency and claims codes.
- Reserve Bank - Integrated agents Scheme. 2021: legal claims relief options providing cost-free adjudication for unfair banking and credit card claims practices.
- Credit Information firms (Regulation) Act. 2005 (CICRA): Section 21 and Section 22 governing credit reporting accuracy and conversion of Settled records.
- Supreme Court of India Jurisprudence: Perkins Eastman Architects DPC (2020). and TRF Ltd. (2017) regarding the invalidity of unilateral judge appointments.
- Payments and settlement Systems Act. 2007 (PSSA): Section 25 rules and court defenses concerning electronic auto-debit bounce notices.