CIBIL Score Kaise Badhaye After Loan Settlement (750+ Strategy)
Loan closure ke baad CIBIL score kaise badhaye? Janiye closure remark kyu lagta hai. Status closed mein kaise badlein. Aur secured credit card se 12 se 24 mahine mein 750+ score kaise hasil karein.
- Settled Remark: closure ke baad bank status Settled report karta hai jisse score 70-120 points girta hai.
- Mandatory NDC: closure ke 30 dino mein bank se valid NDC lena aur zero balance check karna anivarya hai.
- Secured Card: Score claims ke liye FD-backed card sabse tezi se positive payment track banata hai.
- Strict CUR: Scoring algorithms ke liye credit utilization hamesha 15% se 20% ke andar maintain karein.
- digital Weight: CIBIL formula mein 35% weight payment history ka hai. Isliye zero late payment rakhein.
- Status Upgrade: Capacity aane par waived main sum pay karke settled remark ko closed mein upgrade karein.
- CICRA Section 21: Galat reporting par clients ko credit desk aur bank ke samne dispute ka adhikar hai.
- Avoid Loan Spamming: Repeated loan applications se bachein kyunki hard inquiries credit score ko hurt karti hain.
- 12-24 Mo. Window: Systematic discipline se 550 score ko dobara prime 750+ level par pahunchaya ja sakta hai.
1. Debt Economics: Loan Settlement Ke Baad CIBIL Score Kyu Girta Hai?
Jab clients genuine money crisis jaise job loss ya firm loss ke karan own loan EMIs pay nahi kar pata. Toh 90 days non-payment ke baad account NPA ban jata hai. NPA banne par RBI provisioning rules ke tehat bank ko 100% Tier-1 capital block karna padta hai. Is provisioning burden aur claims litigation costs se bachne ke liye banks One-Time closure (OTS) offer karte hain jisme penal charges waive karke reduced amount par deal closure hota hai.
closure ke baad bank credit bureaus ko account status Closed ke bajaye Settled report karta hai kyunki bank ne waived balance ko operational loss ke roop mein write-off kiya hota hai. Yeh Settled remark automated Loan Origination Systems ke liye risk flag ban jata hai. Jisse score 70 se 120 points girta hai aur naye clean loans auto-reject hone lagte hain.
2. Financial Breakdown: Status Conversion Math
Defaulted loan accounts mein total balance ka bada hissa growing penal rates aur bounce charges ka hota hai. CredSettle ki talks se yeh charges waive ho jate hain aur closure purely adjusted main sum par hota hai. Closure ke baad CIBIL report par Current Balance ₹0 hota hai. Par Written-off column mein waived amount reflect hoti hai.
Bhavishya mein money position strong hone par aap bachi hui main sum differential amount pay karke bank se formal NDC aur desk par Closed status update prapt kar sakte hain.
3. Comparison Matrix: CIBIL Rebuilding Trajectory
Alag-alag debt relief options. Unke reporting status aur CIBIL claims timeframe ki tulna:
| Resolution Route | CIBIL Status Reported | Immediate Score Impact | Rebuilding Timeframe | Prime Loan Eligibility |
|---|---|---|---|---|
| One-Time closure | Settled / Written-off | Drops 70-120 pts | 12-24 Months (Secured Route) | Restored after 18-24 Mo. |
| Loan Restructuring | Restructured Account | Drops 40-60 pts | 6-12 Months | Restored after 12 Mo. |
| Full payment | Closed (Past DPD logged) | Stabilizes quickly | 6-9 Months | fast post-update |
| Secured Rebuilding | Active (0 DPD streak) | +15 to +25 pts / qtr | 12-18 Months | Prime 750+ Achieved |
| money Inaction | Suit Filed / Wilful Default | Drops below 500 | Indefinite Freeze | Permanently Blocked |
4. CIBIL Scoring Math: 5 Factors & Recovery Steps
TransUnion CIBIL score 300 se 900 ke numerical scale par automated mathematical algorithm calculate karta hai. Is algorithm mein sabse bada weight Payment History (35% Weight) ka hota hai jo 36 mahino ke Days Past Due (DPD) record ko measure karta hai. closure hone par purani DPD cycle negative signal deti hai.
Doosra pramukh factor Credit Utilization Ratio (30% Weight) hai. Jo credit limit ke mukable used balance ko check karta hai. Baki factors mein Credit History Duration (15% Weight), Credit Mix (10% Weight) jisme secured aur clean debt ka balance dekha jata hai. Aur New Hard Inquiries (10% Weight) shamil hain. Score rebuild karne ke liye 35% payment track aur 30% utilization ko strategically leverage kiya jata hai.
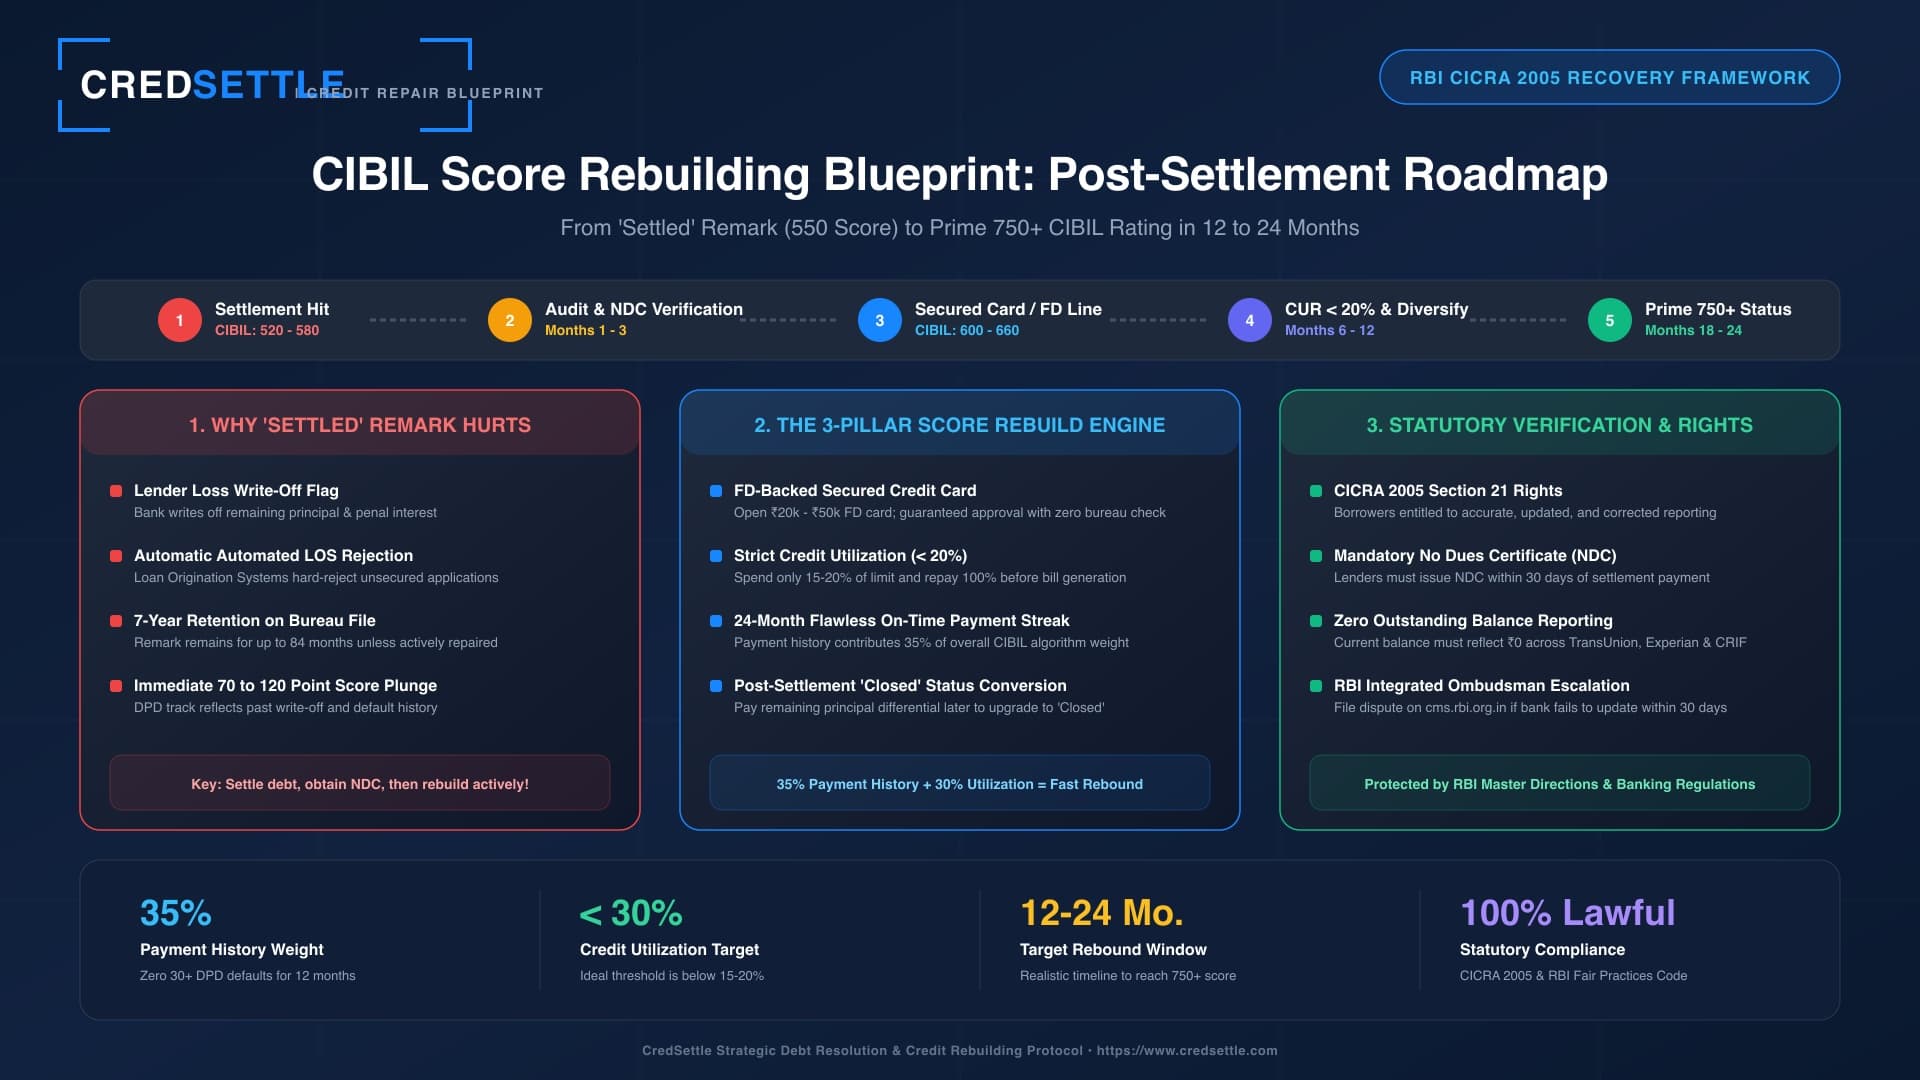
Visual Blueprint: CIBIL Score Rebuilding Trajectory (Settled to 750+)
Neeche diya gaya infographic loan closure ke baad CIBIL score ko 550 se dobara 750+ prime tier tak le jaane ka roadmap darshata hai:
6. Step-by-Step SOP: 6 Stages of CIBIL Score Restoration
Follow this battle-tested 6-stage protocol to rebuild your credit rating post-closure:
Forensic CIR Audit
CIBIL. Experian. CRIF aur Equifax reports download karein. check karein ki settled account par Current Balance ₹0 show ho raha hai aur koi live fine add nahi ho rahi.
NDC Procurement
Bank se valid No Dues letter lein. Agar 45 dino baad bhi balance zero na ho. Toh CICRA Section 21 ke tehat desk portal par dispute raise karein.
Secured Credit Card
trade bank mein ₹25,000 se ₹50,000 ki FD karke secured card lein. Yeh cards bina credit check ke instant issue hote hain aur positive DPD banate hain.
Utilization Optimization
Secured card par total limit ka kewal 15% se 20% spend karein. Regular utility bills card se pay karein aur due date par 100% full payment karein.
Credit Mix Diversification
6-9 mahine regular card payments ke baad chhota consumer durable loan add karein. Yeh credit mix balance karke score 700 cross karwata hai.
Status Conversion &. 750+
Prime loans ke liye bank ko main sum differential pay karke settled remark ko Closed mein convert karein. 18-24 mahine mein score 750+ ho jayega.
7. Statutory Rights & Legal Protections in Credit Bureau Reporting
Credit Information Companies Act Section 21 ke tehat clients ko wrong data challenge karne ka right hai. Bureaus aur banks ko dispute date se 30 dino mein records correct karna mandatory hai.
RBI Master Directions ke anusar sabbhi banks aur NBFCs ko har mahine loan closures aur zero balances sabhi 4 licensed bureaus ko synchronized tarike se submit karna mandatory hai.
deal closure pay hone aur NDC milne ke baad lender Section 25 PSSA ya Section 138 NI Act steps initiate nahi kar sakta. Sabhi claims discharge ho jate hain.
High Courts aur Consumer Forums ke rulings ke mutabik agar bank closure ke baad bhi wrong default report karta hai. Toh clients compensation claim karne ka haqdar hai.
8. The 3-Tier Escalation Matrix for Credit Report Corrections
Agar closure ke baad bank CIBIL par balance zero nahi karta ya NDC issue karne mein delay karta hai. Toh 3-tier escalation hierarchy use karein:
Grievance Redressal head
Bank ke dedicated GRO desk ko formal grievance submit karein. Turnaround: 7-10 working days.
main sum Nodal head
relief na milne par matter bank PNO desk ko escalate karein. Turnaround: 14-21 days.
Integrated RBI officer
30 dino mein satisfactory relief na milne par RBI Portal cms.rbi.org.in par complaint darj karein.
9. Chronological Timeline Table: 1 to 24 Months Score Recovery
closure ke baad CIBIL score claims ek gradual digital process hai. Neeche diye gaye milestone roadmap ko follow karein:
| Timeline Period | Operational Milestones & Actions | Target CIBIL Range | Credit Accessibility |
|---|---|---|---|
| Month 1-3 | Closure audit. NDC receipt. Zero balance desk reporting verification. | 530-580 | Only FD-backed cards. |
| Month 3-6 | Secured card setup. Strict utilization (<. 20%). On-time payment streak. | 590-640 | Secured cards, BNPL. |
| Month 6-12 | Add consumer durable EMI line. Zero hard inquiries. Clean DPD track. | 650-700 | Co-branded cards. |
| Month 12-18 | First clean card approval. Credit limit enhancement on cards. | 710-740 | clean cards. |
| Month 18-24 | Optional status conversion to Closed. Prime profile restoration. | 750+ Prime | Home &. own Loans. |
10. Specialized Credit Repair Scenarios & Tailored Solutions
Multiple Settled Accounts
Agar multiple accounts settle hue hain. Toh sabhi ke NDCs collect karein. Rebuilding phase mein ek central secured card se positive payment frequency establish karein.
Salaried firm Verification
MNCs pre-employment checks mein CIBIL check karti hain. Settled loan par valid NDC aur zero balance show karne par employment check smoothly clear ho jata hai.
firm MSME Capital
Proprietors jinke own loans settle hue hain. Unhe firm credit ke liye GST turnover based loans ya CGTMSE schemes use karni chahiye jab tak CIBIL 720+ na ho.
ARC-Assigned Debt
ARCs ko assign hue loans mein closure pacts aur Section 5 SARFAESI compliance confirmation letter lena desk updation ke liye mandatory hota hai.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
12. Frequently Asked Questions: CIBIL Score & Loan Settlement
CIBIL score improvement. Settled status conversion aur credit rebuilding ke sabhi aam sawalo ke authoritative uttar:
Official Regulatory Citations & Credit Bureau Authorities
- Credit Information Companies (rule) Act. 2005 (CICRA): Sections 18. 19. 21 and 22. Ministry of Finance. Government of India.
- Reserve Bank of India Master Directions: Master Direction on Credit Information Companies Guidelines and Fair Practices Code (Updated 2026).
- Reserve Bank - Integrated RBI officer Scheme. 2021: legal Grievance Redressal for Defective Credit Reporting and Delay in NDC Issuance.
- Banking rule Act. 1949: Section 35A read with Prudential Norms on Asset Classification.