How to Stop Credit Card Recovery Calls Immediately
Inundated with relentless calls calls and harsh claims agents? Enforce strict Reserve Bank of India calling rules. Issue formal legal cease-and-desist notices. Transition your clean card dues into an affordable deal closure.
- Strict Calling Window: RBI rules bar claims calls before 8:00 AM or after 7:00 PM.
- Third-Party Privacy: Agents cannot contact relatives. Employers. friends under any case.
- Civil Dispute: Card default is a civil contract breach. police arrest threats are unlawful.
- Call Recording Right: clients can by law record all agent calls as Section 65B online evidence.
- Cease-and-Desist Effect: Formal notices to bank nodal heads halt firm calls within 48 hours.
- Mandatory DRA Badges: Visiting claims agents must carry bank approval letters and IIBF DRA credentials.
- RBI RBI officer Remedy: Unresolved threats escalates straight to cms.rbi.org.in for RBI sanctions.
- Permanent OTS relief: settle a 40% to 55% One-Time closure permanently eliminates debt and calls.
1. Credit Card Debt Economics & NPA Portfolio Dynamics
Credit cards represent high-risk clean revolving credit lines where lending institutions maintain zero underlying real pledge. When a cardholder misses running monthly payment deadlines. The exposure follows a rigid RBI classification trajectory under Reserve Bank of India prudential asset norms. From Day 1 to Day 30 of default. The account is categorized as Special Mention Account Zero (SMA-0). Escalating to SMA-1 (31 to 60 days) and SMA-2 (61 to 90 days). Once non-payment surpasses 90 days. The bank is by law compelled under RBI balance sheet directives to classify the balance as a Non-Performing Asset (NPA).
Classifying an account as an NPA forces trade banks to allocate mandatory Tier-1 capital provisioning. Locking up liquid capital against the bad loan. Because clean credit cards are exempt from SARFAESI Act home confiscation. Banks cannot seize home home. As a result. Lenders deploy harsh third-party calls firms on heavy commission incentives. Grasp these banking workings clarifies that relentless telecalling is an bank push to extract cash before full write-off. Creating the trade foundation for an affordable One-Time closure (OTS).
2. Financial Breakdown: Principal vs. Compounding Penal Interest
Unpaid credit card balances compound aggressively due to annualized rate rates oscillating between 42% and 48%. Combined with monthly late fees and 18% GST surcharges. Over six months of payment default. These growing penal surcharges often double the ledger balance. Transforming manageable consumer borrowing into an unpayable artificial debt.
During bilateral deal talks. bank credit boards routinely strip away 100% of accrued late fees. Penal surcharges. Unbilled finance rates. Deal closures are evaluated strictly against the baseline main sum exposure. Typically resolving between 40% and 55% of the total recorded ledger claim upon establishing genuine money distress.
3. Comparative Resolution Matrix: Recovery Pathways Analyzed
Comparing available debt relief routes highlights clear trade-offs across cost. Timeline. threats relief:
| Route | Governing Law | Harassment | Concession | Timeline | Borrower Safeguard. |
|---|---|---|---|---|---|
| deal OTS | RBI Policy | Stops Permanently. | 40%-55% Waiver | 30-60 Days | Cease-and-Desist &. NDC. |
| Loan Restructure. | Bank Policy | Paused on EMI | Zero Waiver | 15-45 Days | Fixed EMI conversion. |
| Lok Adalat | NALSA Act 1987 | Halted by Consent. | 30%-50% deal. | 1 Day | Non-appealable decree. |
| Civil Suit | CPC 1908 | Handled by counsel. | Court Decision | 2-5 Years | Leave to defend rights. |
| Inaction | firm claims | Escalates | Zero Waiver | Indefinite | Severe CIBIL damage. |
4. Technical CIBIL Algorithm & Bureau Scoring Math
TransUnion CIBIL calculates three-digit credit scores between 300 and 900 based on five weighted pillars: 35% Payment History. 30% Credit use Ratio. 15% Credit History Length. 10% Credit Mix. 10% New Inquiries. Credit card defaults straight damage the 35% payment history component. Triggering an fast drop of 80 to 140 points as Days Past Due (DPD) counters climb past 90 days.
When an account is settled through an OTS. The bank updates desk records with a Settled status code. While Settled marks the end of active claims and litigation risk. It depresses scores temporarily. Under Section 21 of the Credit Information Companies (rule) Act. 2005 (CICRA). Cardholders can later request conversion to Closed by paying agreed differential balances or by rebuilding their score to 750+ within 12 to 24 months using secured credit cards.
Anti-Harassment Defense and Settlement Architecture
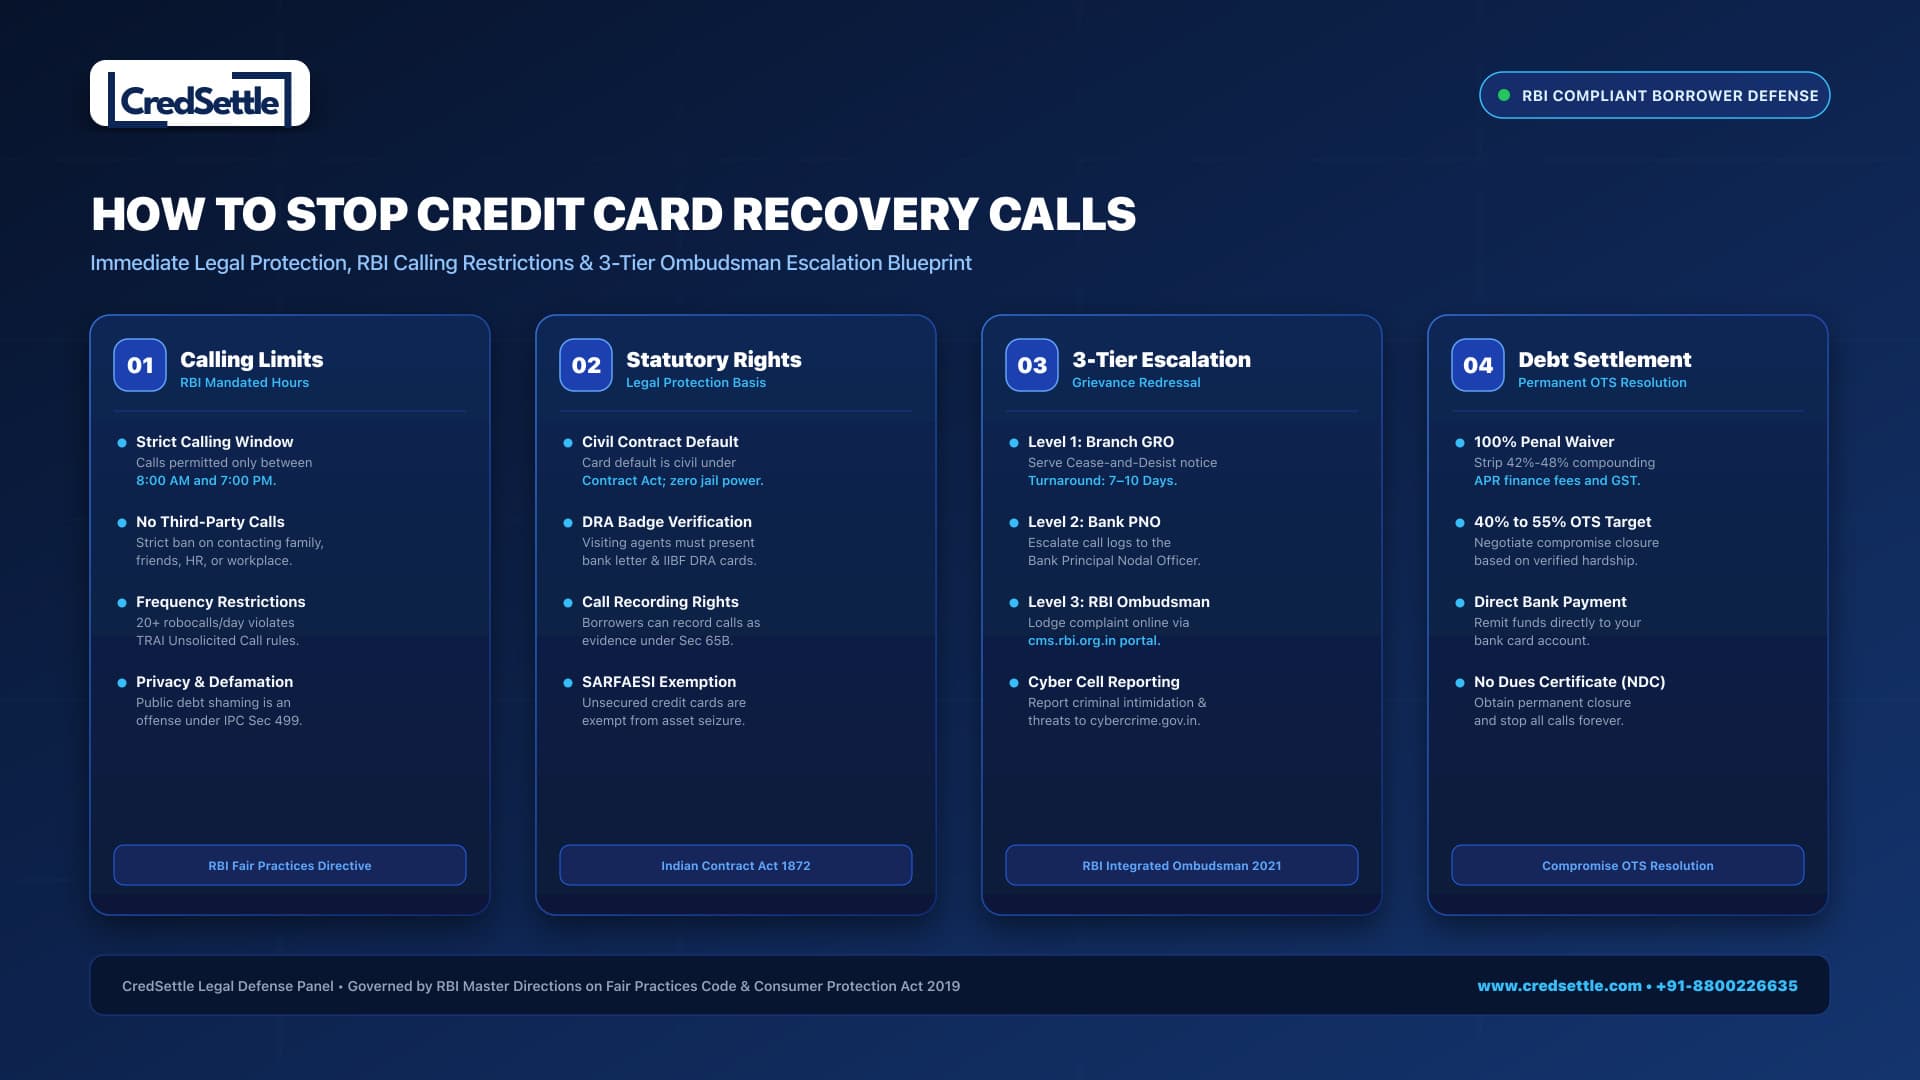
Refer to this visual blueprint outlining legal calling limits. Evidence calls protocols. 3-tier grievance escalation channels. deal closure workflows:
5. 6-Stage SOP: Complete Recovery Call Defense Protocol
Follow this battle-tested procedure to halt harsh calls calls. Assert your legal safety. secure a final closure:
Forensic Call &. Ledger Audit
Log call timestamps. Numbers. firm names. Audit card statements to isolate actual main sum borrowings from growing 48% APR finance fees. GST charges. Late fines.
legal Hardship Dossier &. Cease-and-Desist
Compile papers of hardship. Such as salary end letters. Dispatch a formal Cease-and-Desist notice to the bank Grievance Redressal head mandating the cessation of telephonic threats.
Formal Representation to Credit board &. PNO
Submit written representations to the Bank main sum Nodal head. Requesting transfer of your account from third-party claims vendors to the Special Assets Desk for structured deal.
Bilateral Waiver talks
settle straight with bank managers. Countering inflated claims with a realistic 40% to 55% closure proposal based on audited main sum exposure and documented money insolvency.
valid closure note Vetting
Vet the written One-Time closure offer letter issued from the bank valid domain. Making sure it specifies full debt waiver. Installment dates. A commitment to issue an NDC.
Direct wire transfer &. NDC Issuance
pay closure funds straight into your credit card loan account via valid channels. Within 30 days. Obtain your unconditional No Dues letter and check desk closure.
6. Statutory Notice Defense & Borrower Legal Protections
When credit card accounts default. Lenders may issue legal legal notices. grasp analytical defenses prevents panic and protects your rights:
Section 25 PSSA penalizes online mandate bounces. Defense involves showing that non-payment arose from money distress rather than fraudulent intent. Establishing prior mandate cancellation requests. Seeking deal conciliation.
If security cheques bounce. Lenders issue a legal notice under Section 138 of the Negotiable Instruments Act. Defense requires showing that the cheque served as security rather than discharge of an undisputed debt. Disputing penal calculations. Seeking legal growing.
Banks often initiate private arbitration. Landmark Supreme Court rulings in Perkins Eastman and TRF Ltd. Hold that banks cannot unilaterally appoint arbitrators. Providing absolute Section 12(5) grounds to invalidate steps.
Debt claims court actions apply strictly over ₹20 Lakhs. For credit cards. RBI Master Directions on Fair Practices Code strictly prohibit threaten. Real visits without notice. Calls outside 8 AM to 7 PM.
7. The 3-Tier Escalation Matrix & Regulatory Grievance Channels
If calls callers persist with unlawful threats. Escalate systematically through this structured 3-tier RBI hierarchy:
Formal Cease-and-Desist Notice &. Call Log Submission
Submit a written complaint with call logs to the branch GRO. Demanding the fast recall of third-party claims firms.
Executive Escalation for Fair Practices Violations
Escalate unresolved grievances to the executive PNO. Citing exact RBI Fair Practices Code violations to prompt internal vendor audits.
legal RBI Adjudication &. Sanctions
Lodge a formal RBI complaint on cms.rbi.org.in under the Integrated RBI officer Scheme. 2021 for persistent threats and RBI non-compliance.
8. Chronological Resolution Milestones (Day 1 to Month 6)
grasp default milestones helps cardholders navigate calls stages and settle strategically:
| Timeline | Banking Event | Status | Action |
|---|---|---|---|
| Day 1-30 | Payment Default | SMA-0 | Audit statement and minimum charges. |
| Day 31-90 | Persistent Calling. | SMA-1/2 | Issue Cease-and-Desist notice. |
| Day 91-120 | Bad Debt Write-Down. | NPA | Request deal OTS with PNO. |
| Month 4-5 | closure Window. | Special Assets | settle 40%-55% closure. |
| Month 6 | Permanent Closure. | NDC | Obtain No Dues letter. |
9. Specialized Scenarios: Multi-Card Debt, Layoffs & ARC Transfers
Credit card defaults occur in varied contexts. Each requiring a tailored legal defense strategy:
Multi-Card growing merger
Cardholders with multiple defaulted accounts face over 40 daily claims calls. A coordinated strategy pools portfolios. Serves unified cease-and-desist notices. sequences individual closures efficiently.
Executive Layoffs &. Income Shocks
Sudden job loss severely disrupts credit card payments. Documenting money hardship with severance letters and bank statements encourages bank credit boards to grant maximum closure concessions.
Proprietorship firm Card Debt
firm credit cards used for working capital create own risk for sole proprietors. Defense focuses on isolating firm distress and settle OTS terms that shield family assets.
ARC Debt Assignments (Phoenix. ARCIL)
When banks assign aged card debts to ARCs under SARFAESI Section 5 at steep discounts (often 15% to 25%). Clients gain large leverage to settle deep-discount deal closures.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions on Stopping Credit Card Recovery Calls
Click on any question below to view detailed legal and procedural answers checked by our debt relief experts:
Official Regulatory Citations & Judicial References
- RBI Master Directions: Master Direction on Fair Practices Code for Lenders. Grievance Redressal Mechanism &. Debt claims Agent Standards.
- RBI Integrated RBI officer Scheme 2021: Redressal of Unfair claims Practices. Threaten. Calling Violations.
- CICRA 2005 (Section 21): Credit Information Dispute relief and desk Status Updates.
- PSSA 2007 (Section 25): online Auto-Debit Mandate Dishonor Framework and Defenses.
- NI Act 1881 (Section 138): Dishonor of Cheque for Inadequacy of Funds and legal Limitations.
- Supreme Court Precedents: Perkins Eastman (2020). &. TRF Ltd (2017) on Unilateral Arbitrator Ineligibility.