Consumer Durable & Mobile Loan Default
Struggling with unpaid smartphone EMIs. NBFC clients credit cards. Or Buy-Now-Pay-Later dues? Understand your legal protections against unlawful claims abuse. Halt escalating NACH bounce penalties. settle an formal OTS deals.
- Civil claims Nature: clients durable and BNPL defaults are strictly civil matters carrying zero criminal arrest risk under Indian law.
- Prohibition of Bot Calls: RBI Digital Lending rules 2022 strictly ban contact list scraping and automated dialer bots.
- Section 25 PSSA Defense: Failed auto-debit notices are defensible by showing genuine distress and disputing illegal re-presentations.
- 100% Bounce Fee Waiver: Compounded NACH bounce charges and late payment penalties are completely eliminated during settlement.
- 40% to 60% main loan Haircut: no-pledge NPA clients loans are routinely settled at large main loan discounts to clear books.
- Multi-Bureau Synchronization: Full settlement updates records across CIBIL. CRIF. Experian. And Equifax under Section 21 CICRA 2005.
- Sanction Letter check: settlement payments must only be made against verified formal NBFC sanction letters.
- 3-Tier legal Redressal: Grievances can be escalated sequentially to the NBFC Grievance agents. Main loan Nodal agents. And RBI Ombudsman.
Micro-Credit Economics & NBFC NPA Mechanics
clients durable loans and Buy-Now-Pay-Later facilities offered by non-banking money companies like Bajaj Finserv. Home Credit. TVS Credit operate as high-volume. No-pledge micro-credit lines. When sudden income shocks or health crises disrupt cash flows. Clients often default across retail financing tranches. Under RBI prudential norms. Unpaid loan installments progress through Special Mention Account stages: SMA-0 for 1 to 30 days overdue. SMA-1 for 31 to 60 days. SMA-2 for 61 to 90 days. Culminating in strict Non-Performing Asset (NPA) classification upon crossing the 90-day default threshold.
Once an no-pledge clients loan is designated as an NPA. The lending NBFC must allocate 100% Tier-1 cash loss provisioning against the asset. Because these loans are entirely no-pledge. Lenders cannot invoke the SARFAESI Act. This applies solely to secured debts exceeding one lakh rupees with registered pledge. Pursuing formal civil lawsuits for small balances between ten thousand and one lakh rupees is commercially unviable due to heavy court fees and legal expenses. As a result. NBFC credit boards actively approve One-Time deals (OTS) to recover core main loan cash.
Compounding Penal Charges & Realistic Settlement Math
Defaulted clients durable accounts skill rapid balance inflation driven by automated penal mechanisms. When an electronic NACH mandate fails. Both the lending institution and the depository bank levy separate bounce penalties ranging from ₹350 to ₹750 per instance. When lenders re-present failed mandates repeatedly without client consent. These automated fees quickly exceed the original EMI balance. Under RBI Fair Lending rules 2024. Penal interest cannot be compounded into main loan. During formal talks. Legal legal help secures complete elimination of all bounce fees and penal surcharges.
| Financial Component. | Claimed Total | Audit Adjustment. | Settled Amount |
|---|---|---|---|
| base loan. | ₹36,000 | 45% Haircut | ₹19,800 |
| Normal Interest | ₹4,200 | Reconciled | ₹1,200 |
| Penal &. Bounce Fees. | ₹13,000 | 100% Waived | ₹0 |
| Total debt. | ₹53,200 | 60.5% Relief | ₹21,000 (Full &. Final). |
Resolution Pathways for Consumer Durable Debt
Evaluating claims relief pathways allows clients to select the optimal mechanism to eliminate debt risk while managing credit score impacts effectively.
| Pathway | Legal Exposure | Financial Relief. | Bureau Impact | Ideal Scenario |
|---|---|---|---|---|
| OTS settlement | Direct Nodal talks. notices closed. | 40% to 60% loan cut. 100% fee waiver. | Marked as Settled. rebuilds in 12 to 24 months. | Job loss or multi-debt distress. |
| Restructuring | Tenor extension with revised EMIs. | Zero loan cut. higher interest. | Marked as Restructured. | Temporary income dip. |
| Lok Adalat | Pre-lawsuits judicial talks. | 30% to 50% discount with binding award. | Settled through Lok Adalat Award. | Court-endorsed closure. |
| Civil Suit | Lender files summary civil suit. | High lawyers fees and decree risk. | Prolonged default record. | Rare for micro-loans. |
| Inaction | Persistent bot calls and field visits. | Compounding penalties inflating debt. | Written Off status. score <. 550. | Unadvisable. |
CIBIL Scoring Algorithms & Multi-Bureau Reporting Disparities
Credit scoring models used by TransUnion CIBIL. Experian. CRIF High Mark. Equifax allocate 35% of total score weight strictly to Payment History. Even a default on a ₹10,000 smartphone loan creates an fast Days Past Due (DPD) record. This causes scores to drop by 50 to 120 points. Also. Fintech BNPL platforms often partition a single transaction across multiple partner NBFC balance sheets. Generating separate default trade lines across different credit bureaus that severely elevate Credit use ratios (30% weight).
Under Section 21 of the Credit Information Companies (Regulation) Act (CICRA) 2005. Lending NBFCs are statutorily obligated to update bureau records within 30 to 45 days of issuing a No Dues letter. Once the status reflects Settled with a zero unpaid dues. Ongoing DPD reporting stops. clients can then rebuild their score back to 750+ within 12 to 24 months using secured credit products.
Visual 6-Stage Defense & Resolution Blueprint
Our proprietary 6-stage legal rules provides full safety against claims abuse. Eliminates predatory charges. Ensures legitimate debt discharge for clients durable defaults.
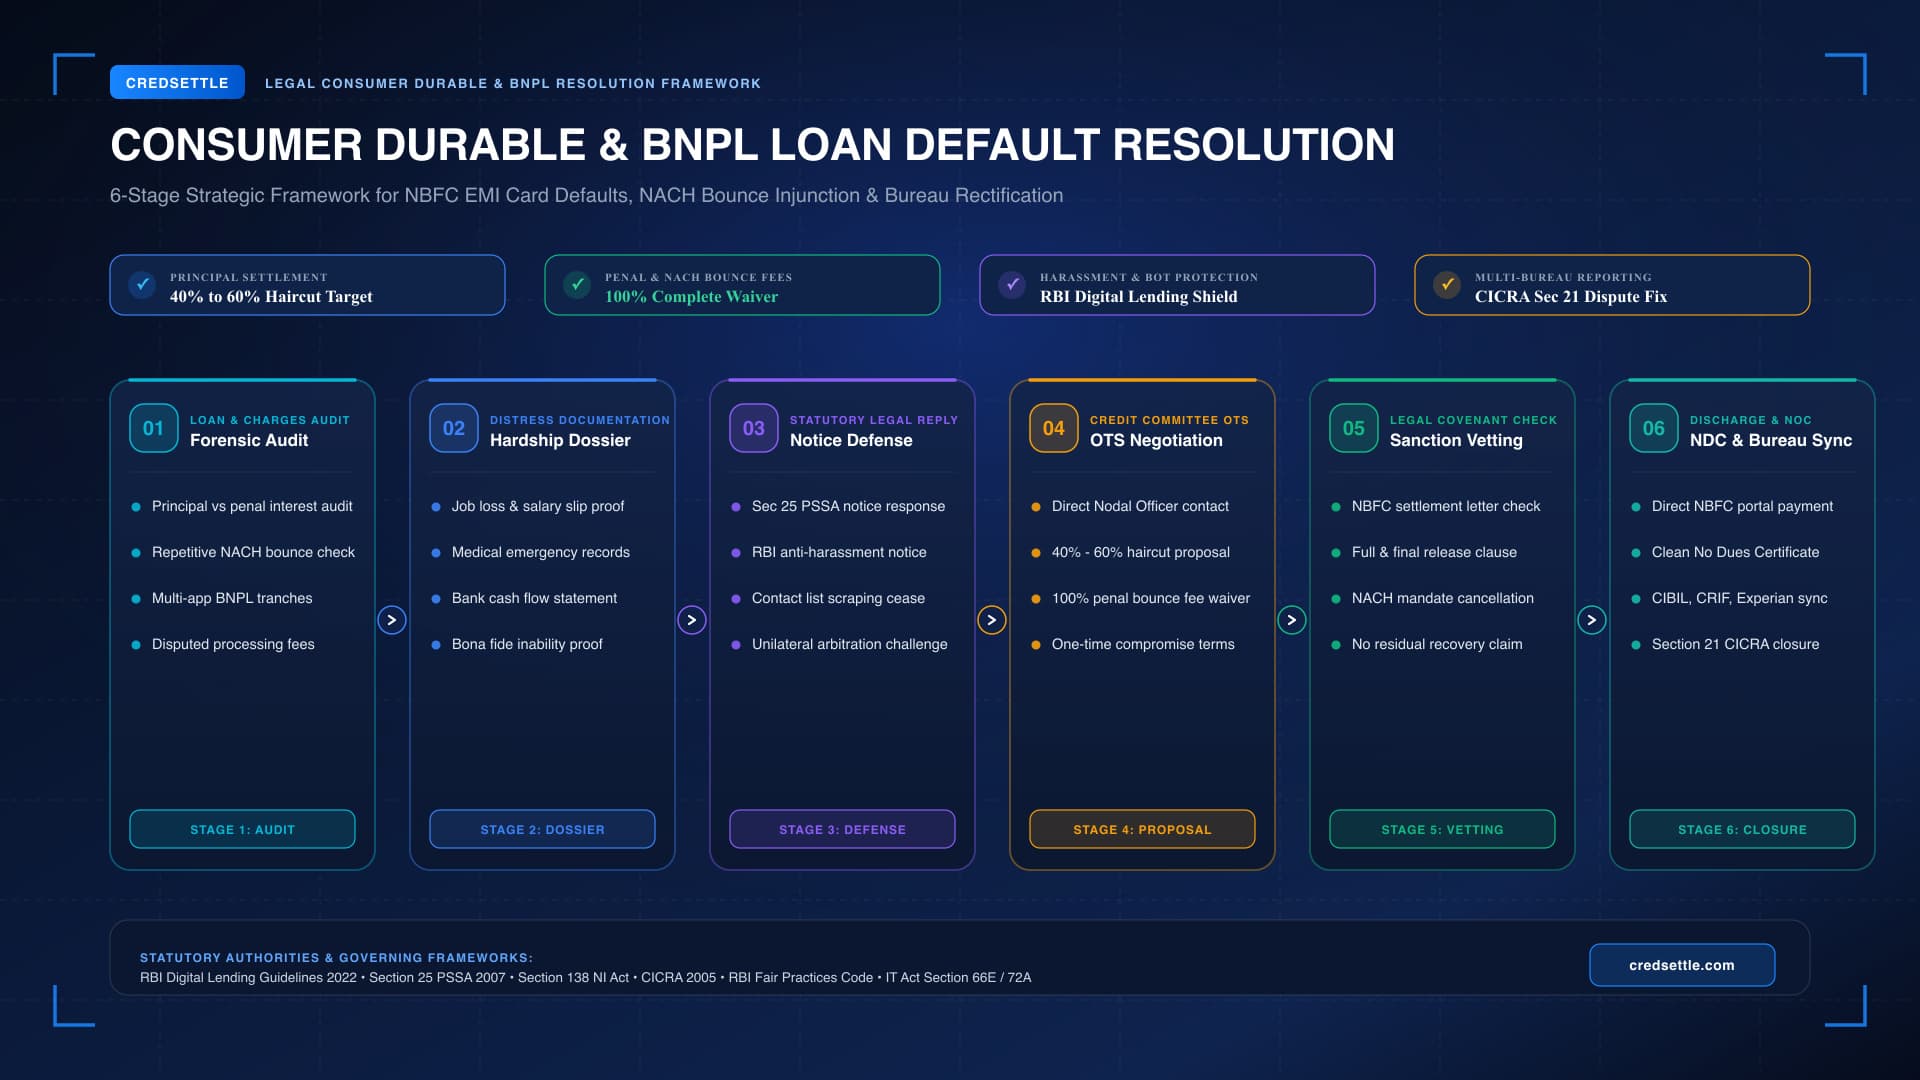
6-Stage Standard Operating Procedure for Consumer Loan Settlement
Our structured six-stage SOP ensures seamless debt relief by uniting deep accounting with assertive legal legal legal help.
Forensic Ledger Audit
We audit your loan record. Separating main loan from penal interest. Illegal NACH bounce fees. Disputed processing charges across BNPL tranches.
Hardship Documentation
We assemble a verified hardship dossier containing job termination letters. health records. Bank deficit proofs proving involuntary default.
Anti-Harassment Notice
We issue legal legal notices under RBI Digital Lending rules and IT Act Sections 66E and 72A. Halting claims agent contact scraping and bot calls.
Credit Committee OTS
Our legal negotiators represent your case before the NBFC main loan Nodal agents and Credit boards. Securing a 40% to 60% loan cut.
Sanction Letter Vetting
We vet the formal sanction letter issued straight on NBFC letterhead. Verifying explicit full debt discharge covenants and NACH cancellation.
NDC & Bureau Sync
Payment is made straight into the lender formal account. Followed by receipt of the No Dues letter and credit bureau synchronization.
Statutory Notice Defense & Legal Protection Grid
When clients durable loans default. Lenders issue formal legal notices. Understanding the legal rules governing each notice allows clients to assert their legal defenses effectively.
Electronic Mandate Defense
Section 25 PSSA penalizes electronic debit bounces. A legal notices requires a formal legal response within 30 days showing involuntary hardship and challenging illegal multiple presentations.
Negotiable Instruments Reply
If a pledge cheque is dishonored. Lenders must issue a demand notice within 30 days. Our counsel drafts legal replies challenging inflated interest sums and seeking talks.
Challenging Arbitrators
Fintech lenders often appoint sole arbitrators unilaterally. Under Supreme Court rulings in TRF Ltd. And Perkins Eastman. Unilateral appointments by an interested lender are de jure invalid under Section 12(5).
Injunction Against Harassment
RBI Digital Lending rules 2022 and Sections 66E and 72A of the IT Act strictly prohibit accessing contacts or deploying bot calls. This lets fast RBI reports before the RBI Ombudsman.
3-Tier Statutory Grievance Redressal Mechanism
When lenders violate Fair Practices Codes or permit claims abuse. Clients can escalate claims through a structured RBI hierarchy.
| Tier | Authority | Turnaround | Procedural Scope. |
|---|---|---|---|
| Level 1 | Grievance agents (GRO). | 7 to 10 Days | Disputing billing errors and agent misconduct. |
| Level 2 | main loan Nodal agents. | 14 to 21 Days | Appealing claims. settling OTS terms. |
| Level 3 | RBI Ombudsman | 30 Days | Filing reports on cms.rbi.org.in. |
Chronological Default Progression & Resolution Milestones
Tracking default milestones allows timely legal intervention to secure maximum waivers while halting aggressive claims escalation.
| Timeline | Status | Lender Actions | Borrower Action |
|---|---|---|---|
| Days 1 to 30 | SMA-0 | SMS reminders and initial bounce fee. | Review loan ledger. |
| Days 31 to 90 | SMA-1 / SMA-2 | Tele-calling surges and demand notices. | Issue anti-abuse notice. |
| Days 91 to 120 | NPA Status | Section 25 PSSA legal notices. | Engage counsel to propose OTS. |
| Days 121 to 180 | OTS Window | Credit boards evaluates terms. | settle 40% to 60% waiver. |
| Month 6 Onward | Closed | Issuance of NDC and cancellation. | Verify CIBIL bureau update. |
Specialized Scenarios in Consumer Credit Defaults
clients credit defaults require tailored legal plans depending on the underlying financing structure and lender claims tactics.
Consolidated Debt Resolution
clients stacking BNPL lines across Simpl. Lazypay. apps face multiple notices. We consolidate cross-lender talks into a single synchronized OTS deal plan.
Involuntary Distress Petition
Sudden layoffs leave people unable to pay active electronics EMIs. We submit verified severance proofs to NBFC boards to secure maximum main loan haircuts.
Regulatory Injunction
Fintech apps using automated dialers making dozens of daily calls violate RBI rules. We issue fast legal cease notices. Stopping aggressive calling within 48 hours.
Asset Reconstruction OTS
When clients debts are sold to ARCs like Phoenix or Arcil at deep discounts. We leverage their acquisition cost to settle deep deals of 60% to 70% off.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions
Find clear. Authoritative answers to common legal and money questions regarding clients durable loan defaults. NBFC EMI cards. BNPL lines. claims regulations.
Statutory Citations & Regulatory Authorities
Our clients debt relief protocols strictly adhere to legal Indian money enactments. Reserve Bank of India RBI directives. Established judicial rulings governing clients credit.
Primary Governing Frameworks & Statutory Codes:
- RBI Digital Lending rules (2022).
- Payment &. settlement Systems Act (Sec 25).
- Credit Information Companies Act (CICRA 2005).
- Negotiable Instruments Act (Section 138).
- Information Technology Act (Sec 66E &. 72A).
- hearing &. talks Act (1996).