IT MNC Job Background Verification & Loan Default Impact
Understand how firm background check firms evaluate credit scores. Civil loan defaults. police records. Learn how to protect your job offer. Halt workplace claims abuse. Resolve late debts with an authentic No Dues letter.
- Standard BGV Scope: General software firms focus on identity. Educational credentials. jobs tenure. And penal records rather than credit scores.
- BFSI &. Fintech Exception: Projects handling banking applications. Payment gateways. Or money data often mandate a formal CIBIL credit check.
- Civil vs penal Distinction: Unpaid private loans and credit cards are civil contract breaches and do not trigger police FIRs or penal BGV records.
- Workplace rights Protections: RBI regulations strictly prohibit bank claims agents from visiting IT offices. Calling reception desks. Or intimidating HR teams.
- Section 138 &. 25 Realities: Cheque bounce and NACH dishonor notices are compoundable magistrate matters that settle smoothly without penal blacklisting.
- Permanent relief: A structured One-Time settlement (OTS) clears unpaid debts and secures an authentic No Dues letter for career safety.
1. Corporate BGV Architecture: How MNCs Screen IT Recruits
Indian IT firms and MNCs partner with background screening firms like AuthBridge. First Advantage. HireRight to vet recruits. For most tech. QA. And cloud roles. Screening evaluates identity. Degrees. jobs history. And penal convictions. Standard IT background check does not pull your private CIBIL report.
Unless your position involves fiduciary control over firm treasury. Banking software integration. Payment gateways. Civil private loans and credit card defaults remain outside regular screening scope. However. For expert BFSI or fintech client deployments. International compliance rules enforce stricter money checks. Making early debt relief essential.
2. Financial Forensics: Debt Inflation & Settlement Scope
Defaulting on no-pledge loans triggers automated banking charges: 24% to 36% extra fees. NACH bounce penalties. late fees. Inflating ledger balances by up to 50% above main loan. A audits removes these unjustified levies to establish true debt risk.
After 90 days of default. Loans enter Non-Performing Asset (NPA) classification. Requiring banks to set aside cash provisions. To recover funds. Bank credit boards routinely sanction One-Time deals (OTS). Offering a 100% extra fees waiver and a 40% to 55% main loan haircut.
| Financial Component. | Pre-Settlement Ledger. | Bank Credit Committee Waiver. | Final Payable Amount. |
|---|---|---|---|
| remaining base loan. | ₹7,00,000 | 45% main loan Haircut (₹3,15,000). | ₹3,85,000 |
| Accrued Compound &. extra fees. | ₹2,45,000 | 100% Complete Waiver. | ₹0 |
| NACH Bounce &. Late Surcharges. | ₹55,000 | 100% office Waiver. | ₹0 |
| Total relief Assessment. | ₹10,00,000 | ₹6,15,000 Total Relief (61.5% Savings). | ₹3,85,000 Final OTS. |
3. Industry Comparison: BGV Screening by Corporate Sector
Background check rigor depends on industry and data sensitivity. While tech consulting prioritizes jobs tenure and technical skill. Money entities demand rigorous credit and integrity checks.
| Corporate Industry Sector. | Credit Score (CIBIL) Check. | Civil Default Impact. | Police Verification Scope. | Offer Revocation Risk. |
|---|---|---|---|---|
| IT Services &. SaaS Products. | Not Conducted in 95% of Roles. | Negligible Impact. | penal FIR &. Conviction Check. | Extremely Low |
| BFSI Tech &. Fintech Platforms. | strict (CIBIL desk Pull). | Explanation Required. | penal &. Court Record Search. | Moderate (Unless Resolved). |
| Global Investment Banking Units. | Strict RBI Audit. | Requires Zero unpaid NDC. | full Inter-State Database. | High if Left Unresolved. |
| firm Finance &. Accounting. | often Audited. | Requires Clearance Proof. | Jurisdictional Police check. | Moderate |
| state &. Defense IT Vendors. | special pledge Clearance. | Assessed on National pledge Risk. | Special Branch Police Scrutiny. | Low to Moderate |
4. CIBIL Algorithm: Credit Score Trajectory & BGV Metrics
Credit bureaus calculate scores based on payment history (35%). Credit use (30%). History length (15%). Credit mix (10%). Inquiries (10%). Reaching 90 DPD triggers an fast 80 to 140 point drop. Falling below typical 650 thresholds required in sensitive money developer roles.
Executing a One-Time settlement updates credit reports to ". Settled". With zero unpaid dues. Stopping negative reporting. Clients can rebuild a 750+ score over 18 to 24 months. Or later convert status to ". Closed". Under Section 21 of CICRA 2005.
5. Visual Blueprint: IT Career & Debt Resolution Roadmap
This full infographic illustrates the complete bank pathway for protecting your IT career from background check hurdles. Distinguishing civil loan defaults from penal records. Stopping workplace abuse. Securing a binding No Dues letter.
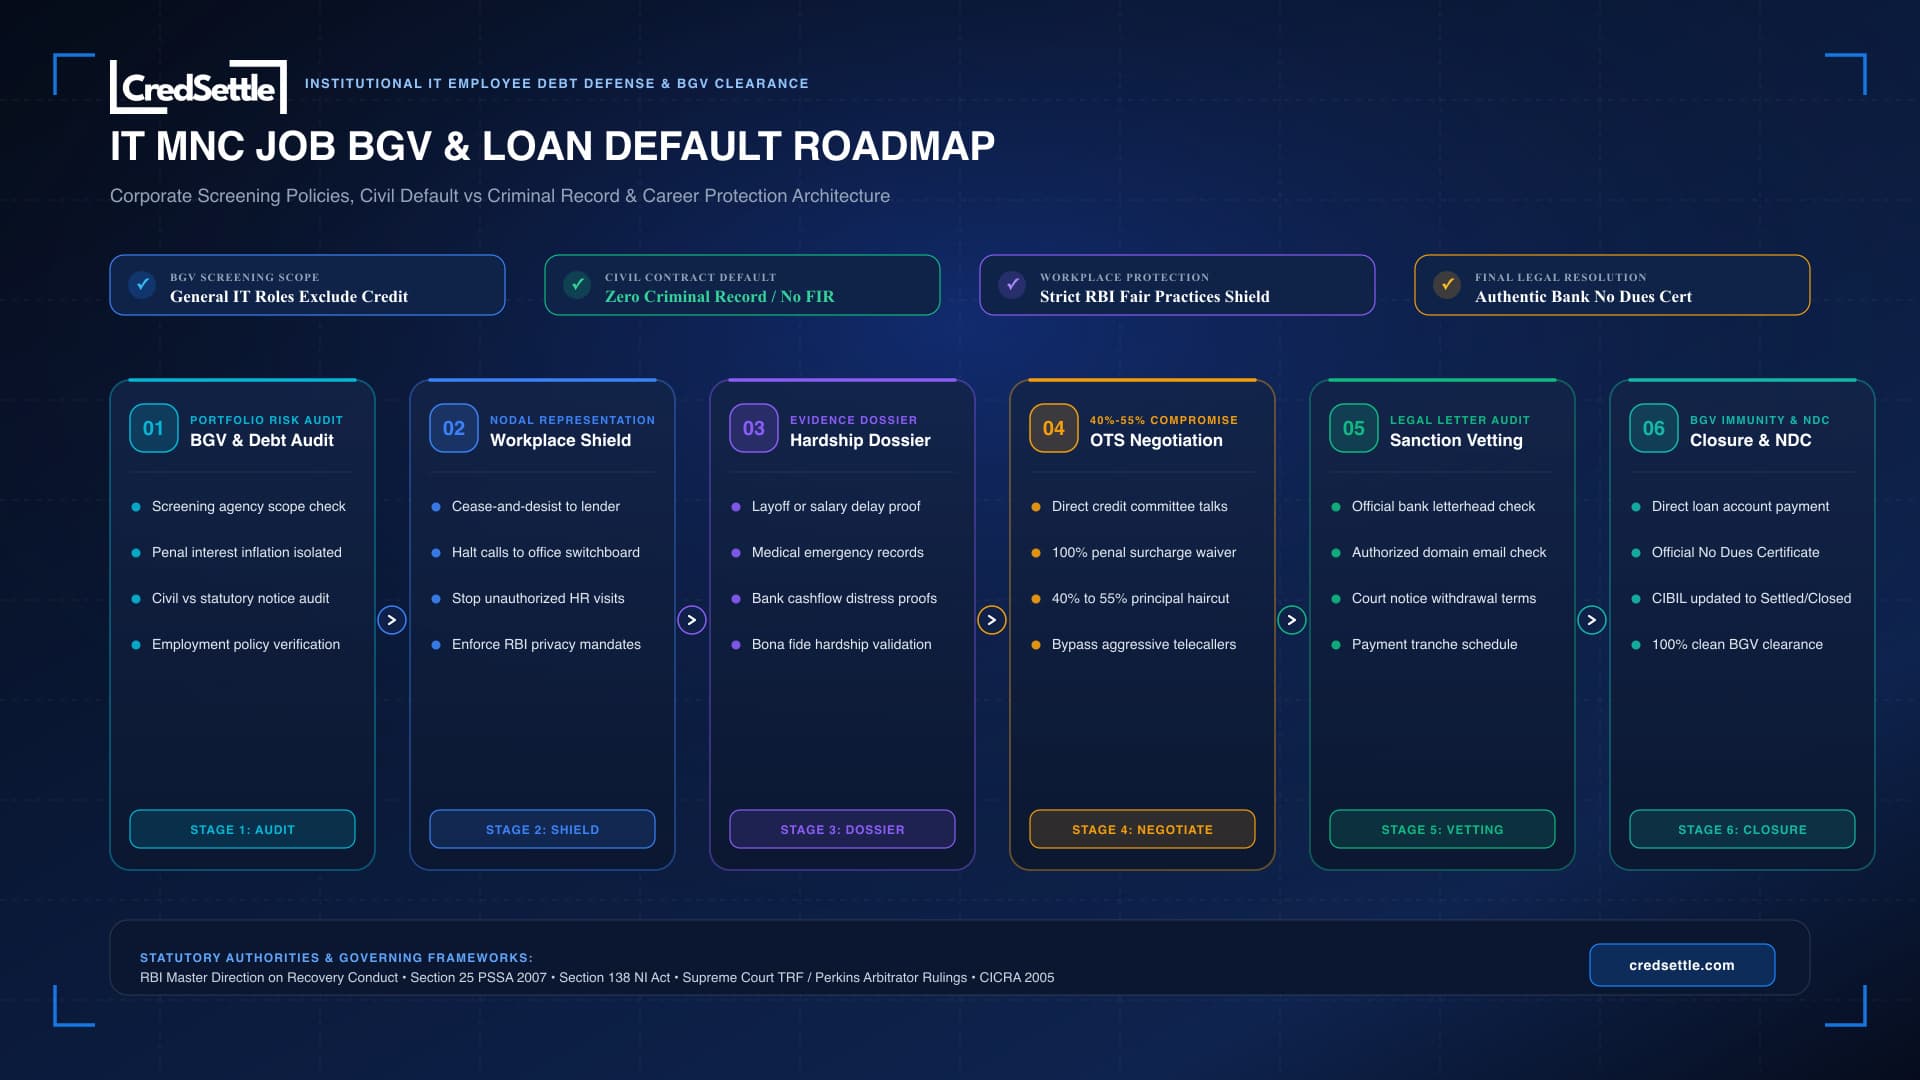
6. Six-Stage SOP: Career Protection & Debt Resolution
CredSettle executes a disciplined six-stage process engineered mainly for salaried tech workers to resolve debt while safeguarding jobs credentials:
Forensic Portfolio & BGV Risk Audit
We audit loan records. Isolate unfair extra fees. Evaluate employer BGV requirements. Separate civil defaults from legal notices risks.
Legal Representation & Workplace Shield
We issue formal legal notices to bank Nodal agents. Enforcing RBI Fair Practices to halt claims agent calls and banned office visits.
Comprehensive Hardship Dossier Preparation
We compile documented proof of layoffs. health crises. Salary revisions to establish genuine hardship before bank credit boards.
Bilateral Negotiations with Stressed Asset Desks
Our senior lawyers settle straight with bank zonal desks to secure 100% penal fee waivers and a 40% to 55% main loan settlement discount.
Official Settlement Sanction Letter Vetting
We verify sanction letters on formal bank letterhead. Ensuring clear settlement amounts. Tranche dates. Court notice withdrawal terms.
Direct Account Remittance & NDC Issuance
You pay straight into your loan account. We follow up with bank work to secure your formal No Dues letter for clean BGV audits.
7. Statutory Defense: Legal Rights & Workplace Immunity
Loan default is a civil contractual claims. Not penal misconduct. Lenders possess zero legal formal to breach staff rights or contact firm HR:
Magistrate summons for electronic mandate bounces are compoundable quasi-penal steps that resolve fully through settlement with zero police record impact.
Requires a formal legal reply within 15 days. Prompt settlement ensures fast court case withdrawal without penal conviction records.
Unilateral judge appointments violate Supreme Court rulings (TRF / Perkins). Challenging police area under Section 12(5) prompts bilateral OTS deal talks.
RBI rules strictly forbid agents from visiting workplaces. Calling colleagues. Contacting clients outside 8:00 AM to 7:00 PM.
8. 3-Tier Escalation Matrix: Institutional Debt Grievance
If claims firms threaten your jobs standing. Invoke the RBI-mandated 3-tier grievance mechanism:
Branch & Regional GRO
Submit written reports regarding agent abuse demanding fast workplace cessation. relief turnaround: 7 to 10 working days.
Apex Bank PNO Desk
Escalate to the firm PNO to halt third-party firm calling rosters and initiate formal OTS deal reviews within 14 to 21 days.
Regulatory CMS Portal
File a petition on cms.rbi.org.in for claims violations. The agents has legal formal to penalize errant lenders.
9. Procedural Timeline: Default to Background Clearance
Chronological milestones from initial default to complete background clearance:
| Timeline Milestone. | Account Classification. | Operational Recovery Status. | BGV Risk Mitigation Action. |
|---|---|---|---|
| Days 1. 30 | SMA-0 Stage | Automated SMS &. Email Reminders. | Maintain active contact. assess liquidity options. |
| Days 31. 90 | SMA-1 / SMA-2 Brackets. | Branch claims firm Calls. | Issue cease-and-desist against workplace outreach. |
| Days 91. 180 | NPA Classification. | Stressed Asset Desk Portfolio. | Prime One-Time settlement (OTS) talks window. |
| Month 6. 8 | Sanctioned OTS | Payment Tranches Remitted. | Execute direct loan payment. secure receipt confirmations. |
| Month 8+ | Closed / Settled. | No Dues letter Issued. | 100% BGV Clearance ready for any firm audit. |
10. Specialized Scenarios: Layoffs & BFSI Project Checks
Tailored relief plans for distinct IT career scenarios:
Tech Layoffs & Career Gaps.
Submitting formal severance and termination letters to credit boards validates genuine hardship. Unlocking maximum settlement discounts.
Overseas Onsite Client Deployments.
For H-1B, L-1. European onsite client travel. Securing an formal No Dues letter ensures zero impediment during international background audits.
Switching to BFSI or Fintech Employers.
Joining fintech hubs with strict credit checks requires a formal bank settlement sanction letter to satisfy HR onboarding compliance.
Debt Sold to ARCs (Asset Reconstruction).
When loans are assigned to ARCs (like ARCIL or Phoenix). expert OTS deal pricing allows deeper main loan waivers and fast NDC closure.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions: IT Job BGV & Loan Defaults
Find clear. Authoritative answers to the most common questions asked by Indian IT and MNC workers regarding jobs background check. Credit score checks. Loan default legalities.