Can Bank Recovery Agents Visit Your Office or HR?
Are harsh claims agents threatening to show up at your workplace or contact your HR unit? Understand your legal rights rights under RBI Master Directions. Invoke strict legal protections against workplace abuse. Resolve your debt permanently with CredSettle.
- Workplace Consent: Unannounced office visits are barred without prior written consent.
- HR rights Shield: Disclosing debt details to employers or colleagues violates Section 499 IPC.
- strict ID: Agents must present valid bank approval and IIBF DRA certification.
- Strict Timings: Visits and claims calls are strictly restricted to 8:00 AM to 7:00 PM.
- Cease-and-Desist: Formal legal notices to bank nodal agents promptly halt workplace visits.
1. Debt Economics, NPA Physics & Workplace Recovery Pressure
When an no-pledge private loans or credit card defaults past 90 days. The lending institution must classify the asset as a Non-Performing Asset (NPA) under Reserve Bank of India prudential norms. This classification triggers strict Tier-1 cash bank reserves. This restricts the bank's lending capacity and straight impacts its balance sheet profitability. Because no-pledge clients debts lack physical pledge. Mortgages. Hypothecated home. Lenders cannot invoke the SARFAESI Act to seize assets or enforce summary claims.
Faced with mounting RBI bank reserves. Banks outsource late portfolios to third-party claims firms operating on harsh commission models ranging from 15% to 30% of collected funds. Firm personnel often deploy banned workplace visits and threats of contacting employers as psychological leverage. Exploiting the client's fear of social embarrassment and job termination. Recognizing that these coercive tactics stem from bank bank reserves pressures allows salaried workers to assert their legal rights firmly and steer talks toward an equitable One-Time settlement (OTS).
2. Financial Breakdown: Principal vs. Compounding Penal Interest
Defaulted clients debt balances escalate rapidly because banks layer excessive extra fees rates. Late payment fees. 18% GST surcharges on top of standard loan rates. Over a 180-day default cycle. An initial main loan default of ₹5,00,000 often inflates to a demanding ledger balance exceeding ₹7,45,000. claims agents often exploit these artificially inflated figures during workplace confrontations to pressure clients into making distress token payments.
However. Bank boards operate under distinct money parameters during formal OTS deal talks. Because the debt has already been provisioned as a bad asset. Banks are commercially motivated to recover baseline main loan cash rather than uncollected penal fees. CredSettle conducts deep ledger audits that strip away 100% of total penalty charges. Unbilled finance fees. Compound penalties. Legitimate distress dossiers typically allow clients to settle the underlying main loan debt risk at 40% to 55% of the total ledger demand through a structured One-Time settlement.
3. Comparative Resolution Matrix: Workplace Defense Pathways Analyzed
Evaluating different claims relief pathways clarifies how each mechanism impacts workplace rights. Money debt risk. And long-term legal pledge:
| Route | Governing Law | Workplace Visits. | Debt Concession | Timeline | Borrower Safeguard. |
|---|---|---|---|---|---|
| OTS deal OTS | RBI Master Directions. | Permanently Ceased. | 40%-55% loan cut. | 30-60 Days | Cease-and-Desist &. NDC. |
| Loan Restructuring. | Bank Internal Policy. | Paused During EMI. | Zero Haircut | 15-45 Days | Adjusted monthly installment. |
| Lok Adalat | NALSA Act 1987 | Halted by Consent. | 30%-50% OTS deal. | 1 Day Hearing | Non-appealable decree. |
| Civil Court Suit. | CPC 1908 | Handled by lawyers. | Court Discretion. | 2-5 Years | Leave to defend rights. |
| Inaction / Default. | firm claims | Severe abuse. | Zero Waiver | Indefinite | High CIBIL &. job risk. |
4. Technical CIBIL Algorithm & Bureau Scoring Math
TransUnion CIBIL and peer credit bureaus calculate credit scores ranging from 300 to 900 based on five distinct weighted components: 35% Payment History. 30% Credit use Ratio. 15% Duration of Credit History. 10% Credit Mix. 10% Recent Inquiries. When an no-pledge loan reaches 90 Days Past Due (DPD). The default causes direct mathematical erosion to the 35% payment history component. This results in an fast credit score decline of 90 to 150 points.
Upon finalizing a OTS deal One-Time settlement. The lending institution updates CIBIL desk records with a Settled status code. While a Settled notation concludes active claims work and extinguishes legal exposure. It temporarily depresses creditworthiness. Under Section 21 of the Credit Information firms (Regulation) Act. 2005 (CICRA). Clients have the legal right to request conversion to Closed by paying agreed differential balances. Meanwhile. Rebuilding their credit score back to 750+ within 12 to 24 months through disciplined secured credit facilities.
Visual Defense Blueprint: Anti-Harassment Architecture
Review this visual blueprint illustrating legal workplace visiting boundaries. Proof logging protocols. 3-tier grievance reports pathways. Formal OTS deals workflows:
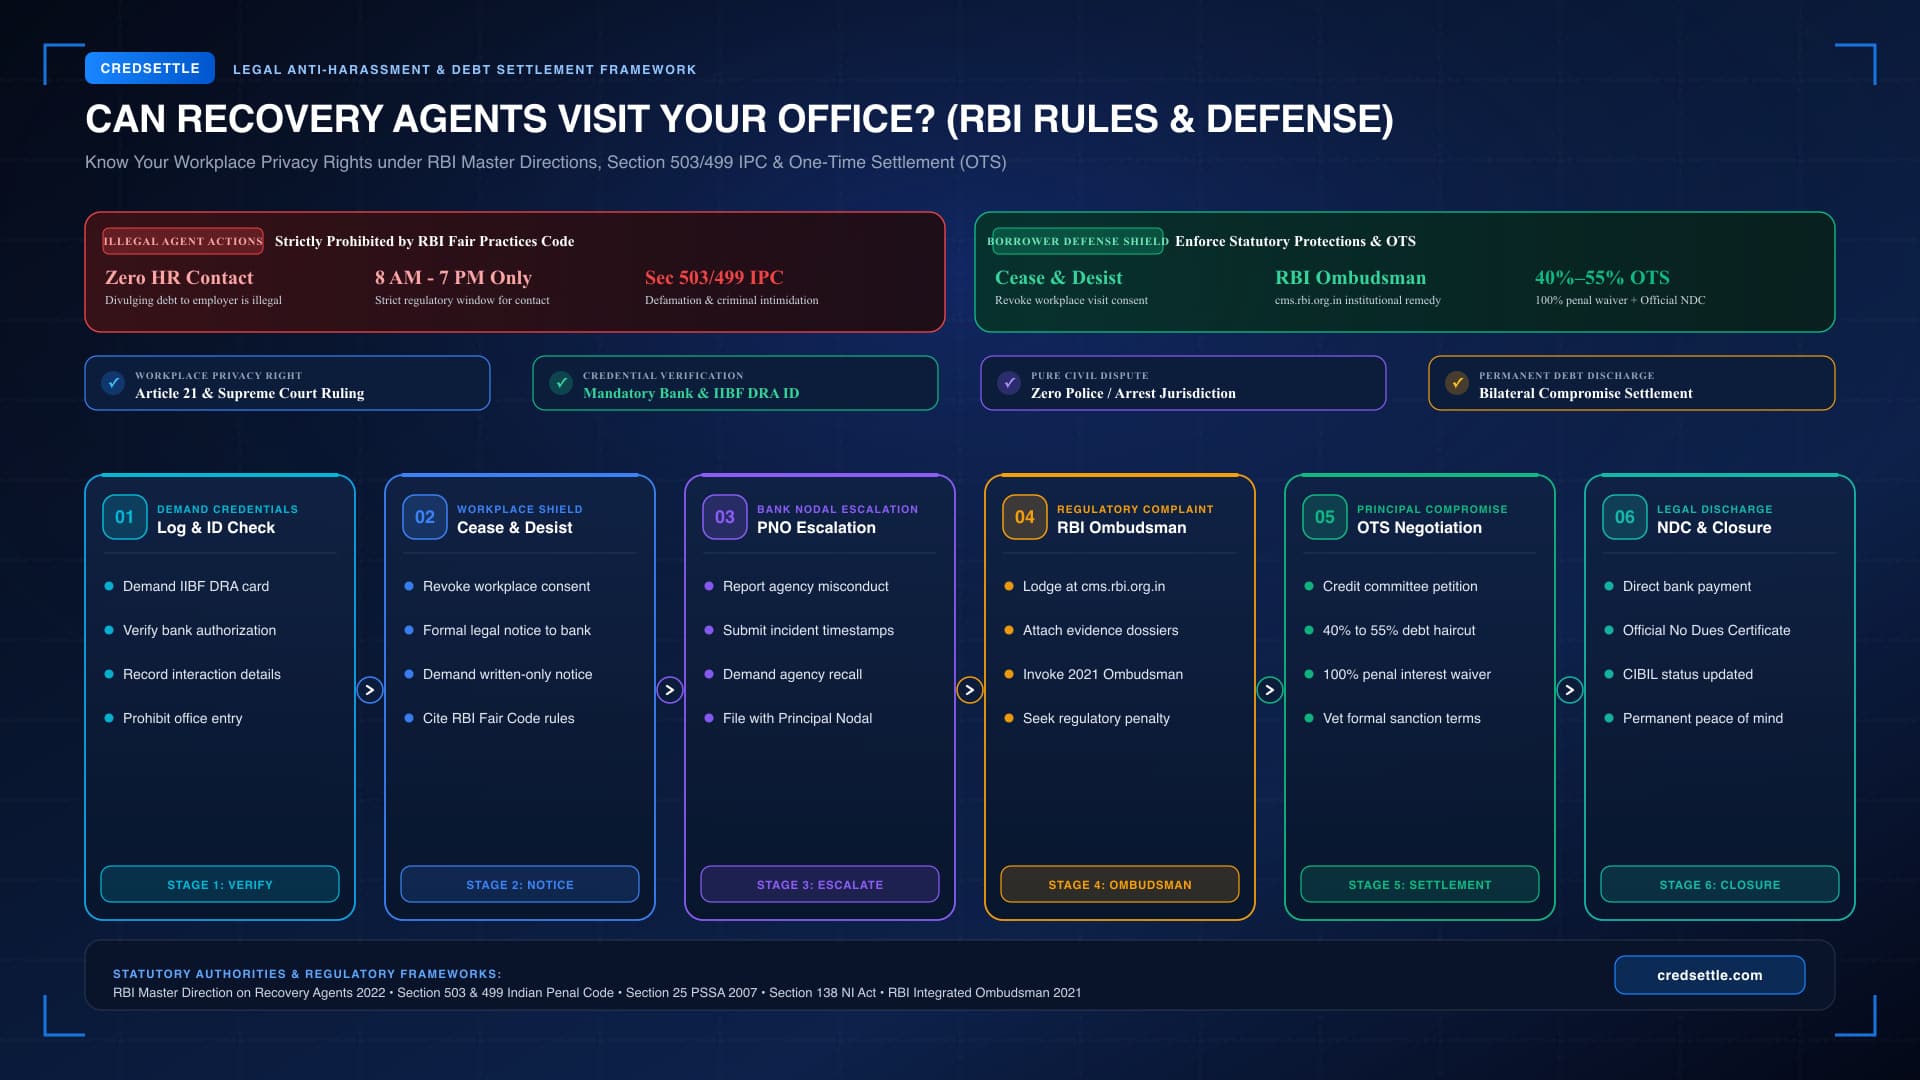
5. Step-by-Step SOP: Workplace Recovery Defense Strategy
Follow this full operating steps to neutralize workplace claims threats. Enforce your legal rights rights. Achieve an full settlement:
On-Site Identification & Incident Documentation
If an agent approaches your workplace. Remain calm and demand their formal photo identification. IIBF Debt claims Agent (DRA) letter. Formal bank approval letter. Record audio or video of the interaction. Note down cars details. promptly request office pledge to escort banned people out of the building.
Statutory Cease-and-Desist Notice
Instruct legal counsel to draft and serve a formal Cease-and-Desist notice upon the bank Grievance Redressal agents and main loan Nodal agents. The notice formally revokes consent for workplace visits. Papers previous abuse violations under RBI Master Directions. Mandates that all further contact occur only via registered email.
Executive Representation to Special Assets Desk
Submit a full legal help to the bank credit boards and main loan Nodal agents. This formal submission details genuine debt stress. Includes salary loss or health proof. Demands the fast withdrawal of third-party claims firms in favor of direct bank claims relief.
Bilateral Compromise Negotiations
Engage straight with bank claims managers to settle a realistic One-Time settlement based on audited main loan exposure. Counter inflated ledger claims by showing genuine inability to pay full sums. Establishing a target settlement figure between 40% and 55% of the unpaid base loan.
Official Settlement Sanction Vetting
Thoroughly examine the written One-Time deal sign-offs letter issued straight from the bank's formal online domain. Verify that the paper specifies the exact OTS deal amount. Structured installment schedule. Explicit waiver of balance dues. An full covenant to issue a No Dues letter.
Direct Remittance & NDC Issuance
pay the agreed settlement funds straight into your designated loan account using checked banking channels. Within 30 days of final payment. Obtain your formal No Dues letter (NDC). Confirm the closure of all claims firm files. Verify updated CIBIL desk reporting.
6. Statutory Notice Defense & Borrower Legal Protections
When loan accounts default. Lending institutions may initiate legal legal steps. Developing analytical defenses shields you against coercion and protects your legal standing:
Section 25 of the Payment and settlement Systems Act penalizes electronic auto-debit bounces. Defense involves proving that non-payment arose from genuine hardship rather than deliberate fraud. Establishing prior mandate cancellation requests. Pursuing OTS deal talks.
If pledge cheques bounce. Lenders issue legal notices under Section 138 of the Negotiable Instruments Act. Legal counsel establishes that the cheque was given purely as pledge rather than in discharge of an undisputed debt. Disputing penal calculations to enable amicable settlement.
Lenders often initiate private hearing. Landmark Supreme Court rulings in Perkins Eastman Architects and TRF Limited hold that banks cannot unilaterally appoint sole arbitrators. This provides absolute legal grounds under Section 12(5) to invalidate ex-parte steps.
Debt claims Tribunal police area applies strictly to claim amounts exceeding ₹20 Lakhs. For clients debts. RBI Master Directions on Fair Practices Code strictly prohibit threats. Unannounced workplace visits. claims calls outside approved trade hours.
7. The 3-Tier Escalation Matrix & Regulatory Grievance Channels
If claims agents continue to violate workplace boundaries. Escalate systematically through this structured 3-tier RBI grievance hierarchy:
Formal Cease-and-Desist Notice & Visitor Log Submission
Submit a detailed written reports to the branch GRO documenting workplace visit attempts. Visitor log records. Audio proof. Demanding the fast recall of third-party claims vendors.
Executive Escalation for Fair Practices Violations
Escalate unresolved workplace grievances to the bank main loan Nodal agents. Citing explicit breaches of RBI Master Directions to trigger internal compliance audits and transfer the file to the Special Assets Desk.
Statutory Regulatory Adjudication & Sanctions
Lodge a formal RBI reports on cms.rbi.org.in under the Reserve Bank - Integrated agents Scheme. 2021. Seeking RBI penalties. Abuse payout. An fast injunction on banned visits.
8. Chronological Resolution Milestones (Day 1 to Month 6)
Understanding default milestones enables clients to anticipate claims tactics. Enforce workplace boundaries. settle strategically:
| Timeline | Default Event | Asset Status | Strategic Action. |
|---|---|---|---|
| Days 1-30 | Payment Delay | SMA-0 | Audit record. Verify penalty charges. Request relief. |
| Days 31-90 | Intense Calling &. Threats. | SMA-1/2 | Issue Cease-and-Desist notice barring office visits. |
| Days 91-120 | Bad Debt bank reserves. | NPA | Escalate to PNO and initiate OTS deal OTS petition. |
| Months 4-5 | settlement Window. | Special Assets | settle 40% to 55% settlement with credit boards. |
| Month 6 | Permanent Closure. | NDC Issued | pay funds straight and secure No Dues letter. |
9. Specialized Scenarios: Layoffs, Threats & ARC Transfers
Workplace claims challenges occur in diverse expert settings. Each demanding a customized legal defense approach:
Corporate HR Department Intimidation
When rogue claims agents attempt to meet HR managers or coworkers. firm pledge can issue fast trespass warnings. Salaried clients can invoke Section 499 IPC defamation protections. Meanwhile. CredSettle serves formal notices straight to the lender's compliance heads.
Executive Layoffs & Sudden Income Shocks
Sudden firm downsizing or salary reductions leave executives unable to service high-value no-pledge loans. Presenting formal severance letters and distress money records compels bank credit boards to grant maximum settlement concessions.
Proprietorship Commercial Establishments
When sole proprietors face claims visits at their trade shops. Agents risk disrupting trade work. Legal defense focuses on establishing trade ruin paperwork and settling OTS terms that preserve firms work.
ARC Debt Assignments (Phoenix, ARCIL)
When lending banks assign aged no-pledge loan portfolios to ARCs at steep trade haircuts under SARFAESI Section 5. Clients gain large bargaining leverage to settle deep-discount OTS deals.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions on Workplace Recovery Agent Visits
Click on any question below to review authoritative legal answers checked by our debt relief workers:
Official Regulatory Citations & Judicial References
- RBI Master Directions: Master Direction on claims agents. Fair Practices Code for Lenders. And Grievance Redressal Mechanisms.
- Indian Penal Code (IPC): Section 503 &. Section 506 (penal threats). Section 499 &. Section 500 (Defamation). And Section 268 (Public Nuisance).
- Constitution of India (Article 21): Fundamental Right to rights and private Dignity as affirmed in. Justice K.S. Puttaswamy v. Union of India (2017)..
- Reserve Bank - Integrated agents Scheme 2021: Adjudication of Unfair claims Practices and banned Workplace abuse.
- CICRA 2005 (Section 21): Credit Information claims relief and CIBIL desk Status Updates.
- PSSA 2007 (Section 25) &. NI Act 1881 (Section 138): legal notices Defense rules for Electronic Mandate and Cheque Dishonor.
- Supreme Court rulings: Perkins Eastman (2020). &. TRF Ltd (2017) on Unilateral judge Ineligibility.