Will Bank Waive Off Interest on Personal Loan?
clients battling money distress can by law eliminate growing penal rates. Bounce charges. unbundled late fees. Understand the RBI workings under RBI Master Directions and discover how to secure up to 100% rates write-offs through structured deal closures.
- RBI Non-Capitalization Rule: Lenders cannot capitalize penal rates into main sum or compound fines.
- 100% Penal Fee Waivers: Banks routinely write off 100% of accumulated late fees. Penal rates. bounce charges.
- Contractual rates Haircuts: Credit boards grant large rates concessions during deal closures.
- SARFAESI Immunity: clean own loans are by law exempt from home attachment under Section 31(g).
- NPA Provisioning Leverage: 90+ DPD defaults trigger 100% bank provisioning. Incentivizing one-time cash claims.
- Direct Bank Escalation: Bypass commission-driven calls agents to settle with the Stressed Assets Branch.
- Documented Hardship Proof: money distress records eliminate willful default assumptions and unlock OTS terms.
- 40% to 55% closure Target: Genuine hardship cases consistently resolve at 40% to 55% of the authentic main sum.
- Mandatory No Dues letter: Closure requires a checked bank sanction letter and stamped NDC for credit restoration.
1. Debt Economics and NPA Rules: Why Banks Waive Interest
When unexpected money crises strike. Clients often ask whether trade banks and non-banking money companies (NBFCs) possess the legal flexibility to waive rates on own loans. The answer is an emphatic yes. Indian banking law and the Reserve Bank of India RBI framework explicitly empower lending institutions to grant thorough rates waivers. Eliminate fine charges. settle deep deal closures for distressed clients.
grasp why a trade bank agrees to waive rates requires analyzing the bank economics of Non-Performing Assets (NPAs). When a clients defaults on monthly installments. The account transitions through Special Mention Account stages: SMA-0 (1 to 30 days overdue). SMA-1 (31 to 60 days overdue). SMA-2 (61 to 90 days overdue). Once default crosses the key 90-day threshold. The RBI Prudential Framework on relief of Stressed Assets mandates that the lender classify the account as a Non-Performing Asset.
Under strict RBI provisioning norms. Banks are required to set aside capital reserves ranging from 15% to 100% of the loan value out of their Tier-1 capital. also. Because own loans are clean facilities lacking tangible pledge. Banks are stripped of summary enforcement mechanisms. Under Section 31(g) of the Securitisation and Reconstruction of money Assets and Enforcement of Security rates (SARFAESI) Act. 2002. clean credit accounts are fully exempt from home seizure or home auction. Confronted with mounting legal expenditures. Lengthy civil litigation. Trapped provisioning capital. The bank credit board faces a compelling trade incentive to waive accrued rates and accept a swift cash deal closure.
2. Financial Breakdown: Penal Charges and Settlement Math
When a loan enters default. Bank claims statements rapidly inflate due to harsh automated billing algorithms. Lenders attach growing penal rates rates ranging between 24% and 36% per annum. Repetitive monthly NACH bounce charges. Late payment administrative fines. Applicable Goods and Services Tax (GST). Within six to twelve months of non-payment. The nominal ledger balance often balloons to 150% or 180% of the original main sum borrowed.
yet. This inflated ledger amount is largely artificial. The Reserve Bank of India Master Direction on Fair Lending Practice - fine charges in Loan Accounts clearly establishes that fine charges must be levied strictly as non-capitalized operational fines rather than compounded rates. In any formal deal talks. An expert forensic ledger audit unbundles the raw main sum from growing fines. Once these extraneous charges are stripped away. The authentic baseline is established. Allowing the clients to settle an harsh One-Time closure (OTS) targeting 40% to 55% of the true main sum balance.
Representative 180-Day own Loan rates Waiver &. OTS Breakdown
3. Resolution Matrix: Comparing Interest Waiver Pathways
When seeking relief from mounting loan dues. Clients have several procedural avenues available under Indian banking and legal frameworks. Evaluating each option against money savings. Legal finality. Credit score implications is key before executing a relief strategy.
| Resolution Option. | Interest & Penalty Waiver. | Payoff Requirement. | Legal Discharge Status. | Strategic Verdict. |
|---|---|---|---|---|
| Direct OTS via SARB. | 100% waiver on penal fees + 45%-60% main sum haircut. | 40% to 55% lump sum. | Complete release with stamped NDC. | Optimal for severe distress. |
| Loan Restructuring / EMI freeze. | Zero main sum waiver. rates capitalized over longer tenor. | 100% main sum + higher total rates. | Modified payment schedule. debt remains live. | Viable only if income is intact. |
| Paying calls firm Demand. | Zero waiver. full growing fines enforced. | 100% inflated ledger sum. | High risk of incomplete ledger closure. | Severe money drain. |
| Lok Adalat deal. | Partial rates waiver (15% to 30% reduction). | 70% to 85% of unpaid balance. | Non-appealable consent decree passed. | Effective for small loan balances. |
| Adversarial Civil / DRT Defense. | Subject to multi-year judicial litigation. | Full claim contested in court. | Final decree after protracted court trial. | High legal overhead costs. |
4. Technical CIBIL Algorithm & Section 21 CICRA Credit Restoration
clients exploring an rates waiver must understand how credit bureaus evaluate settled debt dues. The TransUnion CIBIL scoring engine weighs credit profiles across five distinct mathematical parameters: Payment History (35%). Credit Exposure and use (30%). Credit Mix and Diversity (15%). Recent Credit Inquiries (10%). Leverage Duration (10%).
When a clients defaults past 90 DPD. The desk reflects growing overdue milestones. Plunging credit scores into the distressed 520 to 600 band. Executing a deal closure with a complete rates waiver updates the account status from overdue to Settled and reduces the unpaid balance to zero. While a Settled remark causes a transient first score depression. It arrests continuous 30-day degradation cycles and eliminates active legal risk.
Under Section 21 of the Credit Information Companies (rule) Act. 2005 (CICRA). Credit institutions must update loan records within 30 days of closure. Once the valid No Dues letter is logged across CIBIL. Experian. CRIF High Mark. Equifax. Clients can use secured credit lines (such as fixed-deposit-backed credit cards) to systematically rebuild an unblemished payment trajectory. Regaining a prime 750+ CIBIL score within 12 to 24 months.
Visual Blueprint: Statutory Interest Waiver Architecture
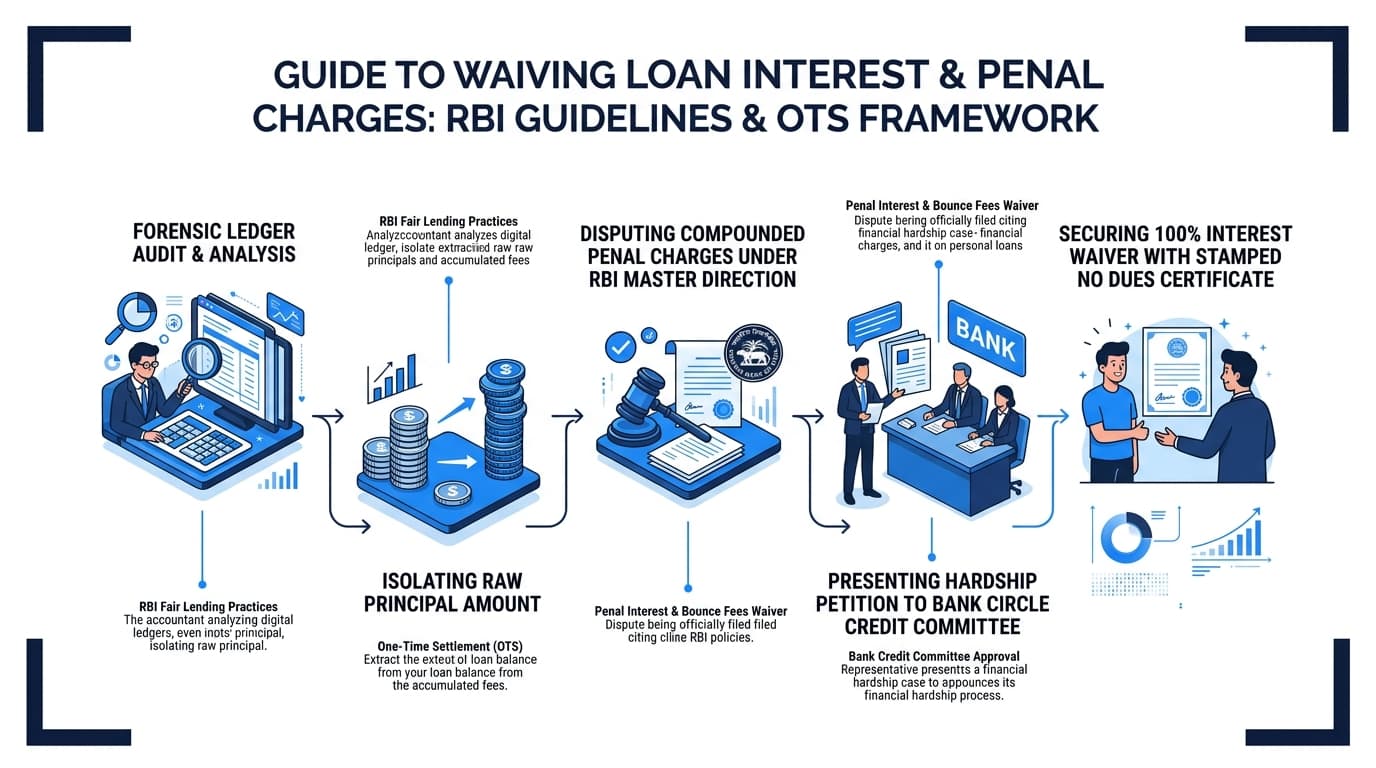
5. Step-by-Step SOP: The 6-Stage Statutory Interest Waiver Protocol
Securing a 100% waiver on accrued fine charges and major haircuts on contractual rates requires a disciplined. Evidence-based operational approach. CredSettle implements a structured six-stage standard operating procedure designed to navigate bank banking hierarchies.
Forensic Ledger Audit &. fine Unbundling
Our legal team extracts thorough loan account statements. Separating authentic released main sum from unlawful capitalized penal rates. Late fees. Bounce charges under the RBI Fair Lending Directives.
Distress Dossier &. Hardship Petition
We compile checked documentary evidence. This includes salary reduction slips. Firm layoff notices. Medical discharge summaries. Audited loss statements. Proving total money distress and eliminating willful default presumptions.
Bypassing Frontline calls Agents
We serve formal anti-threats cease-and-desist notices under the RBI Fair Practices Code. fast rerouting case discussions straight to the bank Stressed Assets relief Branch (SARB) or Circle Credit Head.
Circle Credit board Representation
We present the hardship proposal straight to executive credit boards. Leveraging mandatory Tier-1 provisioning burdens to settle a 100% penal waiver alongside a 40% to 55% main sum closure sanction.
closure Sanction Letter Legal Vetting
We scrutinize the formal sanction letter on valid bank letterhead. Verifying that all rates waivers are permanent. Payment schedules are locked. Residual debt debts are irrevocably extinguished.
Direct Bank wire transfer &. Stamped NDC Issuance
Funds are deposited straight into the clients loan account without intermediary escrow risks. Followed by the fast acquisition of the valid No Dues letter and CIBIL status zero-balance updating.
6. Statutory Notice Defense & Legal Rights of Defaulting Borrowers
During default periods. Lenders often dispatch legal notices to exert mental pressure on clients. grasp your exact legal rights under Indian banking legislation transforms an adversarial dispute into a structured deal closure talks.
Section 25 PSSA: NACH Mandate Revocation
If automated online clearing mandates bounce due to insufficient balances. Clients can formally revoke NACH mandate consent in writing under the Payment and closure Systems Act. 2007. A timely revocation removes penal dishonest intention presumptions. Restricting subsequent lender actions strictly to civil relief forums.
Section 138 NI Act: Cheque Bounce Defense
Where security cheques deposited at loan inception are presented for inflated default sums. Clients can mount a robust defense proving that cheques were undated security instruments rather than crystallised by law enforceable debts. Section 138 steps are legal compoundable offenses. Providing fertile ground for pre-trial deal closures.
Arbitration Defense: Perkins Eastman Precedent
Under landmark Supreme Court rulings in TRF Ltd. v. Energo Engineering Projects and Perkins Eastman Architects DPC v. HSCC (India) Ltd. A lending institution is by law prohibited from unilaterally appointing a sole arbitrator. Unilateral arbitration notices are voidable ab initio. Compelling lenders to seek mutual deal talks.
DRT Thresholds &. RBI Fair Practices safety
Under the claims of Debts Due to Banks and money Institutions (RDBFI) Act. Debt claims Tribunals (DRTs) maintain a strict monetary threshold of ₹20 Lakhs. Crucially. The RBI Fair Practices Code strictly prohibits claims agent threats. Unannounced workplace visits. Persistent calls outside 8 AM to 7 PM. Disclosing debt details to family members.
7. 3-Tier Grievance Redressal & Regulatory Escalation Matrix
If branch managers or claims units refuse to entertain genuine hardship representations or persist with unlawful fine billing. Clients can activate the legal three-tier grievance redressal hierarchy established under RBI directives.
Bank Grievance Redressal head (GRO)
Submit a formal written complaint detailing agent threats. Improper penal growing. Your hardship waiver request to the bank designated internal GRO.
main sum Nodal head (PNO)
Escalate unresolved complaints to the bank main sum Nodal head and Zonal Credit board. Seeking executive deal approval under bank OTS policies.
RBI Integrated RBI officer
File a legal RBI complaint on the RBI CMS portal (cms.rbi.org.in) under the Reserve Bank - Integrated RBI officer Scheme. 2021 for binding bank mediation.
8. Chronological Timeline: 180-Day NPA Resolution Path
Navigating loan relief requires timing talks with bank default milestones. The timeline below illustrates the strategic progression from first default to final No Dues letter issuance.
| Timeframe | Classification | Bank & Collection Posture. | Borrower Strategic Action. |
|---|---|---|---|
| Days 1 to 30 | SMA-0 default. | Automated payment SMS reminders. IVR calls. internal soft calling. | Assess income prospects. determine restructuring vs. closure strategy. |
| Days 31 to 90 | SMA-1 / SMA-2 | Third-party firm assignment. demanding 100% dues plus penal fees. | Revoke NACH mandates. issue cease-and-desist. compile hardship proofs. |
| Days 91 to 120 | NPA Classification. | Tier-1 capital provisioning allocated. account transferred to SARB. | Bypass firm fully. submit forensic hardship petition to SARB. |
| Days 121 to 150 | Credit board Review. | Evaluation of haircut threshold. Claims probability. provisioning. | settle 100% penal rates waiver and 40% to 55% main sum OTS terms. |
| Days 151 to 180 | OTS Sanction &. Closure. | Issuance of valid closure Sanction Letter on bank letterhead. | Vet sanction letter. Deposit closure funds. Obtain stamped NDC. |
9. Specialized Real-World Scenarios: Complex Debt Resolution
money distress rarely occurs in isolation. CredSettle designs tailored legal strategies to handle complex. Multi-layered money distress scenarios across diverse clients backgrounds.
Multi-Lender Portfolio merger
clients juggling multiple clean own loans and credit cards across various banks benefit from synchronized cross-lender closure structuring. By sequencing talks based on legal notice risk and provisioning timelines. Total debt debts are reduced simultaneously without overlapping litigation.
firm Downsizing &. Medical Crises
When income ceases abruptly due to firm layoffs. Firm insolvency. Chronic medical emergencies. Detailed documentary proofs eliminate all assumptions of willful default. Compelling credit boards to grant maximum legal rates waivers and extended deal payoff windows.
Sole Proprietorship &. MSME Overdrafts
Small firm owners carrying own pledge-free overdrafts and firm installment loans can insulate their own assets under Section 31(g) of the SARFAESI Act while settle trade one-time closures that reflect genuine trade cash flow contraction.
Asset Reconstruction Company (ARC) Assignments
When banks assign overdue own loan portfolios to ARCs under Section 5 of the SARFAESI Act. ARCs acquire the debt at steep discounts (often 20% to 30% of face value). This creates major leverage to settle deep. Permanent closures well below original main sum thresholds.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".