Bank Demanding Full Payment for Loan Closure? (How to Settle)
When third-party collection firms demand 100% full payment. They are using commission-driven pressure scripts. Learn how to bypass collection agents. Invoke RBI OTS deals norms straight with bank leadership. Settle for 40% to 55%.
- Zero Settlement formal in Collection firms: collection agents operate on commission models and lack legal formal to sanction waivers. Their 100% demand is merely a tactical pressure script.
- Right to Bypass Frontline Agents: clients have the RBI right under RBI Master Directions to settle straight with the bank\'s Stressed Assets relief Branch (SARB) or Circle Head.
- 100% Bank Provisioning on NPAs: Once a overdue loan crosses 90 days into NPA status. Banks set aside up to 100% provisions from cash reserves. Making a cash OTS commercially attractive.
- Isolating True main loan: deep ledger audits unbundle illegal compounding penalty charges and late fees. Anchoring OTS deal talks strictly around the base main loan debt.
- Documented debt stress Dossier: Evidentiary hardship proofs (job loss. Trade decline, medical emergencies) eliminate willful default assumptions and trigger credit boards review.
- Realistic 40% to 55% OTS Target: Distressed clients consistently secure a 40% to 55% main loan settlement with a 100% waiver of total penal interest.
- SARFAESI Immunity on no-collateral Loans: Under Section 31(g) of the SARFAESI Act. No-collateral private loans and credit cards cannot be subjected to property attachment or auction.
- No Dues letter (NDC): Payments must only be remitted against an formal sanction letter. Followed by a stamped NDC to restore your credit record under Section 21 CICRA.
1. Debt Economics & NPA Dynamics: Why Banks Settle
When a client faces money breaks and misses loan installments. The account is outside to third-party collection firms. These firms earn high commission percentages on extracted recoveries and have zero formal to approve waivers. As a result, their agents use standardized scripts demanding 100% full payment plus penalties. Threatening legal action to maximize collection pressure.
In reality, RBI prudential norms dictate that loans overdue past 90 days transition from Special Mention Accounts (SMA-0/1/2) into Non-Performing Assets (NPAs). Once an account becomes an NPA. The bank must set aside 15% to 100% cash provisioning from its Tier-1 reserves. For no-collateral loans exempt from property attachment under Section 31(g) of the SARFAESI Act. Civil lawsuits is costly and slow. Bank credit boards routinely prefer recovering 40% to 55% via a One-Time Settlement (OTS) to release locked cash reserves promptly.
2. Financial Breakdown: Principal vs. Penal Inflation
collection demands often inflate the original debt by 40% to 70% due to compounded overdue interest. 24%-36% penalty charges, bounce fees. collection costs. Under RBI Fair Lending Practice norms. Lenders cannot capitalize penalty charges into main loan. A audits isolates the authentic base loan to settle realistic settlement figures.
Representative 180-Day NPA Settlement Calculation
3. Resolution Matrix: Evaluating Your Debt Options
| Pathway | Financial Impact. | Legal Finality | CIBIL Trajectory. | Suitability |
|---|---|---|---|---|
| Direct OTS via SARB. | 40% to 55% of main loan. 100% penal waiver. | Permanent discharge with stamped NDC. | Status: Settled. rebuildable to 750+ in 12-24 mos. | Recommended for hardship. |
| Paying 100% to firm. | 100% main loan + full compounded penalties. | Risk of unrecorded payment disputes. | Marked Closed after severe money strain. | High money loss. |
| Restructuring | Zero discount. higher total interest. | Loan re-executed. default risk recurs. | Marked Restructured on bureau files. | Only if income is stable. |
| Civil / DRT lawsuits. | Heavy legal and court expenses. | Multi-year adversarial proceedings. | Reported as Suit Filed / Wilful Default. | High stress, high cost. |
| Lok Adalat | 15% to 30% modest waiver. | Non-appealable consent decree. | Marked Settled in Lok Adalat. | Small ticket loans. |
4. CIBIL Scoring & Section 21 CICRA Credit Restoration
Credit scores are calculated across Payment History (35%). Credit use (30%), Credit Mix (15%), Inquiries (10%). Leverage (10%). Defaulting past 90 DPD drops scores into the 520-600 range. Settling halts steady negative reporting and updates the balance to zero.
Under Section 21 of the Credit Information Companies (Regulation) Act. 2005 (CICRA), clients can submit their No Dues letter. Start fresh payment cycles with a secured credit card. Rebuild their score back to 750+ within 12 to 24 months.
Visual Blueprint: Countering Full Repayment Demands & RBI OTS
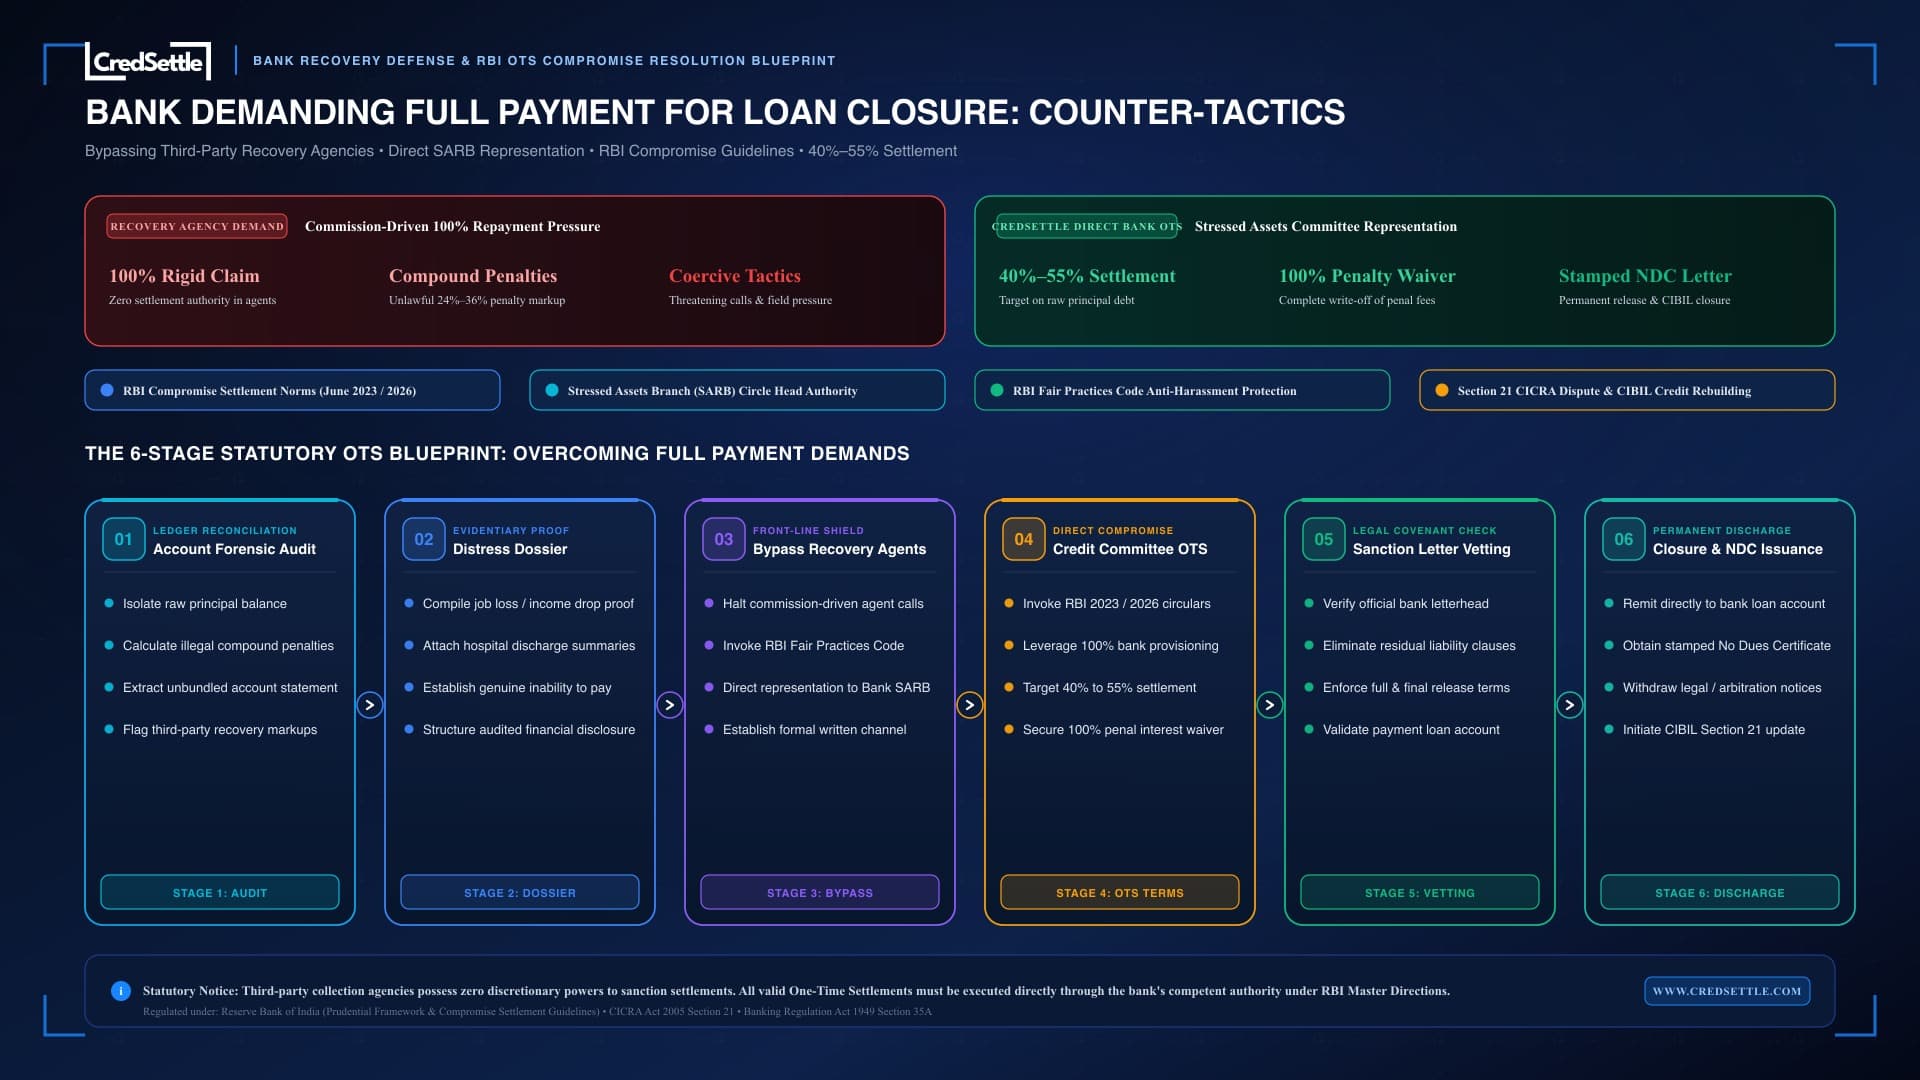
5. Step-by-Step SOP: The 6-Stage Statutory OTS Blueprint
Forensic Account Audit
Isolate raw main loan from compounded penalties. Establishing the baseline for OTS deal talks.
Hardship Dossier Compilation
Gather termination letters, audited trade losses. And medical summaries to prove genuine distress.
Bypassing Recovery Agents
Issue anti-abuse notices and escalate the case straight to the bank\'s Stressed Assets Branch (SARB).
Credit Committee Negotiations
Leverage bank provisioning to secure a 40% to 55% settlement with a 100% waiver of penalty charges.
Sanction Letter Vetting
Verify that the sanction letter confirms full release without residual debt risk clauses before payment.
Remittance & NDC Issuance
Deposit funds straight to the loan account. Secure the stamped No Dues letter, and update CIBIL.
6. Statutory Notice Defense & Borrower Rights
Section 25 PSSA: NACH Mandate Recall
clients can formally revoke NACH auto-debit consent in writing. Eliminating criminal default grounds and restricting the matter to civil debt settlement.
Section 138 NI Act: Cheque Bounce Defense
Security cheques cannot be presented for inflated penalty sums without an audited record. This lets a pre-trial compoundable settlement response.
Arbitration: Perkins Eastman Precedent
Supreme Court rulings (TRF Ltd. &. Perkins Eastman) prohibit banks from unilaterally appointing sole arbitrators, rendering unilateral proceedings voidable.
DRT Threshold & Fair Practices Code
DRT police area is restricted to debts exceeding ₹20 Lakhs. The RBI Fair Practices Code strictly prohibits workplace visits, threats, or calling relatives.
7. 3-Tier Grievance & Regulatory Escalation
Grievance Officer (GRO)
Submit a formal complaint against agent abuse requesting hardship settlement review.
Nodal Officer (PNO)
Escalate unresolved cases to the main loan Nodal Officer and Zonal Stressed Assets boards.
RBI Ombudsman
File a legal complaint on cms.rbi.org.in if the bank fails to resolve the matter in 30 days.
8. Chronological Timeline: 180-Day Resolution Path
| Timeline | Account Status | Bank / Agency Action. | Borrower Action |
|---|---|---|---|
| Days 1 to 30 | SMA-0 default. | Automated payment reminders and internal calls. | Assess restructuring vs settlement plan. |
| Days 31 to 90 | SMA-1 / SMA-2 | outside to collection firm. 100% demand calls. | Issue anti-abuse notice. compile hardship proofs. |
| Days 91 to 120 | NPA Classification. | Bank allocates provision. file moved to SARB. | Bypass firm. present hardship dossier to SARB. |
| Days 121 to 150 | boards Review. | Evaluation of hardship and settlement haircut. | settle 40% to 55% main loan OTS deal terms. |
| Days 151 to 180 | OTS Sanction &. Closure. | Issuance of Settlement Sanction Letter. | Vet sanction letter, pay funds, obtain stamped NDC. |
9. Specialized Real-World Scenarios
Multi-Lender Portfolios
Synchronized settlement plan across multiple lenders. Prioritizing accounts by notice risk.
Layoffs & Medical Crises
Evidentiary hardship dossiers proving zero cash flow to secure maximum main loan haircuts without court action.
MSME Overdrafts
Protecting own assets under Section 31(g) SARFAESI while settling clean trade OTS terms.
ARC Debt Assignments
Verifying SARFAESI Section 5 assignment validity and settling deep settlements reflecting ARC acquisition discounts.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".