Personal Loan Na Chukane Par Kya Hota Hai?
Agar aap money crisis. Job loss ya medical emergency ke karan own loan EMI nahi bhar pa rahe hain. Toh samjhein 90-day NPA lifecycle. Claims limits. Legal notice defense. Aur 40% se 55% tak One Time closure (OTS) karwane ki legal process.
Jab koi clients medical emergency ya job loss ki wajah se clean own loan EMI default karta hai. Toh sabse pehle mental panic create hota hai. Indian banking laws ke mutabik clean loan non-payment strictly civil breach of contract hai. Jisme police arrest ya penal jail ka koi rules nahi hota.
Agar lagatar EMIs bounce hoti hain. Toh 90 din mein account SMA stage se nikal kar Substandard NPA classify ho jata hai. Is stage par bank penal rates freeze karta hai aur One Time closure (OTS) window open karta hai.
RBI Fair Practices Code agents ko odd hours mein call karne aur relatives ko harass karne se strictly rokta hai. Section 25 PSSA ya Section 138 notice ka timely legal reply dekar aap ex-parte claims orders ko block kar sakte hain aur 40% se 55% main sum waiver ke sath valid No Dues letter (NDC) hasil kar sakte hain.
1. Debt Economics & 90-Day NPA Dynamics in India
clean own loan portfolio mein koi real pledge hypothecated nahi hota. Jab clients money hardship ke chalte EMI service nahi kar pata. Toh banks RBI ke Master Direction on IRACP framework ke antargat bound hote hain.
Delinquency teen stages mein progress karti hai: pehle 1 se 30 din overdue par SMA-0 tag hota hai. 31 se 60 din par SMA-1 banta hai. Aur 61 se 90 din par SMA-2 designate hota hai. Jaise hi 90 din cross hote hain. Account formally Substandard Non-Performing Asset (NPA) classify ho jata hai.
NPA tag hote hi bank ko loan amount par 15% Tier-1 capital provisioning separate karni padti hai aur unbilled rates income freeze ho jati hai. Chunki clean loans par SARFAESI Act apply nahi hota. Isliye banks prolonged litigation ki jagah One-Time closure (OTS) ke through capital claims prefer karte hain.
2. Principal vs Penal Charges and Loan Settlement Math
Default ke baad clients ke account mein sabse bada distortion 24% se 36% compound penal rates aur NACH bounce fees create karti hain. Jo 6 se 12 mahine mein claim ko main sum se 25% se 40% inflate kar deti hain.
CredSettle team loan ledger ka audit karti hai taaki artificial charges ko main sum se bifurcate kiya ja sake. Banks ke Delegation of money Power (DOFP) matrices ke tehat credit boards genuine hardship mein 100% penal waiver aur 40% se 55% deal discount sanction karti hain.
₹6,00,000 clean Loan Case Study
₹6,00,000
36 Months @ 14% p.a.₹4,80,000
Pure Unpaid Capital₹1,45,000
180 Days Compounded₹6,25,000
Gross Demand Total₹2,15,000
Full & Final Payment₹4,10,000
65.6% Debt Reduction3. Comparative Matrix: Personal Loan Resolution Pathways
Default ke baad restructuring tenure extend karke rates double kar deti hai. Jabki passive default CIBIL ko 7 saal ke liye ruin karta hai. Civil litigation dono parties ke liye expensive hoti hai. Jabki One-Time closure (OTS) sabse practical legal exit provide karta hai:
| Resolution Route | Financial Cost | Legal Risk | CIBIL Impact | Settlement Verdict |
|---|---|---|---|---|
| One-Time closure (OTS) | 40% to 55% main sum | Zero risk post NDC | Marked Settled Rebuildable | Optimal for acute money distress |
| Loan Restructuring | 100% main sum + rates | Temporary relief high rates | Marked Restructured | Viable only if income recovers fast |
| Civil Court Litigation | High fees + 100% claim | Summons attachment risk | Marked Suit Filed | Expensive stressful court battle |
| Lok Adalat deal | 50% to 70% of Claim | Binding decree zero appeals | Marked Settled via Lok Adalat | Good forum for consensual closure |
| Ignoring &. Inaction | growing penal rates | Severe agent threats | CIBIL ruined for 7 years | Worst choice leads to vulnerability |
4. Technical CIBIL Algorithm & Credit Score Impact
CIBIL aur credit bureaus 5 factors evaluate karti hain: Payment History (35%). Credit Utilization (30%). History Age (15%). Credit Mix (10%). Aur Inquiries (10%).
Jab default 90 days cross karta hai. Payment history scoring collapse hone se score 100 se 250 points plunge kar jata hai. Unresolved default par bank Written Off status report karta hai jo 7 saal tak fresh credit block kar deta hai.
deal OTS execute karne par status Settled mark hota hai. Section 21 CICRA Act ke tehat balance dispute karke status Closed karwaya ja sakta hai. Jisse 12-24 mahine mein score 750+ rebuild ho jata hai.
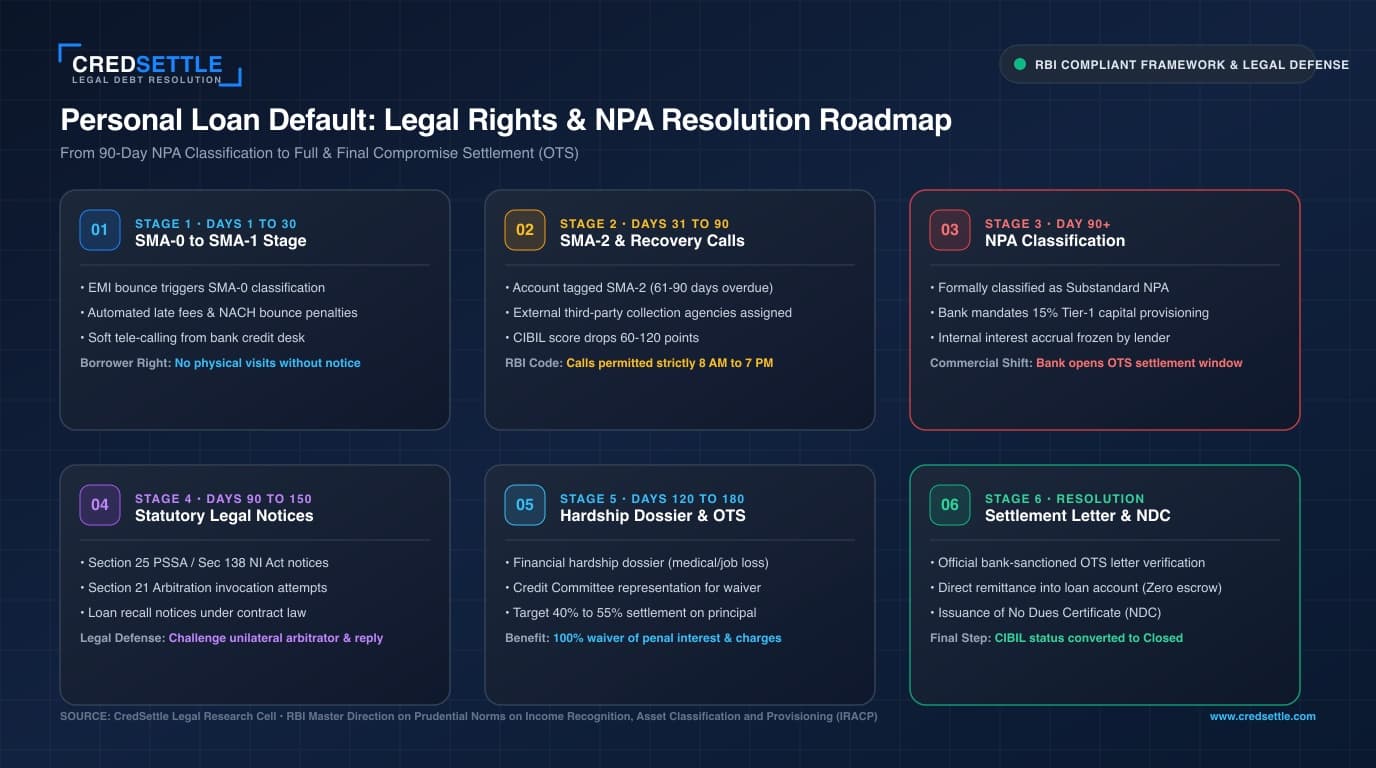
Visual Blueprint: Personal Loan Default & Resolution Roadmap
Neeche diye gaye visual roadmap mein own loan delinquency ke 6-stage lifecycle ko explain kiya gaya hai:
5. Step-by-Step SOP: 6 Stages of Personal Loan Resolution & OTS
own loan default ko smoothly resolve karne aur threats se permanent relief pane ke liye CredSettle ka 6-stage SOP follow karein:
Forensic Account Audit
Bank se Statement of Account procure karke main sum ko artificial penal rates aur unapproved charges se alag karein.
Hardship Dossier Compilation
Job loss end slip. Medical discharge summary. Ya firm loss report assemble karke hardship representation tayar karein.
Credit board Engagement
External claims call centers ko bypass karke direct bank ke Credit board aur Nodal heads se closure initiate karein.
Bilateral talks
Hardship precedents cite karke 100% penal waiver aur main sum balance par 40% se 55% tak deal discount settle karein.
Sanction Letter Legal Vetting
Bank se valid OTS sanction letter lekar check karein ki letter mein agreed amount aur legal withdrawal terms clearly stated hon.
wire transfer &. NDC Procurement
Agreed amount direct bank loan account mein deposit karein. Unconditional No Dues letter lein. Aur CIBIL update ensure karein.
6. Statutory Notice Defense: What Banks Can & Cannot Legally Do
Loan default hone par bank legal notices issue karti hai jinka timely reply dena zaroori hai:
Payment Systems Act Notice
Auto-debit bounce par 15 din ka notice milta hai. Formal reply bhejkar money hardship aur lack of penal intent prove kiya jata hai.
Negotiable Instruments Notice
Security cheque bounce par 15 din mein reply file karein. Supreme Court ke Dashrath Rupsingh Rathod ruling ke mutabik misuse contest karein.
Arbitration Invocation
Supreme Court Perkins Eastman ruling ke tehat unilateral arbitrator appointment voidable hoti hai. Jisse contest karke closure banti hai.
Debt claims court
Bada loan exposure hone par bank DRT move karti hai. Written Statement file karke matter Lok Adalat conciliation ke liye refer karwayein.
RBI rules ke mutabik agents subah 8 baje se pehle aur shaam 7 baje ke baad call nahi kar sakte. Abusive language use nahi kar sakte. Aur bina ID card visit nahi kar sakte.
7. 3-Tier Grievance Redressal Matrix for Unlawful Harassment
Agar agents RBI guidelines violate karte hain. Toh structured 3-tier legal escalation follow karein:
Grievance head
threats calls ke audio proofs aur numbers ke sath bank ke Grievance head ko formal complaint lodge karein.
main sum Nodal head
Branch se relief na milne par zonal main sum Nodal head ko escalate karein jinke paas firm contract cancel karne ki authority hoti hai.
Integrated RBI officer
30 din mein relief na milne par cms.rbi.org.in par complaint file karein jaha RBI officer direct fine impose karta hai.
8. Chronological Timeline: Procedural Milestones from Default to NDC
own loan default hone par procedural progression chronological milestones ke through unfold hota hai:
| Milestone | Timeline | Bank Classification | Strategic Borrower Action |
|---|---|---|---|
| SMA-0 Stage | Days 1. 30 | Automated late fees. Bounce SMS | Assess money health. Stop auto-debits |
| SMA-1 / SMA-2 | Days 31. 90 | calls firm tele-calling | Record calls. Assemble hardship proof |
| NPA Declaration | Day 90+ | Substandard NPA. 15% rules | Submit formal deal OTS representation |
| legal Notices | Days 90. 150 | Sec 25 / Sec 138 / Arbitration | Serve structured legal reply contesting claims |
| closure &. NDC | Days 150. 180 | Sanction OTS. Issue NDC | Direct payment. Obtain NDC. Update CIBIL |
9. Specialized Real-World Personal Loan Default Scenarios
Different money crisis cases mein customized legal defense aur closure strategy apply hoti hai:
Multiple loans default hone par legal notice urgency ke basis par sequential OTS execute kiya jata hai.
Salaried experts layoff mein severance slips submit karke 55% tak main sum discount secure kar sakte hain.
firm owners GST cancellation aur losses present karke trade distress ke tehat low-ticket OTS le sakte hain.
Jab bad loans ARCs ko sell hote hain. Tab ARCs deep OTS concessions readily offer karti hain.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions on Personal Loan Default & Settlement
own loan default aur legal rights se related key questions ke authoritative answers:
Statutory Citations & Regulatory Authorities
Yeh legal breakdown primary Indian banking laws aur RBI directives par based hai:
- RBI IRACP Directions (2021/2023): Norms on asset classification and provisioning.
- RBI Fair Practices Code (2022/2023): Guidelines prohibiting claims threats.
- Section 25. PSSA 2007: online NACH mandate dishonor framework.
- Section 138. NI Act 1881: Cheque dishonour notice procedures.
- Arbitration Act 1996: Unilateral appointment restrictions.
- CICRA 2005: desk reporting standards and remediation.