Navi Loan Default Harassment: Stop Recovery Threats & Settle Legally
Facing harsh claims calls. Contact scraping. Or doorstep visits from Navi Finserv agents? Learn your legal rights under RBI regulations. Stop claims abuses. And settle an affordable One-Time settlement.
- Civil safety: Defaulting on an no-pledge Navi loan is purely civil with zero police arrest formal.
- rights Shield: RBI rules strictly prohibit accessing contact lists. Photos. messaging relatives and employers.
- Visit Regulations: Field agents must give prior written notice and visit only between 8:00 AM and 7:00 PM.
- Anti-abuse Shield: Relentless robocalls and workplace humiliation violate the RBI Fair Practices Code.
- legal reports: Unresolved claims abuses can be escalated to Navi main loan Nodal agents and RBI agents.
- 40% to 55% OTS Waiver: late app loans in NPA status can be settled with large rates reductions.
- Notice Defense: Formal replies to Section 25 PSSA NACH bounce notices prevent ex-parte legal actions.
- CIBIL Rehabilitation: Securing a No Dues letter enables structured credit score claims under CICRA.
1. Debt Economics & NPA Dynamics of Digital Lending Apps
Navi Finserv operates as a systemically key NBFC using automated algorithmic underwriting to disburse no-pledge private loans across India. Unlike traditional banks evaluating physical pledge. online fintech lenders rely on algorithmic risk scoring and bank record analysis. When macroeconomic stress. Unexpected job loss. health crises. Trade downturns cause missed installments. The loan undergoes legal asset classification under Reserve Bank of India prudential norms.
During the initial 1 to 30 days of default. The account enters SMA-0 status. Advancing through SMA-1 (31 to 60 days) and SMA-2 (61 to 90 days). Upon crossing 90 days of steady non-payment. The loan is formally classified as a Non-Performing Asset (NPA). Under RBI cash adequacy rules. NBFCs must allocate strict Tier-1 cash bank reserves against no-pledge NPAs. Locking balance sheet liquidity. Because no-pledge loans have no pledge governed by the SARFAESI Act. Lenders cannot seize home. As a result. Bank boards prioritize trade One-Time deals (OTS) to recover main loan cash and release bank reserves reserves.
2. Financial Breakdown & Settlement Target Math
When an no-pledge app loans defaults. Automated billing engines add extra fees rates. Late fees. Repeated NACH mandate bounce charges (often ₹500 to ₹1,000 per bounce). Over a 180-day default period. These growing non-main loan charges artificially inflate the ledger balance by 25% to 40% above the genuine main loan released.
During trade OTS talks. The primary objective is separating the by law binding main loan exposure from arbitrary penal fees. Credit boards hold special formal to waive 100% of extra fees. Late payment charges. office fees. Meanwhile. Accepting a structured main loan haircut based on demonstrated hardship. For a agent ₹5,00,000 late Navi loan escalated to ₹6,80,000 with extra fees. An bank OTS typically closes at ₹2,50,000 to ₹3,20,000 (a 40% to 55% total waiver). Payable in a single lump sum or structured two-tranche disbursements.
3. Legal & Financial Resolution Options Matrix
Resolving a late online private loans requires evaluating available claims relief options under Indian money regulations:
| Resolution Route. | Waiver Scope | Harassment Status. | Turnaround | Bureau Impact |
|---|---|---|---|---|
| One-Time settlement (OTS). | 40% to 55% Total Waiver. | fast Cessation. | 30-60 Days | Settled (Upgradable). |
| Loan Restructuring. | Zero loan cut. | Conditional on EMI. | 15-30 Days | Restructured |
| Civil Court lawsuits. | Court Discretion. | Protracted claims. | 2-5 Years | Severe DPD Loss |
| National Lok Adalat. | 30% to 50% OTS deal. | fast on Award. | Single Day | Lok Adalat Settled. |
| Default Inaction. | Zero (Penalties Rise). | Severe reports. | Indefinite | Sub-550 Score |
4. Technical CIBIL Algorithm & Score Rehabilitation
Credit Information CIBIL desk (India) Limited (CIBIL) and peer bureaus calculate creditworthiness using a 300 to 900 score model. Five key weighted factors determine score calculation: Payment History (35%). Credit Exposure and use (30%). Credit History Length (15%). Credit Mix (10%). Recent Credit Inquiries (10%).
Defaulting on a app loans damages the 35% payment history component. This results in an 80 to 140 point drop within 90 days. While an OTS brings a temporary 40 to 60 point drop due to Settled reporting. It permanently halts active growing default marks. Under Section 21 of the Credit Information firms (Regulation) Act. 2005 (CICRA). Clients can systematically rebuild their score to 750+ within 18 to 24 months by using secured credit builder cards. Maintaining credit use below 30%. Eventually converting Settled to Closed status through residual differential clearance.
5. Visual 6-Step Defense & Settlement Blueprint
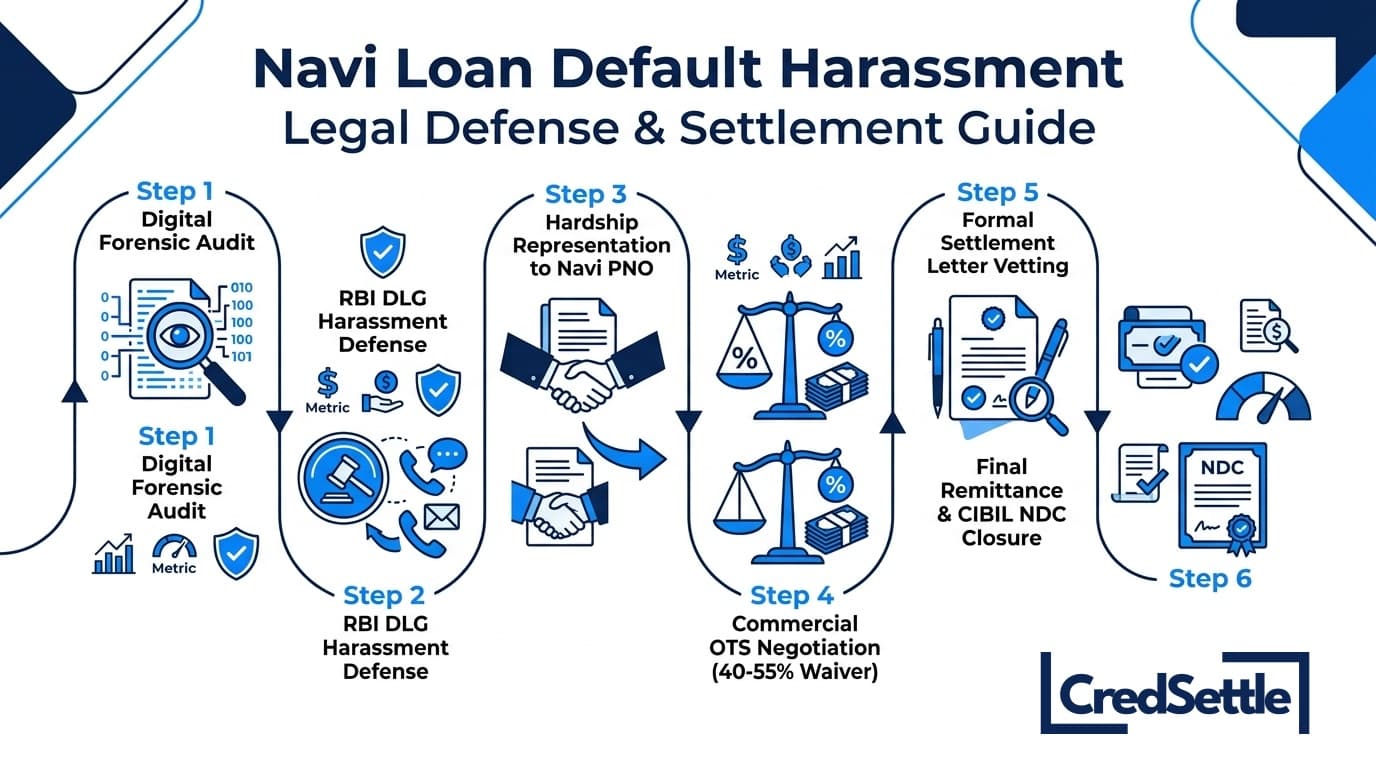
The visual blueprint below outlines the 6 stages of stopping claims abuse and executing an authorized settlement with Navi Finserv under Reserve Bank of India RBI directives:
6. Step-by-Step SOP: 6 Stages from Default to Final Settlement
Conduct an exhaustive analysis of the app loans sanction letter. Payment schedules. Bank debits. And rates computations. Identify errors including rates exceeding approved APR caps. banned mandate bounce fees. And uncredited payments.
Assemble irrefutable documentary proof establishing genuine debt stress. Key proof includes termination letters. Health letters. Salary deduction records. Trade income tax return depreciation. Bank records showing cash flow ruin.
Issue a formal legal notices to Navi Finserv and its claims firms demanding fast cessation of banned calls. Workplace visits. Contact list abuse under the RBI online Lending rules and Fair Practices Code.
Engage straight with Navi bank board and nodal claims managers. Present the structured hardship dossier to settle maximum waivers on extra fees. Late payment penalties. main loan balances for an affordable OTS amount.
Subject the formal OTS approval letter to rigorous legal scrutiny. Ensure the paper explicitly specifies the agreed OTS deal amount. Payment deadlines. Waiver terms. A binding commitment to issue an full No Dues letter.
Execute the settlement payment straight into the designated Navi Finserv bank loan account via traceable banking channels. Secure the original No Dues letter (NDC) and initiate formal CIBIL desk updates under CICRA 2005.
7. Statutory Notice Defense & Borrower Rights
Navi Finserv and online lending entities use local legal rules to recover defaulted no-pledge debts. Understanding your substantive legal rights safeguards you against coercive tactics:
When auto-debit mandates bounce. Lenders may issue a 30-day notice alleging quasi-penal debt risk. Establishing genuine debt stress and absence of fraudulent intent provides a solid defense while initiating OTS talks.
Applicable when payment cheques dishonor. A valid legal defense requires showing that the instrument was issued merely as pledge rather than towards a crystallized debt. Proving lack of timely legal notices.
Lenders often invoke hearing for rapid awards. Under Supreme Court rulings in Perkins Eastman and TRF Ltd. Unilateral judge appointments by lenders are by law invalid. Granting grounds to challenge police area under Section 12(5).
no-pledge private loans below ₹20 Lakhs cannot be brought before the Debt claims Tribunal. Also. The RBI Fair Practices Code strictly prohibits physical force. Verbal abuse. Public humiliation. Doorstep visits outside 8:00 AM to 7:00 PM.
8. 3-Tier Escalation Matrix Against Recovery Abuses
When facing non-compliant claims tactics or banned contact scraping. Clients must follow a structured reports rules:
Grievance Redressal Officer
Lodge a written reports with Navi designated GRO citing local call dates and violations. Response turnaround is 7 to 10 working days.
Principal Nodal Officer
Escalate to the main loan Nodal agents of Navi Finserv with call recordings and proof. Response turnaround is 14 to 21 days.
RBI Integrated Ombudsman
If unresolved after 30 days. File a legal reports on the RBI CMS portal (cms.rbi.org.in) under the Integrated agents Scheme.
9. Chronological Timeline: From Default to Resolution
Navi private loans default follows defined legal and trade milestones:
| Timeline | Asset Classification. | Lender Action | Defense Strategy. |
|---|---|---|---|
| Day 1-30 | SMA-0 | Automated SMS and app alerts. | Audit records and track records. |
| Day 31-60 | SMA-1 | Tele-calling claims outreach. | Enforce RBI calling hour limits. |
| Day 61-90 | SMA-2 | Pre-lawsuits warning notices. | Compile hardship dossier. |
| Day 91-120 | NPA | strict cash bank reserves. | Initiate formal OTS settlement. |
| Day 121-180 | Deep Default | Section 25 PSSA / Sec 21 notices. | Finalize 40% to 55% OTS deal OTS. |
| Month 6+ | Settled | Account closure and NDC issued. | Rehabilitate CIBIL score under CICRA. |
10. Specialized Real-World Default Scenarios
Default situations differ depending on client money situation. Our legal panel resolves complex online lending challenges across four common scenarios:
clients with active loans across multiple apps face severe payment stress. CredSettle implements a consolidated defense plan. Settling coordinated OTS waivers across all lenders simultaneously.
workers impacted by firm layoffs or prolonged unemployment can present formal termination letters and severance proofs to secure deep main loan settlement discounts.
shop owners using online private loans for daily work cash flow can leverage audited records and GST decline filings to prove trade hardship before credit boards.
When Navi Finserv transfers late loan portfolios to Asset Reconstruction firms. Our legal team conducts deep assignment check under SARFAESI Section 5. Settling steep portfolio discounts.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
12. Frequently Asked Questions: Navi Loan Default & Harassment
Authoritative legal answers regarding Navi loan defaults. Claims rules. And debt settlement in India.
Official Regulatory Citations & Statutory Authorities
- Reserve Bank of India: rules on online Lending (2026) and Master Direction on Fair Practices Code.
- Reserve Bank - Integrated agents Scheme. 2021: Redressal of Unfair claims Practices and Charges.
- Ministry of Law and Justice: Payment and settlement Systems Act 2007 (Section 25). Negotiable Instruments Act 1881 (Section 138). hearing Act 1996 (Section 21).
- Credit Information firms Act. 2005: Rights of clients regarding credit score claims redressal under Section 21.
- Supreme Court of India: Perkins Eastman (2020). and TRF Ltd. (2017) on unilateral judge disqualification.