Lok Adalat Notice Kya Hota Hai? NALSA Settlement & Legal Rights
Bank ya NBFC se Lok Adalat notice mila hai? Janein Lok Adalat notice kya hota hai. NALSA settlement process. 50% se 70% loan waiver prapt karne ke legal tarike aur legal rights.
Receiving a Lok Adalat notice often causes panic among clients who mistake it for a criminal summons or police warrant. In reality. Lok Adalat is an amicable talks body established under the Legal Services officials Act. 1987. Organised under NALSA. It operates purely as a civil talks bench with zero powers to issue arrest warrants or order imprisonment. Role is completely voluntary. And no settlement can be forced without mutual. Written consent.
Because banks use National Lok Adalats to write off NPAs and release locked Tier-1 cash. Clients gain large settlement leverage. Presenting a documented hardship dossier allows clients to eliminate 100% of total penal interest and settle 50% to 70% waivers on core dues. Any agreed OTS deal results in an formal Section 21 Award. Holding the binding formal of a final. Non-appealable Civil Court decree.
1. Debt Economics: Why Banks Send Lok Adalat Notices
When an individual defaults on private loans or credit card EMIs for 90 days. Banking regulations require the lender to classify the account as a Non-Performing Asset (NPA). Under RBI prudential norms. Banks must allocate 15% to 100% of the overdue debt into locked Tier-1 cash reserves. Restricting lending work and eroding bank profitability.
Because no-pledge loans lack mortgaged security. Lenders cannot enforce SARFAESI property seizures. Traditional civil lawsuits entails upfront court fees of 5% to 10% and multi-year delays. As a result. Banks partner with areas Legal Services officials (DLSA) to refer overdue debts to National Lok Adalat. For banks. Lok Adalat provides an expedited One-Time Settlement (OTS) mechanism to recover liquid cash. Write off bad debts. Release locked reserves in a single sitting.
2. Settlement Math: 50% to 70% Lok Adalat Waivers
Following a default. Lenders inflate balances by adding 24% to 36% compound penal interest. Bounce surcharges. claims fees. In Lok Adalat talks. The bench systematically disregards these arbitrary penal additions. Focusing discussions strictly on net unrecovered main loan and genuine client capacity.
Consider a defaulted ₹4,00,000 private loans where ₹3,50,000 in unpaid main loan inflates to a ₹6,50,000 bank demand due to ₹3,00,000 in penal interest and fees. Through structured Lok Adalat talks. The client&apos. S counsel can eliminate 100% of the ₹3,00,000 penal surcharge while securing a 40% hardship discount on the base loan. This establishes a final binding Section 21 settlement of ₹2,10,000. Delivering a total waiver of ₹4,40,000 (67.7% relief) and complete legal discharge.
Bank Inflated Claim Structure (Pre-Adalat)
Lok Adalat Negotiated Compromise Math
3. Resolution Matrix: Lok Adalat vs Court vs Arbitration
Compare how National Lok Adalat compares against conventional claims routes for no-pledge private loans defaults:
| Resolution Forum. | Governing Statute. | Arrest Powers | Finality & Appeal. | Resolution Timeline. | Borrower Advantage. |
|---|---|---|---|---|---|
| National Lok Adalat. | Legal Services Act 1987. | Zero (Civil talks). | Sec 21 Award | Single Sitting | 50%-70% Waiver &. Binding Decree. |
| Summary Civil Suit. | Order 37 CPC | Zero (Civil claims). | Money Decree | 18-36 Months | Extended lawsuits, interest debt risk. |
| Arbitration Tribunal. | Arbitration Act 1996. | Zero (Private Bench). | Sec 36 Decree | 4-8 Months | Challenge Sec 12(5) Unilateral Appointment. |
| Debt claims Tribunal. | RDBFI Act 1993 | Zero (Claims >. ₹20L). | claims letter. | 12-24 Months | High legal costs &. contested accounting. |
| Total Inaction | None (Ignored Notices). | Ex-Parte Attachments. | Ex-Parte Decrees. | Unchecked | Score Destroyed &. Compounding Dues. |
4. CIBIL Dynamics: DPD Tracking & Bureau Upgrades
Credit bureaus (CIBIL, Experian, Equifax. CRIF High Mark) evaluate creditworthiness using five factors: Payment History (35%). Credit use (30%). Credit History Depth (15%). Credit Mix (10%). Recent Inquiries (10%). Defaulting past 90 days past due (90+ DPD) triggers an automated risk flag across inter-bank systems. Reducing credit scores by 80 to 140 points.
Executing a Lok Adalat OTS deal initially updates bureau records to Settled status. Terminating active lawsuits flags and negative DPD compounding. To restore credit ratings systematically. Clients can invoke Section 21 of the Credit Information Companies (Regulation) Act. 2005 (CICRA). Submitting the certified Section 21 Lok Adalat Award alongside the bank&apos. s full No Dues letter ensures the balance is reported as zero. This lets progressive credit rebuilding over 12 to 18 months.
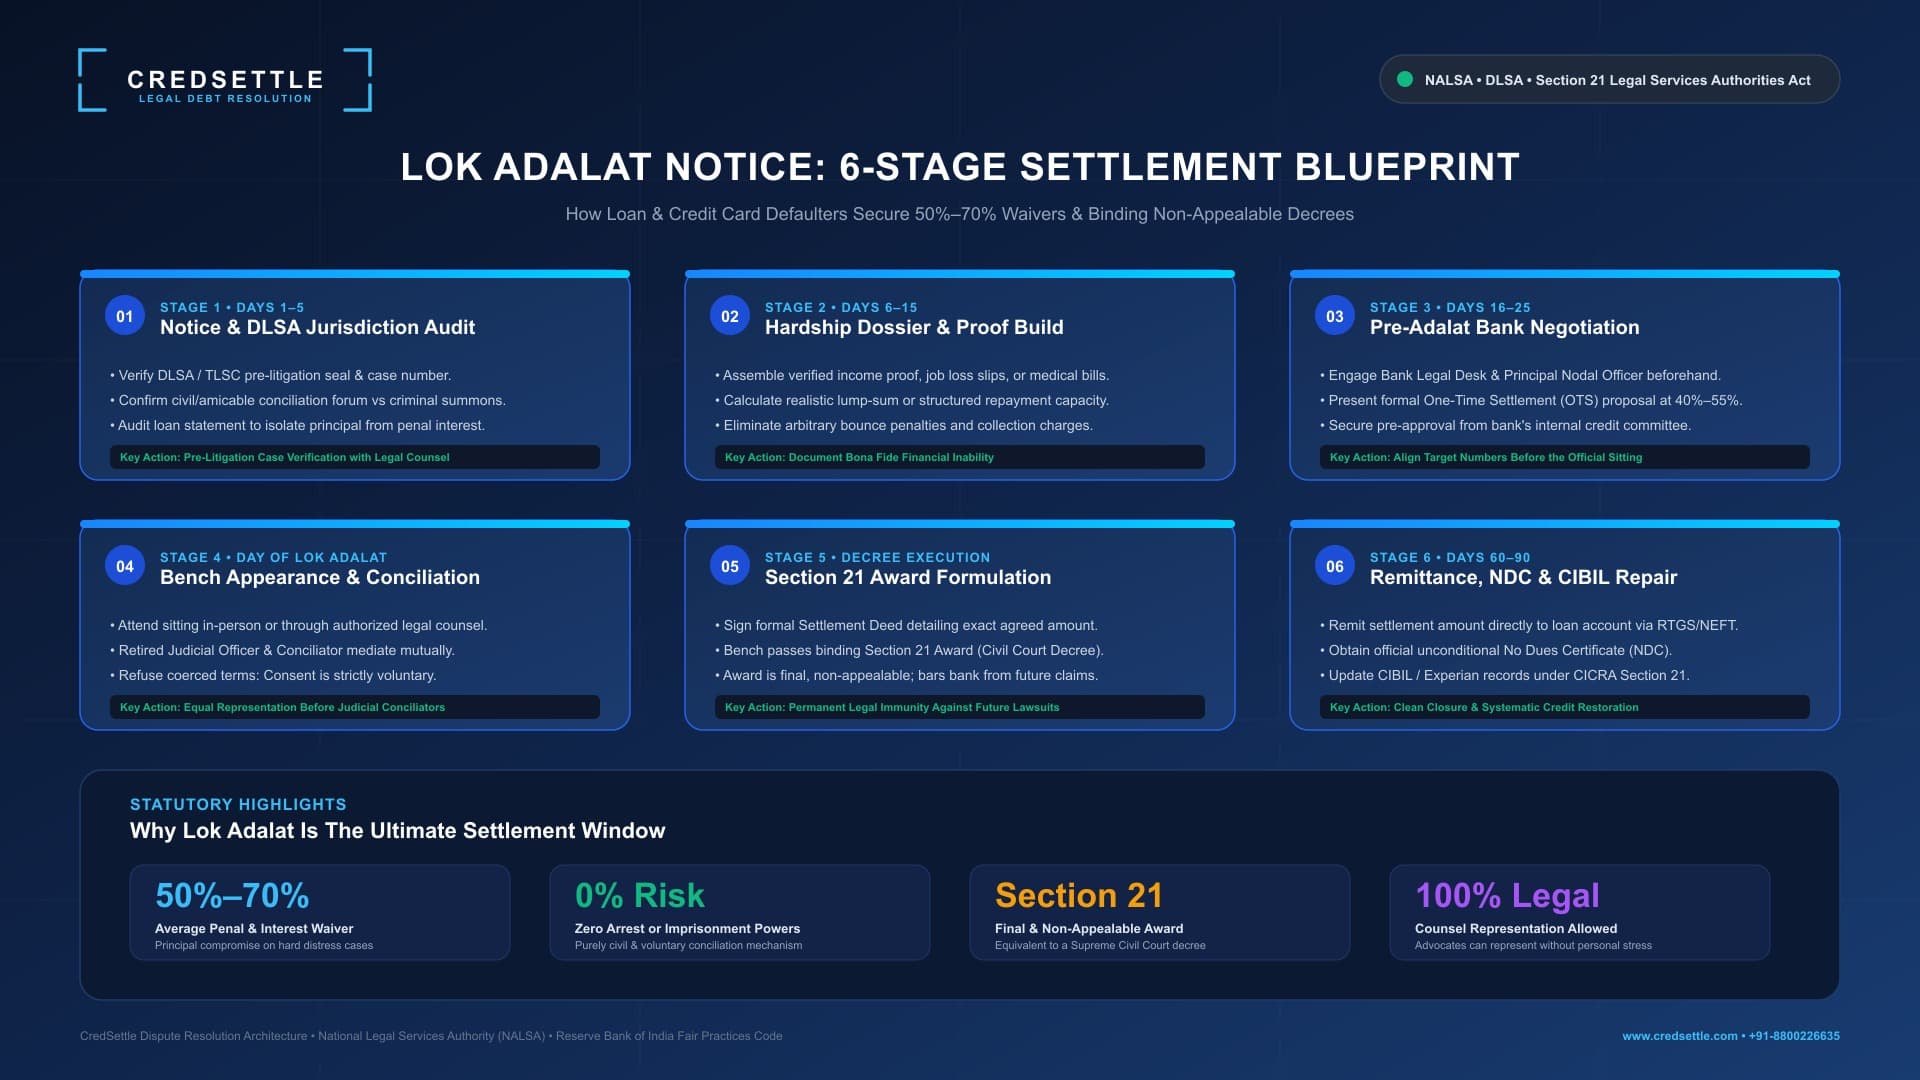
5. Visual Roadmap: Lok Adalat Settlement Workflow
Refer to this visual roadmap illustrating the procedural workflow to handle Lok Adalat notices. Challenge excessive interest claims. Secure binding Section 21 consent awards:
6. Step-by-Step SOP: Handling Lok Adalat Notices
Successfully resolving a defaulted private loans through Lok Adalat requires following a structured six-stage procedural workflow:
Notice Verification & Audit
Verify the DLSA seal and Pre-lawsuits Case number. Audit loan records to isolate main loan balances from arbitrary penal surcharges.
Hardship Dossier
Compile verified distress proof. Examples include termination letters, salary cuts. Or medical records. To prove waiver requests before the bench.
Pre-Adalat Bank Representation
Engage the bank&apos. s Legal Cell and Nodal Officer before the session. Submitting an OTS proposal enables pre-approval of large concessions.
Bench Conciliation
Appear before the bench in person or via counsel. The judicial conciliator mediates terms neutrally. Ensuring no coercive terms are imposed.
Section 21 Award
Upon reaching pacts. Execute a formal Settlement Deed. The bench issues an formal Award under Section 21. Establishing a binding civil decree.
Remittance & NDC
pay settlement funds straight to the loan account. Obtain an full No Dues letter and rectify credit bureau records under CICRA 2005.
7. Notice Defense: PSSA, NI Act & DRT Provisions
clients managing defaulted debt often receive parallel legal notices. Understanding each rules ensures a robust defense:
NACH Dishonor Defense
When NACH mandates bounce. Lenders issue Section 25 notices. Because Section 25 offenses are compoundable. Settling before a Lok Adalat bench leads to the fast quashing of complaints without criminal conviction.
Cheque Bounce Compounding
Lenders often file Section 138 complaints upon cheque dishonor. Under Section 147 of the NI Act. Cheque bounce matters are explicitly compoundable. Executing Lok Adalat OTS deal terms permanently disposes of magistrate court proceedings.
Challenging Arbitrator Nominations
Lenders often initiate private arbitration by unilaterally appointing sole arbitrators. Under Supreme Court rulings (TRF Ltd. And Perkins Eastman). Unilateral nominations are disqualified de jure under Section 12(5). This lets transition to Lok Adalat.
High-Value Claims & Anti-Coercion
Claims exceeding ₹20 Lakhs before Debt claims Tribunals can be referred to Lok Adalats under Section 19(1). Additionally. The RBI Fair Practices Code strictly prohibits claims agents from threats or illegal visits.
8. 3-Tier Escalation Matrix: Defending Borrower Rights
If lenders or claims firms violate legal rules. Escalate through this structured three-tier grievance redressal mechanism:
Formal Statement Audit
File a written objection challenging arbitrary penal surcharges. Requesting formal referral to the bank&apos. s OTS deals boards for Lok Adalat disposal.
Executive Nodal Escalation
If the GRO fails to resolve the dispute or if agent abuse persists. Escalate straight to the main loan Nodal Officer with documented hardship proof to stay claims calls.
Regulatory Complaint Filing
If thirty days elapse without bank relief. Lodge a formal RBI complaint on the RBI CMS portal (cms.rbi.org.in) under the Integrated Ombudsman Scheme. 2021.
9. Procedural Timeline: Notice Receipt to Final Closure
Understanding chronological milestones enables systematic defense planning:
| Timeline Phase | Procedural Milestone. | Statutory Framework. | Actionable Strategy. |
|---|---|---|---|
| Day 1 | Notice Receipt | Sec 19/20 Legal Services Act. | Verify DLSA seal and isolate main loan. |
| Days 10. 20 | Hardship Dossier. | RBI Fair Practices Code. | Compile income loss proofs and engage nodal desk. |
| Days 30. 45 | Bench Sitting | NALSA talks Rules. | Represent via counsel and execute decree. |
| Days 60. 90 | OTS deal Remittance. | Sec 21 Award Terms. | Pay settlement straight and secure NDC. |
| Months 4. 6 | Credit Restoration. | CICRA 2005 Sec 21. | Upgrade CIBIL status to Closed. |
10. Real-World Scenarios: Layoffs, Business & ARCs
Lok Adalat talks mechanics provide versatile debt relief pathways across diverse client hardship scenarios:
Multi-Lender Consolidation in Lok Adalat
clients managing defaulted cards and loans across multiple banks can coordinate joint talks sittings. Settling simultaneous OTS deal pacts across all lenders to eliminate claims pressure.
Corporate Layoffs & Executive Income Loss
Salaried workers impacted by workforce reductions can submit severance letters. Establishing genuine distress and motivating credit boards to grant up to 60% main loan waivers.
Proprietorship & Working Capital Defaults
Small shop owners facing cash-flow collapse can resolve no-pledge overdrafts through Lok Adalat. Preventing asset attachment and shielding guarantors from lawsuits.
Debt Assigned to Asset Reconstruction Companies
When loans are sold to ARCs (e.g. Phoenix ARC. ARCIL). These entities offer deep OTS deals in Lok Adalat for rapid cash recoveries.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions: Lok Adalat Notice Kya Hota Hai
Click on any question below to view detailed legal answers verified by our debt relief workers:
Official Regulatory Citations & Judicial References
- Legal Services officials Act, 1987: Sections 19, 20, 21, and 22. Ministry of Law and Justice. Government of India.
- National Legal Services formal Regulations, 2009: rules for Pre-lawsuits Bank claims Matters.
- Reserve Bank of India Master Directions: Fair Practices Code for Lenders and Grievance Redressal Mechanism.
- Credit Information Companies (Regulation) Act. 2005 (CICRA): Section 21 regarding accuracy and credit status rectification.
- Negotiable Instruments Act, 1881: Section 138 read with Section 147 (Compounding of Cheque Dishonor Offenses).