KreditBee Recovery Agent Harassment: Legal Complaint Guide
Are claims agents calling your relatives. Scraping your contact list. Issuing unlawful threats for a defaulted KreditBee private loans? Understand your legal protections under Reserve Bank of India directions. Lodge formal RBI reports. Secure an authorized OTS deals.
- Regulated NBFC Governance: KreditBee loans operate under Krazybee Services Private Limited. Bound by RBI master directions.
- No Third-Party Calling: Calling kin or scraping contacts violates RBI online Lending rules and the IT Act.
- Permissible Calling Hours: claims calls and home visits are by law restricted to 8:00 AM through 7:00 PM.
- Civil claims Immunity: no-pledge loan default is a civil matter. agents cannot threaten police arrests or warrants.
- Section 25 NACH Defense: Auto-debit bounce notices require timely 30-day legal replies establishing hardship.
- Asset Seizure Immunity: no-pledge online credit carries no mortgage. Barring home attachment under SARFAESI.
- Direct OTS deals: Accounts reaching NPA status qualify for OTS deals at 40% to 55% of claims.
- 3-Tier reports: abuse is escalated to Krazybee GRO. The main loan Nodal agents. And the RBI agents.
Digital Micro-Lending Economics & Krazybee NPA Dynamics
KreditBee originates online credit primarily through Krazybee Services Private Limited. An RBI-registered Systemically key Non-Banking money firm (NBFC-ND-SI). Alongside joint loans banks. When unforeseen hardships cause missed EMIs. Accounts progress across Special Mention Account stages: SMA-0 (1 to 30 days). SMA-1 (31 to 60 days). SMA-2 (61 to 90 days).
Past 90 days. The debt becomes a Non-Performing Asset (NPA). Central banking prudential norms mandate Tier-1 cash bank reserves against no-pledge NPAs. Creating strong trade incentives for Krazybee to accept structured One-Time deals (OTS). Because online private loans are no-pledge. Lenders hold no mortgage rights under the SARFAESI Act. Barring asset attachment without a civil court decree.
Principal Isolation & 180-Day NPA Settlement Mechanics
When an no-pledge online private loans defaults. The unpaid ledger balance on the mobile application escalates steeply through growing extra fees rates. Daily bounce surcharges. claims handling fees. In typical retail defaults. An initial released main loan of ₹1,00,000 can rapidly inflate to over ₹1,65,000 within six months of non-payment. During bank talks. Legal counsel isolates the genuine core main loan released from these excessive penalty layers. Creating an objective basis for OTS deal.
When an account reaches 180 days past due. The loan is fully provisioned on the lender balance sheet. At this juncture. Krazybee routinely accepts OTS deals between 40% and 55% of the total ledger claim. Waiving total penalties upon structured single or split-tranche remittance straight into the checked virtual account.
Original main loan.
₹1,00,000
extra fees &. Fees.
₹65,000
Gross Ledger Claim.
₹1,65,000
Final OTS Target.
₹50,000 - ₹55,000.
Executing an authorized OTS deals eliminates all residual debts. Halts third-party claims calls permanently. Secures an formal No Dues letter straight from Krazybee Services Private Limited.
Resolution Pathways Comparison Matrix
Evaluating different claims relief options allows late clients to compare money dues. Claims abuse outcomes. CIBIL desk repercussions. Legal finality before committing resources.
| Resolution Pathway. | Financial Outflow. | Harassment Halting. | CIBIL Bureau Impact. | Legal Finality |
|---|---|---|---|---|
| One-Time settlement (OTS). | 40% to 55% of claim. | fast upon sanction. | Marked as Settled. | Complete with NDC. |
| Loan Restructuring. | 100% main loan + rates. | Temporary relief. | Marked Restructured. | Ongoing debt debt. |
| Lok Adalat settlement. | 45% to 60% OTS deal. | Permanent post-award. | Reported as Settled. | Non-appealable decree. |
| Court lawsuits. | High legal &. court fees. | Requires court stay. | Marked Suit Filed. | Prolonged court battle. |
| Inaction / Ignoring. | Escalating penalties. | Intense claims calls. | Written-Off / Default. | Ongoing legal exposure. |
Credit Scoring Mechanics & Post-Settlement Rectification
The TransUnion CIBIL credit scoring algorithm operates across five weighted pillars: payment track record accounts for 35%. Credit use ratio represents 30%. Credit history vintage comprises 15%. The portfolio mix of secured versus no-pledge credit makes up 10%. Recent credit inquiries constitute 10%. Defaulting beyond 90 days severely damages the 35% payment weighting. This causes an acute drop of 120 to 180 points.
Executing a formal OTS marks the trade line as Settled. Promptly capping further DPD reporting. Clients can then use Section 21 of the Credit Information firms (Regulation) Act (CICRA 2005) or clear the waived balance to convert the account from Settled to Closed. Rebuilding a 750+ score within 12 to 18 months through disciplined secured credit cards.
Step-by-Step KreditBee Harassment Defense Workflow
Our visual roadmap outlines the core stages to stop unlawful claims abuse. Enforce RBI online Lending rules against Krazybee Services. Achieve an authorized OTS deals.
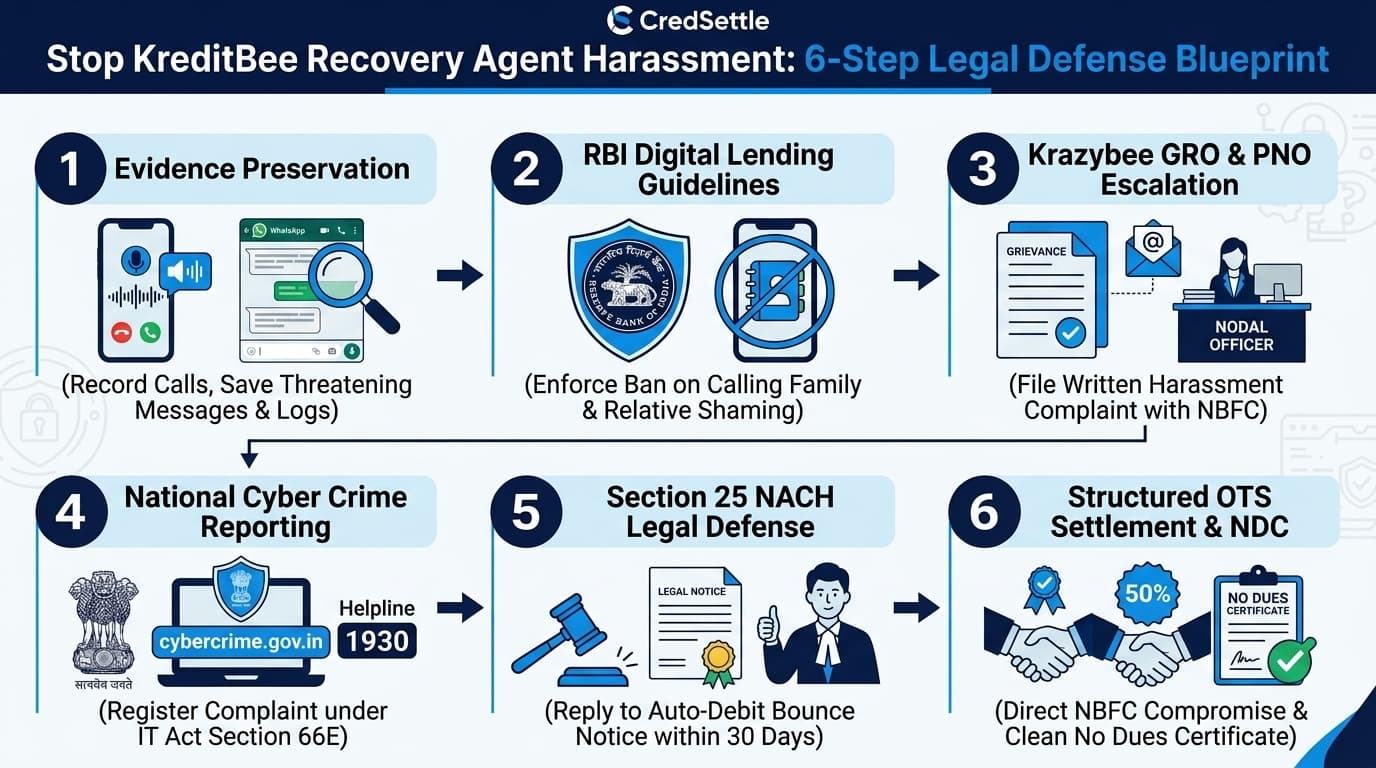
Standard Operating Procedure for Digital Loan Resolution
Resolving online debt claims requires a systematic. Proof-driven approach combining online paperwork with legal legal legal help.
Record threatening calls. Screenshot chat messages. And demand formal credentials from claims personnel to establish an evidentiary record.
Organize hardship proof including termination letters. health summaries. Or trade records to show inability to pay.
Serve a formal legal notice to Krazybee Services citing RBI online Lending rules. Notifying handling of claims infractions.
Engage the NBFC nodal desk straight to eliminate total extra fees. Settling a final OTS deals between 40% and 55%.
Verify that the sanction letter is on formal Krazybee letterhead. Accurately states terms. Confirms full waiver upon payment.
pay the payout sum straight into Krazybee checked virtual accounts. Then obtain an full No Dues letter.
Analytical Framework for Statutory Notice Defense
Understanding the legal rules governing online private loans protects clients from unlawful legal threats and enables structured legal defense.
Governs electronic auto-debit dishonours. Establishing genuine hardship in a timely legal reply refutes penal intent. Preventing legal steps and helping OTS deals.
Applies strictly to physical cheque dishonours. Purely app loans payments through NACH mandates cannot be prosecuted under Section 138 without a physical signed cheque instrument.
Unilateral sole judge appointments by online lenders are by law invalid under Supreme Court rulings in. Perkins Eastman and TRF LimitedNullifying ex parte awards.
Debt claims Tribunals require claims over ₹20 Lakhs. Retail app loans below this threshold are exempt from DRT action and governed strictly by RBI Fair Practices Code limits.
Hierarchical Redressal for Recovery Harassment
When claims firms violate RBI conduct directions. Lodge structured reports across RBI oversight tiers.
Grievance Redressal Officer
Submit a written reports with call recordings and chat screenshots. The GRO must acknowledge within 48 hours and resolve within 7 to 10 days.
Executive Nodal Desk
If Level 1 is unresolved. Escalate to the main loan Nodal agents of Krazybee Services to restrain third-party firms within 14 to 21 days.
Central Banking Portal
If unresolved after 30 days. File an appeal on the RBI Integrated agents portal (cms.rbi.org.in) for RBI penalties and legal relief.
Delinquency to Settlement Timeline
Tracking procedural progression helps anticipate lender calls and initiate OTS deal talks during optimal windows.
| Timeframe | Asset Category | Lender Collection Activity. | Borrower Action Strategy. |
|---|---|---|---|
| Day 1 to 30 | SMA-0 Stage | Automated SMS &. IVR reminders. | Log calls. Evaluate liquidity. |
| Day 31 to 60 | SMA-1 Stage | Tele-calling &. NACH notice reminders. | Submit written hardship notice. |
| Day 61 to 90 | SMA-2 Stage | Third-party firm assignment. | Demand agent ID and assert RBI rules. |
| Day 91 to 180 | NPA Status | strict 100% loss bank reserves. | Open OTS talks at 40%-55%. |
| Month 6 Onward | Loss Pool | ARC assignment consideration. | Finalize settlement &. obtain NDC. |
Practical Resolution for Complex Dispute Cases
Tailored legal solutions insulate private rights and resolve complex online lending claims effectively.
Contact Scraping & Relative Calling
When claims agents call non-guarantor kin. Issue an fast cease-and-desist letter citing RBI online Lending rules and file an IT Act Section 66E rights reports.
WhatsApp Group Defamation
If agents create WhatsApp groups to defame you. Capture full screenshots. This constitutes penal threats and public defamation under Section 356(2) of the Bharatiya Nyaya Sanhita 2023.
Corporate Layoffs & Income Loss
Submit termination letters to Krazybee before the 90-day mark. This establishes genuine good faith. Refutes fraud claims. And forms the basis for a deep-OTS deal OTS.
Multi-App Debt Consolidation
clients with multiple micro-loan defaults should consolidate claims under legal counsel. Enforce uniform RBI conduct rules. settle sequential OTS deals.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Authoritative Legal Answers on KreditBee Recovery & Settlement
Review checked answers to essential legal questions regarding app loans claims. RBI rules. debt settlement.
Regulatory Frameworks & Outbound Verification Links
All legal protections and settlement standards detailed here are anchored in central banking directions and legal Indian enactments.