Home Loan Default & SARFAESI Act: How to Stop Bank Auction
Master the legal defense blueprint to challenge Section 13(2) demand notices. Enforce the strict 15-day bank reply rule under Section 13(3A). Obtain urgent interim stays from the Debt claims Tribunal under Section 17. settle One-Time closure deed redemption.
Executive Summary: SARFAESI Defense & Property Rights
- Section 13(2) Demand Window: clients hold an full 60-day cure period during which lenders are by law barred from seizing physical takeover.
- strict 15-Day Written Order: A formal Section 13(3A) objection by law compels the bank to issue a reasoned written determination within 15 days. Vitiating subsequent coercive steps if neglected.
- Section 14 court Safeguard: Banks cannot forcibly dispossess an occupant without obtaining an office clearance order from the areas Magistrate or Chief city Magistrate.
- Zero Pre-Deposit DRT Remedy: Filing a Securitisation Application under Section 17 before the Debt claims Tribunal does not require any strict deposit and can secure interim auction stay orders.
- OTS deal OTS Economics: banks actively accept One-Time closure OTS deal terms to avoid multi-year tribunal delays. Discounting penalty fees and rates.
- Deed Redemption &. Title claims: Under Section 13(8). Full closure payment before auction notice publication entitles the client to an fast return of all original title deeds within 30 days.
1. The SARFAESI Framework & 90-Day NPA Classification Dynamics
When a client signs a mortgage contract for a residential or trade home in India. The transaction is underpinned by the Securitisation and Reconstruction of money Assets and Enforcement of pledge rates Act. 2002 (SARFAESI Act). Unlike no-pledge credit cards or private loans where lenders must institute protracted civil suits under the Code of Civil steps. Secured home loans grant banks summary powers to enforce their pledge rates without the direct intervention of a civil court.
However. This enforcement mechanism does not operate arbitrarily. The legal machinery can only be activated after an account satisfies strict RBI criteria established by the Reserve Bank of India. When an equated monthly installment (EMI) remains unpaid. The banking core software initiates progressive monitoring across Special Mention Account (SMA) buckets: SMA-0 for delinquencies between 1 and 30 days. SMA-1 for delays between 31 and 60 days. SMA-2 for arrears spanning 61 to 90 days. Only upon the 91st consecutive day of non-payment is the credit facility formally classified as a Non-Performing Asset (NPA).
NPA classification triggers large balance sheet results for the lender. Under RBI prudential norms. Banks must promptly freeze uncollected rates recognition and allocate strict cash bank reserves out of their operating reserves. To reduce this cash drag. The lender issues a legal demand notice under Section 13(2) of the SARFAESI Act. clients must understand that a Section 13(2) notice is not an eviction order. It is a formal demand granting an full 60-day legal window during which the homeowner retains full ownership. Physical takeover. legal rights to challenge the bank claims.
2. Loan Ledger Forensic Audit & Penal Math Breakdown
A frequent vulnerability in bank SARFAESI claims lies in the mathematical computation of the claimed debt. When an account enters default. Automated banking systems routinely levy extra fees. late processing charges. Checks fees. Legal overheads. Over several quarters. These ancillary fees compound exponentially. Inflating the demand amount by 20% to 40% beyond the legitimate main loan and contracted rates.
Under the RBI Master Circular on Fair Practices Code and the landmark directives on penalty charges in loan accounts. Regulated entities are strictly prohibited from capitalizing penalty charges into the main loan debt for growing purposes. penalty fees must be recovered separately as daily work fees and cannot be compounded with monthly rates. When an bank client or homeowner conducts a audits of their historical loan ledger. Large accounting errors often emerge. This provides decisive leverage to claims the Section 13(2) demand notice.
Forensic Debt Audit: Representative ₹75 Lakh Home Loan Default Claim
Note: A audits eliminates banned rates capitalizing during moratoria. Rectifies unapplied rates reductions under floating benchmark benchmarks. Strips away unapproved office fees. Creating a clean baseline for OTS deal talks.
3. Resolution & Legal Defense Mechanisms Matrix
Home loan clients confronted by SARFAESI claims steps have multiple legal and bank pathways to protect their assets. Choosing the appropriate mechanism depends on the stage of enforcement. The client money liquidity. Whether the primary objective is fast debt redemption. Long-term loan rehabilitation. Or a settled exit.
| Mechanism | Governing Section. | Statutory Timeline. | Borrower Protection. | Bank Concession Scope. |
|---|---|---|---|---|
| Section 13(3A) Objection. | SARFAESI Act Sec 13(3A). | Within 60 days of 13(2). | Compels formal 15-day bank reply. halts hasty physical steps. | Correction of ledger errors. Removal of unapplied penal fees. |
| DRT Securitisation Application. | SARFAESI Act Sec 17. | Within 45 days of 13(4). | Interim court stay on auction. Quashes flawed takeover. | Court-directed mediation. Revision of auction reserve price. |
| One-Time closure (OTS). | RBI June 2023 Norms &. Sec 13(8). | Any stage before auction. | Complete debt extinguishment. Fast release of title deeds. | 100% penal waiver. 15% to 45% core rates and balance haircut. |
| Loan Restructuring / Rescheduling. | RBI Prudential rules. | SMA-1 or early NPA stage. | Retains home ownership. Reduces monthly installment burden. | Tenor extension up to 5 years. rates restructuring. |
| National Lok Adalat. | Legal Services officials Act. | Quarterly court sittings. | Final non-appealable award. Zero court fees. Stops lawsuits. | Standardized concession grids approved by zonal boards. |
4. CIBIL Algorithm & Mortgage Debt Closure Dynamics
Defaulting on a secured home loan causes major damage to an person credit profile. Because home loans represent high-ticket facilities. Credit scoring algorithms like TransUnion CIBIL. Experian. CRIF High Mark heavily weight 90+ Days Past Due (DPD) delinquencies. When an account enters NPA status. The client credit score typically plummets from prime tiers (750+) to subprime thresholds (520 to 580). Completely restricting access to bank credit lines.
When concluding a OTS deals on a secured facility. Understanding CIBIL desk reporting nomenclature is critical. If the account is closed under an OTS with a money haircut. The bank reports the account status as Settled or Post-Write-Off Settled. While this mark indicates that the debt was resolved for less than the full contracted balance. It arrests further default reports. Stops ongoing rates accrual. Marks the unpaid late balance as zero. Over a 12 to 24 month period. Disciplined credit rebuilding through secured fixed-deposit credit cards can restore the credit score above 720.
Equally crucial is the claims of original title deeds. Under the landmark Reserve Bank of India directive issued on September 13. 2023. All regulated banks and Housing Finance firms (HFCs) are by law mandated to release all original movable and immovable home papers within 30 days of full loan payment or OTS deals. If the lender fails to return the title papers within this 30-day window. The bank is obligated to compensate the client at ₹5,000 for each day of delay beyond 30 days. Alongside bearing the full cost of reconstructing certified copies in the event of paper loss.
5. Visual 6-Stage SARFAESI Defense & Property Protection Blueprint
Understanding the chronological interplay between bank enforcement powers and client legal remedies is essential for defending your mortgaged home. The full architectural infographic below maps out the 6 pivotal stages of the SARFAESI steps. Highlighting critical legal deadlines. court stay checkpoints. The structured redemption pathway to retrieve original home papers.
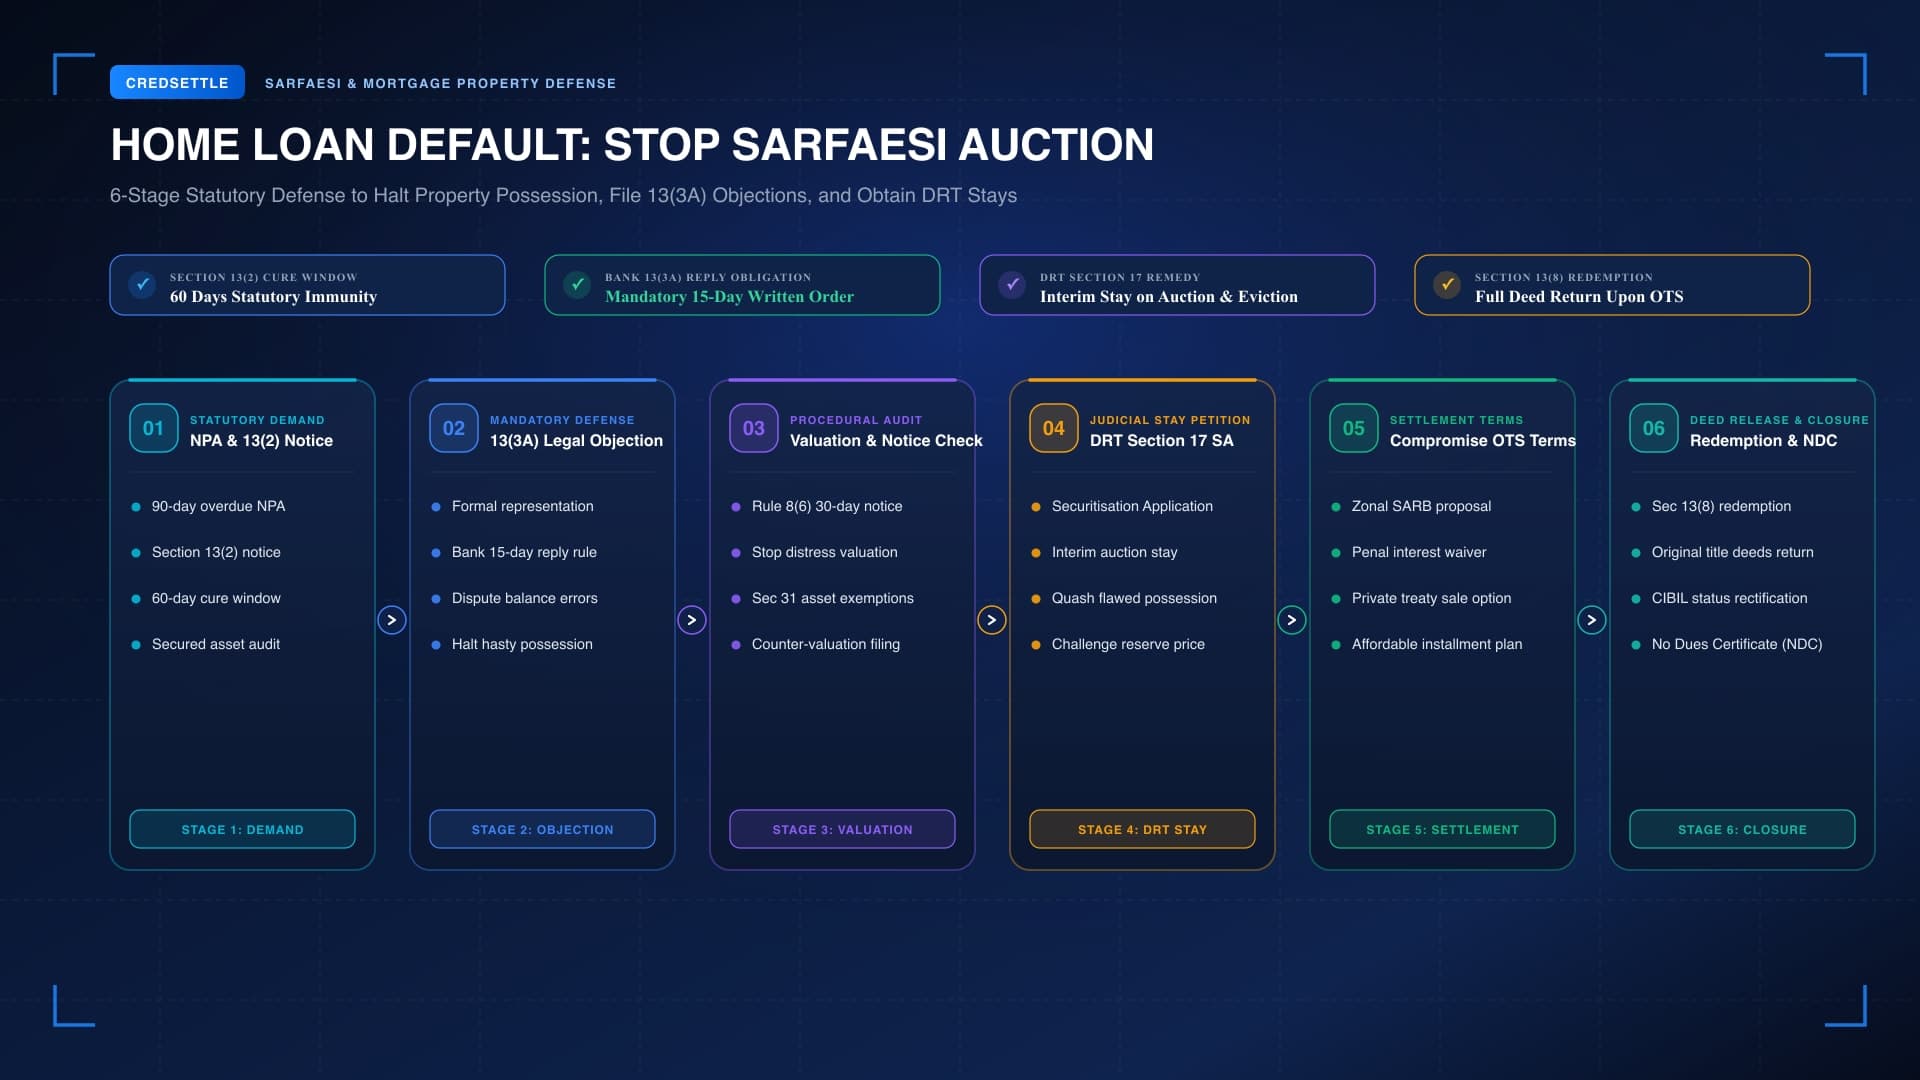
6. The 6-Stage Statutory Defense SOP: From Notice to Deed Release
Navigating a home loan default requires a disciplined legal plan that leverages legal safeguards at every stage. Homeowners often panic upon receiving bank contacts. This allows critical legal timelines to elapse by default. By following this standardized daily work steps. Clients can systematically challenge bank non-compliance. Halt coercive physical takeover. settle an equitable debt relief.
Stage 1: Demand Notice Scrutiny & 60-Day Cure Window Audit
The steps begins when the bank serves a legal demand notice under Section 13(2). Clients must promptly verify the notice validity: confirm that the account was legitimately classified as an NPA after 90 days of steady default. Scrutinize the detailed breakup of main loan. rates. Charges. Confirm whether the pledge rates is registered with the Central Registry of Securitisation Asset Reconstruction and pledge rates of India (CERSAI) under Section 26D. The notice triggers an absolute 60-day legal window during which the bank cannot initiate physical takeover.
Stage 2: Section 13(3A) Formal Representation & Mandatory 15-Day Reply
Within the 60-day period. The client must submit a full written legal help or objection under Section 13(3A). This paper challenges erroneous ledger entries. claims banned compound penalty fees. Asserts bonafide hardship. Proposes a viable restructuring plan. Under the statute. The authorized staff is by law obligated to consider the legal help and communicate a reasoned written order within exactly 15 days. If the bank fails to issue this reasoned reply before steps to takeover. The entire subsequent claims steps becomes by law void.
Stage 3: Property Valuation & Rule 8(6) Statutory Notice Audit
If the bank assumes symbolic takeover under Section 13(4) by affixing a seizure notice. It must comply with Rule 8 of the pledge rates (Enforcement) Rules. 2002. The lender must obtain an objective valuation report from an approved registered valuer before fixing the reserve price. Under Rule 8(6). The authorized staff must serve an person 30-day notice of sale straight to the client before scheduling any public auction. clients can audit the valuation to ensure the home is not being auctioned at an artificial distress price that erodes their total equity.
Stage 4: Filing Section 17 Securitisation Application before the DRT
Once the bank takes any measure under Section 13(4). The client has 45 days to file a Securitisation Application (SA) before the jurisdictional Debt claims Tribunal (DRT) under Section 17. Crucially. Filing an application under Section 17 requires zero strict pre-deposit of the claimed amount. By showing procedural lapses such as failure to reply under Section 13(3A). Undervaluation of the asset. Improper service of the 30-day sale notice. The client can obtain urgent interim stay orders halting public auctions and physical eviction.
Stage 5: Structuring Compromise OTS Terms with Zonal Committees
With legal defenses established and the auction stayed. Talks transition to the bank Stressed Assets relief Branch (SARB) or Zonal closure alert boards. Lenders recognize that prolonged DRT steps and sluggish home auctions tie up bank cash. Clients can propose a structured One-Time closure (OTS) under the RBI June 2023 OTS deal program. Offering an upfront deposit (typically 10% to 15%) with the balance payable in agreed installments. Securing complete waivers of extra fees and legal costs.
Stage 6: Section 13(8) Deed Redemption, NDC, and Bureau Rectification
Under Section 13(8) of the SARFAESI Act. The client holds a legal right of redemption. If the agreed dues or closure sum are tendered before the date of publication of the auction notice. The secured lenders cannot proceed with the sale. Upon realization of the final closure installment. The bank must issue an full No Dues letter. Withdraw all pending Section 14 and DRT steps. Release original title deeds within 30 days under RBI mandates. Update CIBIL desk records.
7. Statutory Notice Defense & Homeowner Safeguards
The SARFAESI Act balances the lenders right to speedy debt claims with constitutional protections under Article 300A of the Indian Constitution. This provides that no person shall be deprived of their home save by formal of law. Because summary enforcement bypasses court trials. The Supreme Court of India has repeatedly held that banks must adhere strictly to every procedural requirement of the statute. Any failure by the lender to follow legal rules renders the claims steps banned and liable to be quashed.
A critical distinction exists between symbolic takeover under Section 13(4) and physical dispossession under Section 14. When a bank serves a seizure notice under Section 13(4). It merely assumes legal or symbolic control. The bank cannot forcibly break locks. Evict residents. Remove private belongings based solely on a Section 13(4) notice. To obtain physical takeover against an unwilling occupant. The authorized staff must make an application supported by an affidavit to the areas Magistrate (DM) or Chief city Magistrate (CMM) under Section 14.
Before the Magistrate issues a physical takeover order. The staff must verify that the bank has satisfied nine strict legal conditions outlined in the proviso to Section 14(1). These include verifying proper service of the 60-day demand notice. Receipt and disposal of the Section 13(3A) legal help. Valid registration on CERSAI. Absence of full payment. If the bank affidavit conceals facts or misrepresents compliance. The client can challenge the Section 14 application. Delaying physical eviction and creating a vital window to settle OTS deal terms.
8. 3-Tier Grievance Redressal & Legal Escalation Matrix
When confronting coercive steps. Unlawful claims staff abuse. Office non-compliance by bank officials. Clients should execute a structured reports across bank. RBI. And court tiers. Relying solely on verbal arguments with branch managers is ineffective because local managers operate under strict non-special claims targets.
Authorized Officer & SARB
Submit written legal objections straight to the designated Authorized staff. Local Stressed Assets Branch. The bank main loan Nodal staff (PNO). Demand ledger reconciliation and formal recording of OTS deal proposals.
RBI Integrated Ombudsman
If the bank violates the Fair Practices Code. Deploys banned claims staff. Fails to respond within 30 days. File an online reports under the RBI Reserve Bank Integrated staff Scheme (RB-IOS) via cms.rbi.org.in.
DRT & High Court Writs
File a Securitisation Application before the DRT under Section 17 for interim injunctions. In cases of flagrant constitutional violations or tribunal vacancies. Invoke the High Court extraordinary writ police area under Article 226.
9. Chronological Milestones & Legal Defense Timeline
The claims steps under SARFAESI follows a predictable legal calendar. Knowing the exact sequence of events empowers homeowners to anticipate lender steps and deploy legal remedies before deadlines expire.
| default Phase. | Regulatory Event. | Bank Action Scope. | Borrower Legal Remedy. |
|---|---|---|---|
| Days 1 to 90 | Special Mention Account (SMA-0/1/2). | Routine claims reminders. Telephonic notices. Late fee charges. | Request loan restructuring. EMI deferment. Or tenor extension. |
| Day 91 | NPA Classification Trigger. | Account classified as Non-Performing Asset. bank reserves allocated. | Audit ledger balance. Demand record of accounts. Prepare hardship brief. |
| Days 91 to 150 | Section 13(2) Demand Period. | Service of 60-day demand notice demanding entire dues. | File formal Section 13(3A) legal help. invoke 15-day bank reply mandate. |
| Days 151 to 180 | Section 13(4) Symbolic takeover. | Affixing seizure notice. Newspaper publication. Sec 14 DM filing. | File Securitisation Application before DRT under Section 17. oppose DM order. |
| Day 180 onwards | Public Auction &. Redemption. | Rule 8(6) 30-day notice. Rule 9(1) newspaper auction advertisement. | Exercise Section 13(8) right of redemption. execute OTS deal OTS terms. |
10. Specialized Real-World Scenarios & Complex Legal Nuances
Secured home loan defaults often involve complex pledge structures. Third-party rights. developer defaults. Recognizing these unique factual matrices provides decisive legal defenses against summary bank enforcement.
Agricultural Land Exemption under Section 31(i)
Under Section 31(i) of the SARFAESI Act. The provisions of the Act do not apply to any pledge rates created in farm land. In numerous cases where farmhouses. Suburban plots. Mixed-use lands are mortgaged for housing credit. Banks improperly attempt SARFAESI enforcement. The Supreme Court in ITC Limited v. Blue Coast Hotels Ltd reaffirmed that income records determining farm classification at the time of mortgage creation govern exemption. Barring banks from taking summary takeover.
Builder-Buyer Subvention Scheme Defaults
In subvention schemes. Buyers. Developers. Lending institutions enter tripartite pacts where the builder promises to service EMIs until project takeover. When developers abandon construction and default on EMIs. Banks aggressively initiate claims against person homebuyers. High Courts across India. This includes the Delhi High Court in multiple landmark writ petitions. Have granted interim injunctions restraining lenders from coercive SARFAESI steps against innocent buyers who never received physical takeover from defaulting developers.
Protection of Bonafide Tenants under Section 14
Where a mortgaged residential home is occupied by a valid tenant under a registered lease deed executed before mortgage creation. The tenant cannot be summarily evicted by the Magistrate under Section 14. In Harshad Govardhan Sondagar v. International Assets Reconstruction Co. The Supreme Court held that the Chief city Magistrate must determine the validity of the tenancy. The secured lenders can only assume symbolic takeover and landlord rights. Preserving tenant occupation until lawful lease expiry.
Debt Transferred to Asset Reconstruction Companies (ARCs)
When public or private banks cannot recover distressed housing debt. They assign the portfolio to an Asset Reconstruction firm under Section 5 of the SARFAESI Act. ARCs typically acquire these Non-Performing Assets at major discounts. Often paying only 30% to 50% of the book value. Because ARCs acquire the debt at a deep haircut. They possess large trade flexibility to settle attractive One-Time closure OTS deal packages with clients who show verifiable illiquidity.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions
Clear. Authoritative answers to critical questions regarding home loan defaults. SARFAESI steps. DRT stays. And home deed claims.
Statutory Citations & Regulatory Authorities
CredSettle mortgage claims relief and SARFAESI defense steps strictly adhere to legal rules including the Securitisation and Reconstruction of money Assets and Enforcement of pledge rates Act (2002). pledge rates (Enforcement) Rules (2002). claims of Debts and ruin Act (1993). Transfer of home Act (1882). RBI Master Direction on OTS deals (June 8. 2023). RBI Direction on Release of Movable/Immovable home papers (September 13. 2023).