Does Loan Settlement Mean Debt is Forgiven?
Understand the critical legal distinction between debt waiver and forgiveness in India. Learn how the Right of Recompense operates. How to prevent post-settlement ARC claims claims. How to secure an full No Dues letter.
- OTS deal vs. Forgiveness: Settlement legally waives unpaid dues under Section 63 of the Indian Contract Act rather than erasing debt without record.
- Right of Recompense: Recompense clauses apply strictly to firm debt restructuring and cannot be enforced on retail private loans unless explicitly signed.
- No Dues letter (NDC): An authentic. Seal-stamped NDC permanently extinguishes the bank&apos. s contractual claim and bars all future claims.
- ARC Portfolio Protection: Any debt transfer or assignment to Asset Reconstruction Companies post-settlement is legally void under Section 5 SARFAESI.
- CIBIL Status Upgrade: An account marked as ". Settled". Can later be converted to ". Closed". under Section 21 of CICRA 2005.
- Legal Notice Compounding: Lenders are legally obligated to withdraw all Section 138 NI Act and Section 25 PSSA proceedings upon settlement.
- Direct Account Remittance: Settlement funds must always be paid straight into the formal bank loan account. Never to third-party firm accounts.
- RBI Fair Practices Code: Regulated lenders must issue sanction letters on formal letterheads and release all loan papers within 30 days.
1. Debt Forgiveness vs. Loan Settlement vs. Accounting Write-Off
When clients in India face severe hardship due to job loss. Trade bankruptcy. Unexpected medical crises. They often wonder whether reaching an pacts with their bank means their remaining unpaid debt is entirely forgiven. In legal jurisprudence and trade banking practice. Debt forgiveness. Loan settlement. Accounting write-offs are distinct concepts governed by different legal rules and daily work rules.
True debt forgiveness is a unilateral. Voluntary act where a creditor erases an unpaid debt risk without requiring any money OTS deal from the debtor. Typically observed in government-sponsored farm relief schemes. In sharp contrast. A retail loan settlement is a bilateral contract executed under Section 63 of the Indian Contract Act. 1872. Where the lender accepts a mutually agreed lump sum in full satisfaction of a larger debt. The bank agrees to waive a large portion of total penal interest and a fraction of the main loan. The transaction is recorded as a settled loss rather than an absolute erasure of debt risk.
From a banking balance sheet perspective. When an no-pledge private loans or credit card debt crosses the 90-day overdue threshold. It transitions through Special Mention Account stages into a Non-Performing Asset (NPA). Under Reserve Bank of India prudential provisioning norms. Banks must set aside 15% to 100% of their Tier-1 cash against non-performing assets. Because retail private loans lack underlying physical security under the SARFAESI Act. Banks face mounting provisioning burdens and prohibitive legal expenses if they pursue civil claims suits. To optimize cash adequacy ratios and recover fast cash liquidity. Banks actively enter into One-Time Settlements (OTS). While the unpaid differential is written off internally on the bank ledger. The settlement legally discharges the client from any further debt claims once an authentic No Dues letter is issued.
2. Financial Breakdown: Principal vs Penal Inflation
When a client defaults on an no-pledge private loans or revolving credit card. The total claimed balance escalates exponentially due to compounding penalty charges. Overdue interest. office processing fees. Understanding how this balance is constructed is essential to evaluating a genuine OTS deals.
Standard retail loan contracts authorize lenders to levy compounding penal interest ranging from 24% to 36% per annum over and above baseline interest rates of 12% to 18%. Over a typical 180-day default cycle. These ancillary charges can inflate the bank&apos. s demanded payoff to 140% to 170% of the actual released main loan. During structured One-Time talks. Debt relief specialists conduct a audits of the loan ledger to separate the core main loan from artificial interest inflation. This allows clients to settle a realistic settlement figure between 40% and 55% of the overall exposure.
Representative 180-Day NPA Debt Inflation Breakdown
Target Compromise Settlement Outcome
3. Legal Resolution Matrix: OTS vs. Restructuring vs. Court Litigation
When evaluating how to handle unpaid retail private loans or credit card accounts. Clients must compare the money and legal ramifications of each available relief pathway:
| Resolution Route. | Governing Framework. | Financial debt. | Credit Bureau Impact. | Legal Finality & NDC. | Strategic Verdict. |
|---|---|---|---|---|---|
| One-Time Settlement (OTS). | Indian Contract Act, Sec 63 &. RBI Board Policy. | 40% to 55% of main loan (Waives Penal Interest). | Marked as ". Settled". (Can be upgraded to Closed). | fast absolute discharge with formal NDC. | Optimal for severe, permanent hardship. |
| Loan Restructuring. | RBI Prudential relief rules 2019. | 100% main loan + Extended Tenor Interest. | Marked as ". Restructured". (Mild negative flag). | Conditional upon completing extended multi-year EMIs. | Best if money breaks is strictly temporary. |
| Civil Court lawsuits (Order 37 CPC). | Code of Civil Procedure, 1908. | 100% main loan + Court Interest + Legal Fees. | Marked as ". Suit Filed / Decreed". (Severe flag). | Concluded only upon final judgment and decree execution. | Costly and drawn-out for both bank and client. |
| National Lok Adalat. | Legal Services officials Act, 1987. | settled OTS deal sum approved by bench. | Marked as ". Settled via Lok Adalat". | Final non-appealable award with full court sanctity. | Excellent bank route during quarterly sittings. |
| Inaction / Continued Default. | legal Default &. Limitation Act, 1963. | Compounding debt risk at 24% to 36% p.a. | Marked as ". Written Off / Wilful Default". | Zero finality. persistent claims firm abuse. | High risk: triggers legal notices and asset attachment. |
4. CIBIL Algorithm: Bureau Status Upgrade Dynamics
Under the Credit Information Companies (Regulation) Act. 2005 (CICRA). All banks and non-banking money companies operating in India are statutorily required to submit monthly account updates to the four authorized credit information companies: TransUnion CIBIL. Experian India, CRIF High Mark. Equifax. Understanding how credit scoring algorithms treat a settled loan clarifies why settlement is not recorded as clean debt forgiveness.
The standard CIBIL scoring model evaluates five mathematical components: Payment History carries the largest weighting at 35%. Followed by Credit Exposure and use at 30%. Credit History Length at 15%. Credit Mix at 10%. Recent Credit Inquiries at 10%. When an account default reaches 90+ Days Past Due (DPD) and is finalized via a OTS deals. The lender reports the account status as ". Settled". (or ". Post-Write-off Settled". ). This reporting causes an fast score drop of 75 to 120 points and remains visible on credit bureau records for up to seven years.
However. A crucial legal remedy exists under Section 21 of CICRA 2005. A ". Settled". Status confirms that the client no longer owes any unpaid monetary balance to the bank. If the client&apos. S money position recovers in subsequent years. They can approach the original lending institution to pay the previously waived differential amount. Upon receipt of this balance. The bank issues a revised No Dues letter and updates the credit bureaus to change the account status from ". Settled". To ". Closed". , completely restoring long-term borrowing eligibility.
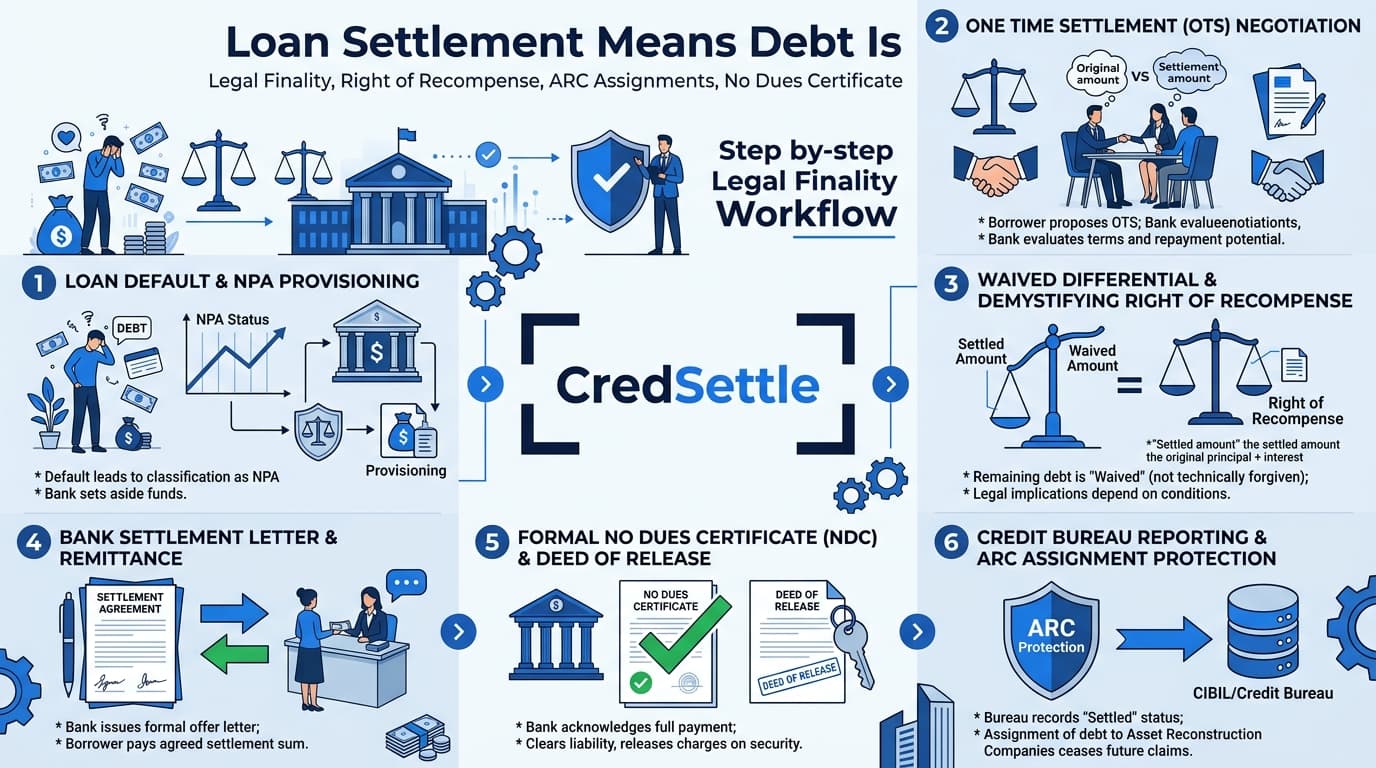
Visual Legal Blueprint: Loan Settlement Finality & NDC Workflow
Examine this visual blueprint illustrating the legal progression from loan default and NPA provisioning to structured settlement. Demystifying the Right of Recompense. Securing the No Dues letter. Blocking third-party ARC claims:
5. SOP: 6 Stages to Secure Legal Finality
To guarantee that your loan settlement achieves permanent legal closure and cannot be reopened by future claims firms or asset reconstruction companies. Follow this sequential 6-stage protocol:
Forensic Debt Ledger & Contractual Audit
Obtain a certified loan account ledger under the Bankers&apos. Books proof Act, 1891. Segregate core main loan from compounding penal interest. Bounce charges. And unapproved office fees to establish your baseline debt risk.
Hardship Dossier Compilation & Financial Evidence
Assemble medical summaries, layoff letters. Bank records, or income tax records. Documenting genuine hardship substantiates genuine bankruptcy. This lets maximum OTS deal concessions from the bank credit boards.
Credit Committee Representation & Right of Recompense Waiver
Submit a formal OTS deal proposal to the bank Competent formal. Explicitly demand total waiver of penalty charges and stipulate that the settlement represents final satisfaction with zero future Right of Recompense.
Bilateral Negotiations & Principal Compromise Structuring
settle straight with the bank claims handling boards. Counter aggressive demands by citing RBI provisioning write-off mandates. Structuring an agreed settlement sum between 40% and 55% of the main loan.
Formal Settlement Letter Vetting & Legal Authentication
Obtain an formal settlement sanction letter on authentic bank letterhead. Verify the OTS deal amount. Payment due dates. Complete balance waiver. Section 138/25 withdrawal terms. 30-day NDC delivery timeline.
Direct Account Remittance, NDC Issuance & Bureau Archival
Deposit funds straight into your loan account via RTGS/NEFT. Collect the seal-stamped No Dues letter and Deed of Release to permanently eliminate future claims and update credit bureau records.
6. Statutory Defenses, Borrower Rights & Regulatory Protections
A common fear among clients is whether creditors can initiate criminal action or coercive claims during or after a settlement. Indian legal law provides explicit legal safeguards that protect clients who enter into legitimate OTS deal pacts:
Failed NACH or auto-debit mandates trigger Section 25 notices. Executing a formal OTS deals requires the lender to cancel active mandates and formally withdraw all pending complaints upon payment.
Cheque dishonour complaints under Section 138 are compoundable under Section 147. A valid closure note must include covenants requiring the bank to file compounding memos and return all security cheques.
Unilateral arbitrator appointments by lenders are void under Supreme Court. Perkins Eastman and TRF Ltd. rulings. Citing Section 12(5) blocks ex-parte awards during active settlement discussions.
RBI prohibits abusive claims conduct. Workplace visits. And calls outside 8:00 AM to 7:00 PM. Continued claims abuse post-settlement is punishable under the RBI Integrated Ombudsman Scheme.
7. The 3-Tier Grievance Redressal & Ombudsman Escalation Matrix
If a bank delays issuing your No Dues letter. Fails to update credit bureau records. Permits claims agents to harass you post-settlement. Escalate through this structured 3-tier RBI hierarchy:
Internal Bank Branch & Grievance Desk Notification
Submit a written complaint to the bank Grievance Redressal Officer attaching the signed closure note and payment receipts to demand fast NDC delivery and cessation of claims contact.
Apex Institutional Nodal Officer Escalation
If unresolved after 10 days. Escalate to the main loan Nodal Officer. Demand core banking account closure and place the institution on notice for RBI non-compliance.
Statutory Complaint via RBI CMS Portal (cms.rbi.org.in)
File a legal complaint on cms.rbi.org.in under the RBI Integrated Ombudsman Scheme 2021 for binding directions and payout for delayed papers or abuse.
8. Procedural Timeline: Initial Default to Legal Closure
Understanding the chronological milestones of debt relief allows clients to execute defenses and settle OTS deals at optimal intervention points:
| Milestone Timeline. | Institutional Status. | Legal Event & Risk. | Strategic Borrower Action. |
|---|---|---|---|
| Days 1. 30 | SMA-0 Classification. | First missed EMI. Soft reminder SMS &. automated calls. | Assess cash flow. determine if hardship is temporary or structural. |
| Days 31. 90 | SMA-1 / SMA-2 Alert. | Compounding penal interest levies. Claims firm assignment. | Request debt restructuring or compile full hardship dossier. |
| Day 90+ | NPA Classification. | Bank sets aside 15%+ cash provisioning. legal notices issued. | Engage legal debt relief specialists to open OTS dialogue. |
| Months 4. 5 | OTS talks Window. | High bank incentive to settle before quarter-end balance audit. | Secure written OTS deal letter with 40%. 55% settlement target. |
| Month 6 | Account Extinguishment. | Remittance processed. legal proceedings formally withdrawn. | Collect authentic No Dues letter &. verify CIBIL update. |
9. Specialized Scenarios: Layoffs & ARC Assignments
Settlement mechanics and legal protections adapt to local debt structures and distress scenarios:
Multi-Lender Portfolio Consolidation & Cross-Default Risks
Settling one account can trigger credit limit reductions across active cards. Executing a synchronized relief plans across all lenders prevents aggressive claims actions by secondary creditors.
Corporate Layoffs & Sudden Loss of Primary Household Income
Furnishing severance notices and provident fund records papers sudden loss of income. This allows debt relief specialists to secure maximum OTS deal waivers from credit boards.
Sole Proprietorship Personal Guarantees & Business Overdrafts
private guarantees for firm loans must be explicitly discharged in the settlement pacts. Confirming zero residual debt risk enforceable against own assets.
Unauthorized Debt Assignment to Asset Reconstruction Companies (ARCs)
If a bank assigns a settled loan to an ARC under Section 5 SARFAESI. Presenting your closure note and No Dues letter legally invalidates the assignment promptly.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions on Loan Settlement & Debt Finality
Click on any question below to view detailed legal answers verified by our debt relief workers:
Official Regulatory Citations & Judicial References
- Indian Contract Act, 1872: Section 63 (Remission of performance and satisfaction of contract by pacts). Ministry of Law and Justice.
- Credit Information Companies (Regulation) Act. 2005 (CICRA): Sections 19. 20. And 21 (Dispute relief and credit report accuracy).
- Reserve Bank of India Master Directions: Master Direction on Fair Practices Code for Lenders and Grievance Redressal Mechanism (Updated 2026).
- Payments and Settlement Systems Act, 2007: Section 25 (Dishonour of electronic funds transfer and compoundable defenses).
- Negotiable Instruments Act, 1881: Sections 138 and 147 (Cheque dishonour and compounding of offenses).
- SARFAESI Act, 2002: Section 5 (Acquisition of rights or interest in money assets by Asset Reconstruction Companies).