Is the Husband Liable for Credit Card Default by Housewife?
Understand your legal protections under the Indian Contract Act. Married Women&apos. S Property Act. And RBI Fair Practices Code. Discover why spousal debt risk is legally separate and how to settle overdue cards with complete legal protection.
- Zero Husband debt risk: Under the Indian Contract Act. Credit card contracts are private to the cardholder. A husband is not legally liable for his wife&apos. s individual debt.
- Husband&apos. s CIBIL Is Unaffected: Credit scores are tracked strictly by individual PAN. A housewife&apos. s default does not impact her husband&apos. s credit profile.
- Strict RBI Ban on abuse: RBI prohibits claims agents from contacting. Calling. Or visiting spouses. Relatives. Or workplaces.
- Asset &. Stridhan Protection: Creditors cannot attach the husband&apos. s salary, savings, or property. A woman&apos. s Stridhan is legally protected.
- 50% to 75% OTS Settlement: Non-earning homemakers qualify for major One-Time Settlement waivers. Finalized with an formal No Dues letter.
1. Spousal Liability: Is Husband Liable for Wife Debt?
In Indian trade jurisprudence. Marriage does not create a joint money entity. When a married woman applies for and is granted a credit card or private loans in her individual name. The legal relationship is governed strictly by the Indian Contract Act. 1872. Under the bedrock doctrine of privity of contract. Rights and dues arising from an pacts exist solely between the contracting parties: the issuing bank and the primary cardholder.
A common misconception exploited by aggressive claims firms is that marriage implies automatic money co-guarantee. Indian law rejects this premise entirely. Unless the husband has explicitly signed the loan pacts as a co-applicant. Primary cardholder. Provided a formal deed of guarantee. He remains a complete stranger to the contract. The lender holds no legal standing to demand payment from the husband. Deduct funds from his bank accounts. Initiate claims steps against his own assets.
also. Ancient concepts such as the doctrine of pious debt under classical Hindu law apply strictly to the moral debt of sons to repay their father&apos. s untainted debts. There is zero legal or customary pious debt requiring a husband to settle his wife&apos. S firm credit debts. Nor does any reciprocal debt exist on the wife. As a result. Credit card arrears contracted by a housewife represent solely her individual civil debt.
2. Indian Legal Framework: Separate Legal Personality
The money independence and separate legal identity of married women are codified under multiple Indian statutes. Most notably the Married Women&apos. S Property Act. 1874 (MWPA) and Section 14 of the Hindu Succession Act. 1956. These legal rules establish that all property acquired by a woman. Whether through inheritance, gifts, private savings. Stridhan received during marriage. Constitutes her absolute and exclusive estate.
Because a woman&apos. s estate is legally segregated from her husband&apos. S estate. Creditors pursuing money claims cannot pierce the marital veil. A bank obtaining an award or civil decree against a defaulted housewife can seek execution solely against assets owned only in her name. The husband&apos. S salary. Expert earnings. Independently purchased residential properties. Vehicles. Investment portfolios are immune from attachment under Order XXI of the Code of Civil Procedure. 1908.
The sole narrow exception recognized in common law is the firm of necessity doctrine. Where a wife purchasing basic life-sustaining necessities such as food or emergency medical supplies without adequate spousal maintenance may pledge her husband&apos. s credit. However. High-interest revolving credit cards. Private loans. Retail purchases. clients durables do not qualify as firm of necessity. banks are fully cognizant of this legal boundary. This is why claims agents often resort to psychological threats rather than legitimate court lawsuits.
3. Debt Resolution Matrix: Legal Relief Mechanisms
When a housewife defaults on credit card dues. Families face several strategic choices. Evaluating these options based on money viability. Spousal insulation. And credit record impact is essential for long-term relief.
| Resolution Pathway. | Financial Relief Target. | Husband Liability Status. | Best Suited For |
|---|---|---|---|
| One-Time Settlement (OTS). | 50% to 75% main loan &. Interest Waiver. | Zero debt risk. completely insulated. | Unmanageable dues with zero independent income. |
| Debt Restructuring / Moratorium. | Tenure extension. zero loan cut. | Zero debt risk unless added as co-signer. | Temporary cash crunch with foreseeable income. |
| Balance Transfer / Top-Up Loan. | Lower APR. shifts debt to new lender. | High risk if husband takes private loans. | Husband voluntarily absorbing the debt. |
| Lok Adalat talks. | 35% to 55% waiver via judicial mediation. | Zero debt risk. formal court decree. | Disputed interest calculations pending in court. |
| Inaction / Continued Default. | Zero relief. 42% APR compounding penalties. | Third-party abuse risks. | Not recommended. worsens credit bureau record. |
4. Credit Score Impact: Wife PAN vs Husband CIBIL
Credit scoring in India operates under the Credit Information Companies (Regulation) Act. 2005 (CICRA). The four licensed credit bureaus: TransUnion CIBIL. Experian. CRIF High Mark. Equifax. Track credit facilities strictly through the client&apos. s Permanent Account Number (PAN). There is no algorithmic mechanism linking marital status. Household addresses. Spousal names into a single consolidated credit profile.
When a housewife defaults on her credit card. The issuing bank reports Days Past Due (DPD) data strictly against her PAN. Her credit score will skill a sharp decline. Typically dropping from a healthy 750+ score to the 550. 620 range following 90 days of steady non-payment. However, her husband&apos. s credit score remains 100% untouched. He can continue applying for home loans. Vehicle financing. Or premium credit lines without any adverse underwriting flags.
Following a successful One-Time Settlement. The card status will be reported to CIBIL as ". Settled". While this prevents active legal claims. It reflects that the balance was resolved for less than the full contract amount. The housewife can systematically restore her credit standing within 12 to 18 months by securing a fixed deposit backed credit card. Maintaining low credit use below 30%. Ensuring flawless payment cycles.
5. Visual Blueprint: Housewife Debt Defense Guide
The visual rules below summarizes the five core legal pillars protecting families against unlawful claims tactics and outlining the bank settlement workflow.
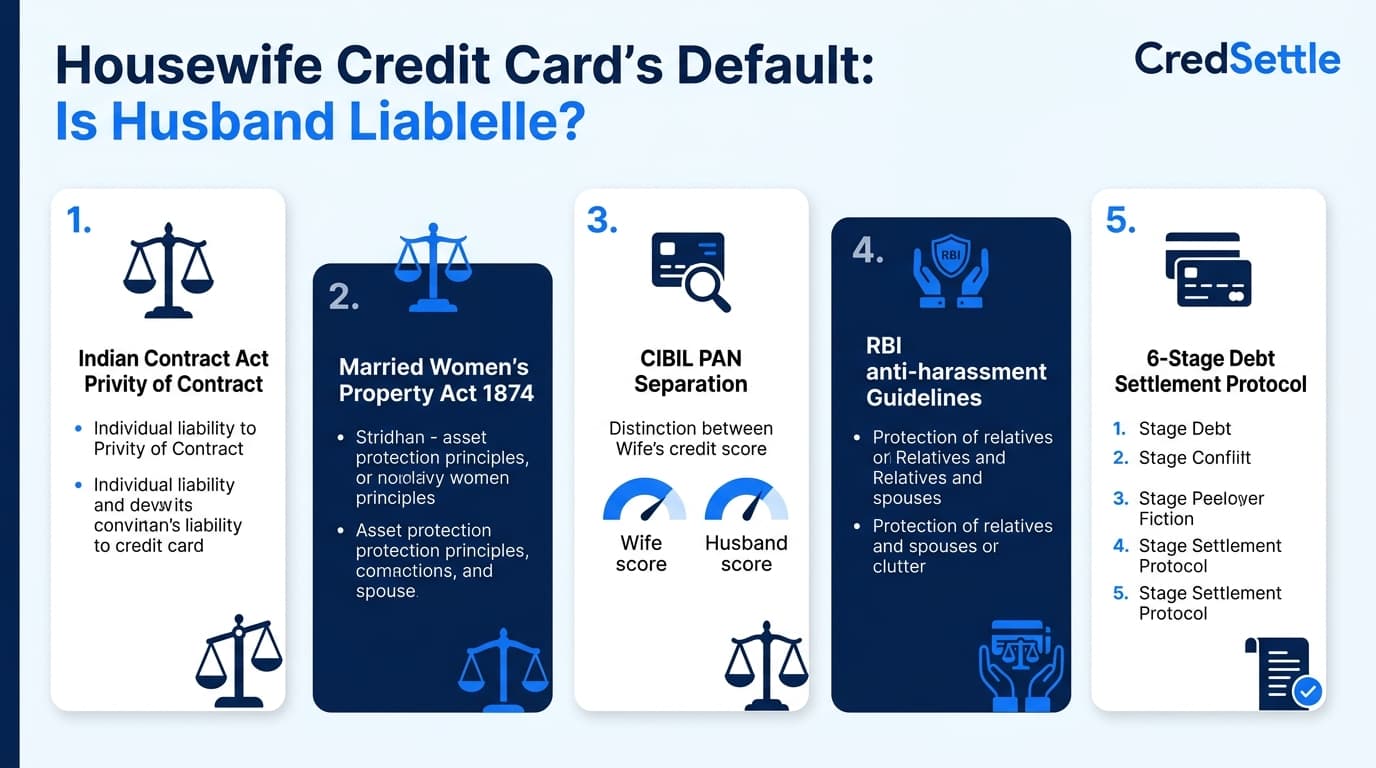
6. 6-Stage Defense Protocol: Settle Housewife Debt
Navigating a credit card default requires a disciplined legal and money plan. CredSettle implements a structured six-stage protocol designed to eliminate third-party abuse. Audit unconscionable fees. Secure permanent money closure.
1Stage 1: Forensic Portfolio & Interest Audit
Our legal desk performs an itemized audit of the card account history. Stripping away excessive compounding late charges. Over-limit penalties. Arbitrary GST components to determine the genuine base main loan.
2Stage 2: Comprehensive Hardship Dossier Compilation
We assemble documented proof showing the homemaker&apos. S lack of independent earning capacity. Medical records. Genuine domestic distress. Establishing that aggressive civil lawsuits would yield zero claims.
3Stage 3: Anti-Harassment Notice & Legal Shielding
We serve formal legal representations to the lender&apos. S legal cell. Directing all contacts to CredSettle and prohibiting calls or visits to the husband. Workplace. Family members under RBI Fair Practices rules.
4Stage 4: Credit Committee Bilateral Negotiations
Our seasoned negotiators engage straight with senior credit boards and stressed asset managers. Leveraging the client&apos. s NPA classification to settle a 50% to 75% OTS deal waiver on dues.
5Stage 5: Settlement Letter Authentication & Legal Vetting
Before any payment is executed. Our attorneys rigorously verify the closure note on formal bank letterhead. Validating authorized signatory credentials, account details. Full debt waiver clauses.
6Stage 6: Direct Bank Remittance & No Dues Issuance
The settled payout sum is remitted straight into the bank&apos. S verified settlement pool account. Followed by formal issuance of the final No Dues letter and closure reporting to credit bureaus.
7. Statutory Defenses: Stop Bank & Agent Harassment
When a credit card defaults. claims departments often deploy deceptive notices to pressure families. Understanding the real legal parameters dismantles these threats tactics.
Section 25 PSSA & Section 138 NI Act
Proceedings for cheque bounce or dishonored NACH auto-debit mandates apply strictly to the local bank account holder who authorized the mandate. If the mandate was linked to the wife&apos. S account. The husband cannot be arrayed as an accused.
Unilateral Arbitration (Section 21)
Under Supreme Court rulings in. Perkins Eastman and TRF Ltd.Banks cannot unilaterally appoint a sole arbitrator to pass ex-parte awards. Any such appointment without mutual consent is legally invalid and challengeable under Section 12(5).
DRT & Civil Recovery Suits
The Debt claims Tribunal (DRT) only exercises police area over debts exceeding ₹20 Lakhs. For smaller credit card dues. Banks can only file summary civil suits under Order XXXVII of the CPC against the cardholder. Never against the spouse.
RBI Fair Practices Code Protections
Under RBI Master Directions. Agents are prohibited from calling before 8:00 AM or after 7:00 PM. Using abusive language, visiting workplaces. Contacting relatives. Violations constitute grounds for RBI complaints and damages.
8. 3-Tier Grievance Matrix: RBI Ombudsman Escalation
If claims agents violate RBI directives by harassing family members or threatening unlawful actions. Clients should initiate formal escalation through the structured three-tier banking grievance mechanism.
9. Default Timeline: SMA Classification to Resolution
Understanding the RBI milestones from initial payment default to full settlement helps families time their talks for optimal money waivers.
| Timeline Phase | Banking Asset Status. | Bank Recovery Action. | Recommended Legal Strategy. |
|---|---|---|---|
| Day 1 to 30 | SMA-0 (Standard Stressed). | Automated SMS, emails, mild follow-ups. | Review finances. assess if temporary or structural. |
| Day 31 to 60 | SMA-1 (Moderate default). | In-house claims calls. late fee additions. | paper contacts. prevent third-party disclosures. |
| Day 61 to 90 | SMA-2 (Severe default). | External firm allocation. legal notices. | Issue anti-abuse shield. begin hardship dossier. |
| Day 90+ | NPA (Non-Performing Asset). | 100% loss provisioning by bank. | Prime OTS talks window. maximum waivers. |
| Day 120 to 180 | OTS deals Phase. | Credit boards reviews OTS proposals. | Vet closure note. Pay funds. Secure formal NDC. |
10. Complex Scenarios: Add-On Cards & Joint Liabilities
Spousal debt debt risk involves nuances depending on how credit facilities were structured. Here are four common real-world scenarios:
Scenario A: Add-On Card on Husband's Account
If the defaulted card was an Add-On card provided to the wife from the husband&apos. S primary credit line. The husband is 100% legally liable for all dues. Under the cardholder pacts. Primary members assume full money responsibility for supplementary users.
Scenario B: Add-On Card on Wife's Account
If the wife is the primary cardholder and issued an Add-On card to her husband. The primary legal debt risk rests strictly with the wife. The husband cannot be sued or forced to pay unless he signed a separate private guarantees pacts.
Scenario C: Joint Co-Borrower Personal Loans
If the husband signed as a co-applicant on a private loans taken alongside his homemaker wife. Debt risk is joint and several. Both parties are equally accountable. And default will straight degrade both individuals&apos. CIBIL scores.
Scenario D: ARC Portfolio Debt Assignments
When banks assign uncollected card debts to Asset Reconstruction Companies (ARCs). claims firms often deploy high-pressure tactics. The underlying legal debt risk remains unchanged: privity of contract still protects the spouse.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions: Housewife Credit Card Debt
Official Regulatory Citations & Statutory References
- Indian Contract Act, 1872: Sections 2(h). 126. 128. And Doctrine of Privity of Contract. Ministry of Law and Justice. Government of India.
- Married Women&apos. s Property Act, 1874 (MWPA): Sections 4. 7. And 8 (Absolute Property Protection and Immunity of Spousal Assets).
- Hindu Succession Act, 1956: Section 14 (Property of a Female Hindu to be Her Absolute Property / Stridhan Inviolability).
- Reserve Bank of India Master Directions: Master Direction on Fair Practices Code for Lenders. claims agents Code of Conduct. Grievance Redressal Mechanisms (Updated 2026).
- Credit Information Companies (Regulation) Act. 2005 (CICRA): Sections 14. 19. 21 (Individual PAN-Based Credit Reporting Regulations).
- Supreme Court of India: Perkins Eastman Architects DPC v. HSCC (India) Ltd. (2020). and TRF Ltd. v. Energo tech Projects Ltd. (2017). (Disqualification of Unilateral Arbitrators).