Can Bank Call Relatives for Loan Recovery?
Are claims agents harassing your kin. Scraping contacts. threatening colleagues? Understand your legal rights rights under RBI rules and stop banned debt claims calls promptly.
- Calling Relatives is Strictly banned: Under Reserve Bank of India Master Directions on Fair Practices Code. Lenders and claims firms are explicitly barred from calling. Messaging. Contacting kin. Friends. Or employers regarding a client&apos. s loan default.
- Constitutional Right to rights: The landmark Supreme Court ruling in. Justice K.S. Puttaswamy v. Union of India. affirms informational rights as a fundamental right under Article 21. Making the non-consensual disclosure of debt to third parties an actionable civil and constitutional violation.
- Zero money debt risk on Non-Guarantors: no-pledge private loans and credit cards are strictly private debts. Relatives, spouses. Parents carry zero legal debt to clear unpaid dues unless they formally signed as joint co-clients or money guarantors.
- online Contact Scraping is a Cyber Crime: loan apps that siphon phone contact lists. Photos. Call logs violate RBI online Lending Directives and Section 43A and Section 66E of the Information Technology Act. 2000.
- penal Penalties for threats: Threatening relatives with arrest. Public shaming. home confiscation triggers fast penal legal steps under Sections 351. 352. 308 of the Bharatiya Nyaya Sanhita (BNS) for penal threats and extortion.
- Reference Contacts are Not Obligors: crisis reference numbers provided during loan application are by law intended only for address trace confirmation and can never be converted into claims targets by claims call centers.
- fast 3-Tier reports Channels: abuse can be halted by filing a formal grievance with the Bank main loan Nodal agents. Registering a cyber reports on portal 1930. Escalating to the RBI Integrated agents on cms.rbi.org.in.
- Permanent relief via OTS deals: Transitioning unmanageable debt into a formal One-Time settlement (OTS) secures a 40% to 70% waiver on accrued extra fees and permanently cancels third-party claims firm mandates.
1. Legal Reality: Can Banks Call Family & Contacts?
When unexpected money stress. Sudden job loss. health crises lead to unpaid private loans installments or credit card dues. Clients often face harsh debt claims tactics. Third-party claims firms routinely resort to calling elderly parents. Spouses, distant relatives. office colleagues. Many clients wonder whether Indian banking laws permit banks to contact their private network to recover late funds.
The unequivocal legal reality under Indian jurisprudence is that banks. Non-Banking money firms (NBFCs). Micro-lending apps have absolutely zero legal approval to contact your relatives. Friends. Or workplace acquaintances for debt claims. A loan pacts is an person bilateral contract between the client and the bank governed by the Indian Contract Act. 1872. Third parties who have not explicitly executed the contract as co-clients or formal legal guarantors carry no money. Moral. Legal debt risk for the unpaid debt.
The Reserve Bank of India has repeatedly issued strict directives through its Master Directions on Fair Practices Code for Lenders. Holding regulated entities straight accountable for the misconduct of their claims agents. The regulator mandates that claims agents must never resort to threats. Abuse. Public humiliation. Breach of customer rights. Disclosing loan default details to kin or calling private contacts is a severe RBI violation that exposes lending institutions to large supervisory penalties and daily work bans.
also. The Nine-Judge Constitution Bench of the Supreme Court of India in. Justice K.S. Puttaswamy (Retd.) v. Union of India (2017). established that the right to rights is an intrinsic facet of the right to life and private liberty guaranteed under Article 21 of the Constitution. Leaking private money records or broadcasting debt defaults to a person&apos. s social circle violates their constitutional dignity. When claims agents use threatening language or threaten relatives with police action. Their conduct crosses from civil default into penal threats under Section 351 and extortion under Section 308 of the Bharatiya Nyaya Sanhita (BNS).
2. Financial Breakdown: Genuine Principal vs Predatory Fees
When a client defaults on no-pledge credit facilities. Banks apply cascading penalty charges. growing fees rates. claims overheads that rapidly inflate the claimed debt risk far beyond the authentic main loan. Within a few months of default. The ledger record swells with growing fees surcharges. NACH bounce penalties. Arbitrary legal fees. Lenders use these inflated figures to exert psychological pressure on clients and their families.
Understanding the mathematical dissection between pure main loan cash and predatory penal inflation is essential for building an effective defense and settling a OTS deals. Once an account reaches Non-Performing Asset (NPA) status after ninety days of steady non-payment. Banks are mandated under RBI prudential norms to make 100% bank reserves against Tier-1 cash. This RBI bank reserves makes banks highly receptive to a One-Time settlement (OTS) that recovers the net main loan while waiving the artificial penal accruals.
Representative 180-Day NPA Personal Loan Settlement Calculation
Target 40% to 55% OTS Waiver.By stripping away banned penal fees and showing genuine debt stress through structured legal representations. Clients can settle late accounts for a fraction of the inflated demand while securing a valid No Dues letter.
3. Debt Resolution Matrix: Legal Relief Mechanisms
When facing harsh claims calls to your kin. You must evaluate the available legal and money remedies. The table below compares One-Time settlement against loan restructuring. Cyber and police reports. Lok Adalat talks. Passive inaction:
| Resolution Route. | Harassment Cessation. | Financial Waiver. | Legal Protection Level. | Resolution Speed. | Strategic Verdict. |
|---|---|---|---|---|---|
| One-Time settlement (OTS). | fast &. Permanent. | 40% to 70% Total Waiver. | Complete civil immunity with NDC. | 30 to 60 Days | Optimal for severe hardship. |
| Loan Restructuring / Moratorium. | Temporary while active. | Zero Waiver (rates Increases). | Conditional on regular EMI flow. | 45 to 90 Days | Viable only if regular income resumes. |
| Cyber Cell &. Police reports. | Stops banned agent calls. | None on underlying loan. | High against penal threats. | 14 to 30 Days | Essential defense against blackmail apps. |
| National Lok Adalat. | Stops all claims action. | 30% to 50% OTS deal. | Binding decree under Sec 21 LSA. | Single-day hearing. | Effective for bank bank claims. |
| Passive Inaction. | abuse Escalates Daily. | Zero (Debt Doubles). | High risk of ex-parte decrees. | Unresolved | Worst approach causing severe damage. |
4. CIBIL Scoring Impact: DPD Tracking & Credit Repair
When loan installments are missed. Credit bureaus such as TransUnion CIBIL. Experian. CRIF High Mark. Equifax recalculate creditworthiness based on algorithmic scoring weights. The standard credit scoring model evaluates five core parameters: payment history (35%). Credit exposure and use (30%). Credit history length (15%). Credit product mix (10%). Recent credit inquiries (10%).
Payment history holds the highest person weighting. Missing consecutive monthly payments triggers Days Past Due (DPD) tracking on your credit profile. Once DPD crosses 90 days. The lender flags the account as an NPA or Sub-Standard Asset. Reducing your credit score by 80 to 140 points. If third-party claims firms initiate civil lawsuits or hearing. Credit algorithms register a severe negative marker that causes loan application rejections across banks.
Section 21 CICRA Remedy & Post-Settlement Credit Rebuilding
Executing a OTS deal One-Time settlement and securing an formal No Dues letter halts further negative DPD reporting. Under Section 21 of the Credit Information firms (Regulation) Act. 2005 (CICRA). Lending institutions are by law required to update credit bureaus within thirty days of settlement. Reflecting the account balance as zero.
While a settled status initially marks the credit history. Clients can systematically rebuild their score to 750+ within 12 to 18 months by maintaining a 100% on-time track record on secured credit cards backed by fixed deposits. Keeping credit use below 30%. Eliminating all uncollateralized revolving balances.
Visual Defense Blueprint: 6-Stage Anti-Harassment Plan
This full visual blueprint details the 6-stage procedural sequence to stop claims calls to relatives. Assert legal rights rights. Achieve complete debt closure:
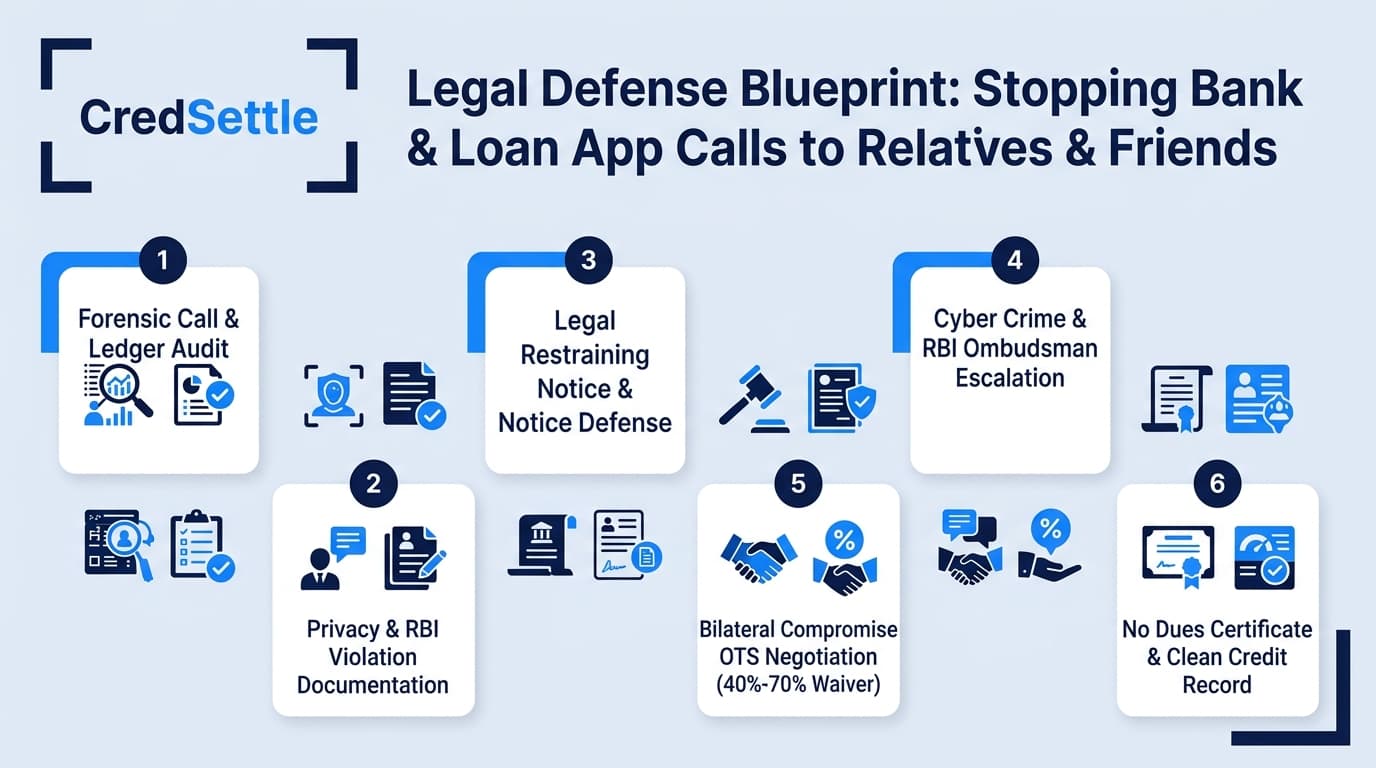
5. Step-by-Step SOP: Stopping Harassment Calls
Follow this sequential standard operating steps to halt banned claims calls to your kin and resolve the underlying debt:
Evidence Logging & Financial Ledger Scrutiny
Preserve all proof of unlawful debt claims. Record abusive phone calls. Capture WhatsApp threats. And log caller phone numbers. Request an audited record of account from the lending institution to identify banned penalty charges and unsubstantiated claims expenses.
Comprehensive Involuntary Hardship Compilation
Compile checked paperwork showing genuine reasons for loan default. This includes hospital discharge summaries. jobs termination letters. Or salary slips showing severe pay cuts. This paperwork forms the foundation of your OTS deals petition.
Statutory Cease-and-Desist Legal Notice
Serve a formal legal notice upon the bank main loan Nodal agents and claims firm. Demand fast cessation of all calls to third parties. Citing RBI Fair Practices Code and Puttaswamy rights rulings. Redirect all formal contacts to your authorized legal agents.
Credit Committee & SAMD Compromise Representation
Our relief specialists present your hardship dossier straight to the bank Credit boards and Stressed Asset handling Division (SAMD). We settle an affordable OTS deals. Seeking a 40% to 70% waiver on accrued extra fees and claims surcharges.
Legal Validation of Formal Settlement Offer
Conduct a deep review of the bank formal closure note. Verify that the paper explicitly states Full and Final settlement. Contains genuine authorized bank signatures. Waives all residual claims. Commits to issuing a No Dues letter upon receipt of funds.
Settlement Execution & Bureau Status Update
pay the agreed settlement funds straight into your checked bank loan account. Secure an formal No Dues letter. Ensure all third-party claims mandates are permanently closed. Confirm that the credit bureaus update your account balance to zero within thirty days.
6. Statutory Notice Defense: Legal Privacy Protections
clients facing harsh debt claims and contact abuse are protected by several legal rules across Indian banking. penal. Civil procedural law:
The Reserve Bank of India mandates that claims agents cannot contact clients before 8:00 AM or after 7:00 PM. Lenders are strictly prohibited from contacting third parties. Misrepresenting debt debts. Using abusive language. Or employing physical threats. Regulated entities face direct supervisory penalties for violations.
When NACH auto-debits or cheques bounce. Lenders may issue legal notices under Section 25 of the Payments and settlement Systems Act or Section 138 of the Negotiable Instruments Act. These steps target only the signatory account holder and cannot be used to harass kin or unassociated contacts.
When banks invoke hearing under Section 21 of the 1996 Act. Unilateral appointments of sole arbitrators are invalid under the Supreme Court ruling in. Perkins Eastman. hearing is strictly a civil steps between signing parties. With zero legal formal to summon or penalize uninvolved relatives.
Abusive claims calls. Morphed images. Threats of violence against relatives constitute penal offenses under Section 351 (penal threats). Section 352 (intentional insult). Section 308 (extortion) of the Bharatiya Nyaya Sanhita (BNS). Punishable with imprisonment and fines.
7. 3-Tier Escalation Matrix: Bank PNO to RBI Ombudsman
If claims callers continue to contact your relatives or reference contacts. Follow this structured 3-tier RBI reports hierarchy to enforce fast compliance:
Internal Institutional Complaint & Agency Recall
File a formal written reports with the bank Grievance Redressal agents (GRO) and main loan Nodal agents (PNO). Submit call records. Specify third-party numbers contacted. Demand the fast withdrawal of the late file from the offending claims firm.
Cybercrime Reporting & Criminal Intimidation FIR
If harsh loan apps or callers use abusive language. Send morphed photos. Threaten relatives. Lodge an fast cyber reports at. cybercrime.gov.in. or dial helpline. 1930. Concurrently file an FIR at your local police station under BNS provisions.
Regulatory Complaint on cms.rbi.org.in
If the bank fails to resolve the grievance within thirty days or provides an unsatisfactory reply. Escalate the claims straight to the. RBI Integrated agents. via cms.rbi.org.in. The agents has the legal formal to award payout up to ₹20 Lakhs for mental anguish and abuse.
8. Procedural Timeline: Default to Complete Debt Relief
Understanding bank claims timelines helps clients anticipate bank actions and structure defense steps effectively:
| Timeline Phase | Loan Classification. | Typical Collection Action. | Strategic Legal Countermeasure. |
|---|---|---|---|
| Days 1. 30 | SMA-0 (Special Mention Account). | Automated SMS. Emails. Tele-calling. | Verify ledger and communicate hardship in writing. |
| Days 31. 60 | SMA-1 Classification. | Third-party firm assignment. | Establish call boundaries and record all contacts. |
| Days 61. 90 | SMA-2 Classification. | Intensified claims and reference calls. | Issue formal cease-and-desist to Bank PNO. |
| Days 91. 120 | NPA (Non-Performing Asset). | Legal notice and OTS OTS deal window. | Initiate bilateral OTS talks for 40%. 70% waiver. |
| Months 4. 6 | Full Closure &. settlement. | Account settled and calls cancelled. | Obtain formal NDC and update CIBIL desk status. |
9. Special Scenarios: Fintech Apps & Contact Scraping
claims abuse manifests differently across credit products. Lending channels. app loans applications:
Illegal Digital Loan Apps Scraping Contact Books
banned 7-day instant loan apps siphon phone contact lists. Photos. messages upon installation. When defaults occur. Syndicates create WhatsApp groups with kin and colleagues to send extortion messages. These entities operate illegally outside RBI oversight and require fast cybercrime reporting (helpline 1930) and device formatting.
Third-Party Recovery Agency Calls to Workplace HR
claims callers often attempt to contact office receptionists. Colleagues. Human resources units to induce fear of job termination. Disclosing loan defaults to employers straight violates RBI Fair Practices rules and creates debt risk for workplace defamation under civil and penal statutes.
Emergency Reference Numbers Given During Application
Lenders often claim that reference numbers provided during loan application signed away their rights rights. by law. Reference contacts are provided strictly for address check at onboarding. Converting reference contacts into claims targets is a blatant violation of lending regulations.
Co-Borrowers vs Non-Guarantor Family Members
If a spouse or kin signed as a joint co-client or formal money guarantor. They share contractual debt risk for the loan. However. Claims agents must still adhere strictly to RBI expert calling hours and decorum standards. With zero tolerance for abusive conduct.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions: Bank Calls & Family Rights
Click on any question below to view detailed legal answers checked by our debt relief workers:
Official Regulatory Citations & Statutory References
- Reserve Bank of India Master Directions: Master Direction on Fair Practices Code for Lenders. Rules on claims agents. Directives on online Lending (Updated 2026).
- Supreme Court of India: Justice K.S. Puttaswamy (Retd.) v. Union of India (2017) 10 SCC 1. (Fundamental Right to rights under Article 21 of the Constitution).
- Bharatiya Nyaya Sanhita (BNS). 2023: Sections 308 (Extortion). 351 (penal threats). And 352 (Intentional Insult to Provoke Breach of Peace).
- Information Technology Act. 2000: Sections 43A. 66E. And 72A (payout for Failure to Protect Data and Breach of rights).
- Credit Information firms (Regulation) Act. 2005 (CICRA): Section 21 (strict Updating of Settled CIBIL desk Records).