RBI Guidelines & Circular for
Bank Loan OTS Settlements.
Understand how Reserve Bank of India OTS deals rules protect distressed clients. Empower banks to grant genuine loan waivers. Provide a lawful path to money claims.
The Reserve Bank of India has established clear RBI rules empowering banks and non-banking money companies to execute OTS deals and One-Time Settlements (OTS) with distressed retail and trade clients.
- Board-Approved OTS Policy: Banks must offer transparent OTS deals under board-approved rules.
- 100% Penal Fee Waiver: Lenders have RBI power to waive total penal interest and legal costs.
- abuse Prohibition: RBI Fair Practices Code strictly bans threatening calls. Abusive tactics, and home visits.
- 30-Day strict NDC: Banks must release full No Dues letters and title deeds within 30 days.
- Direct Bank Remittance: All settlement payments are transferred straight to your bank account via RTGS/NEFT.
1. Debt Economics: NPA Classification & Provisioning
Under the Reserve Bank of India prudential norms. Loan default follows an exact chronological progression. When a client misses scheduled equated monthly installments (EMIs). The account enters the Special Mention Account (SMA) classification. Mainly. Overdue periods between 1 and 30 days are designated as SMA-0. 31 to 60 days as SMA-1. 61 to 90 days as SMA-2. Once main loan or interest payments remain overdue past the critical 90-day threshold. The lending institution is mandated by banking regulation to reclassify the loan as a Non-Performing Asset (NPA).
Classifying a facility as an NPA triggers severe loan loss provisioning requirements under RBI cash adequacy regulations. Banks must set aside Tier-1 cash against doubtful and substandard assets. This straight impacts their profitability and lending limits. For no-pledge credit lines such as credit cards and private loans. Where SARFAESI Act security attachment mechanisms cannot be enforced. Bank claims through civil suits or Debt claims Tribunals (DRTs) typically takes four to seven years. As a result. Banks prefer settling a One-Time Settlement (OTS) under board-approved OTS deal policies. As fast cash realization yields a higher Net Present Value than prolonged court lawsuits.
2. Financial Breakdown: Principal vs Inflated Dues
When a loan account becomes overdue. The unpaid dues shown on claims demand notices rarely reflects the original borrowed sum. Banks automatically apply compounding penal interest. Monthly late payment penalties. Cheque bounce charges. And internal claims overheads. Over twelve to eighteen months of non-payment. These compounding charges can inflate the nominal unpaid dues by 40% to 80% above the genuine main loan ledger balance.
Under the RBI OTS deals rules. Credit sanctioning boards are authorized to dissect the total claim into distinct accounting buckets: original remaining main loan. Regular accrued interest. Penalty charges. In OTS deal talks. The primary objective is securing a complete 100% waiver on all penal interest and late fees. Followed by a settled haircut on the remaining base loan based on verified bankruptcy or medical hardship.
Original main loan.
₹6,50,000
Base borrowed cash.
Inflated Ledger Total.
₹11,40,000
Includes penal interest &. fees.
Penal &. Fee Waiver.
₹4,90,000
100% penal interest waived.
Approved OTS Payment.
₹5,20,000
Full &. final closure amount.
3. Resolution Comparison: OTS vs Litigation Pathways
clients dealing with severe debt burdens often wonder whether they should request a One-Time Settlement. Restructure their ongoing loan. Settle through a National Lok Adalat. Defend in court. Evaluating each legal mechanism against cost. Relief speed. Credit standing provides total clarity on the optimal claims roadmap.
| Resolution Route. | Financial Waiver. | Turnaround Time | Legal Protection. | Credit Bureau Tag. |
|---|---|---|---|---|
| OTS deal OTS (RBI Policy). | 40% to 75% Total Debt Relief. | 30 to 60 Days | Complete civil discharge &. NDC. | Settled / Post-Write-Off. |
| Loan Restructuring. | 0% Waiver (Tenure Extended). | 45 to 90 Days | Contract remains fully active. | Restructured Account. |
| National Lok Adalat. | 30% to 60% Waiver. | Quarterly Court Sittings. | Binding civil court decree. | Settled via Lok Adalat. |
| Civil Court lawsuits / DRT. | Zero (Compound Interest Adds). | 3 to 7 Years | High lawsuits costs &. risk. | Suit Filed / Willful Default. |
4. CIBIL Scoring Math: Post-Settlement Credit Rebuilding
Credit scores generated by TransUnion CIBIL. Experian. Equifax. CRIF High Mark are calculated using proprietary mathematical algorithms based on five core statistical parameters: payment history (35%). Credit exposure and use (30%). Credit history duration (15%). Credit mix between secured and no-pledge debt (10%). Recent hard inquiry frequency (10%).
When an account is settled under an RBI OTS policy. The lending institution updates the bureau with a ". Settled". Tag and reports the waived main loan as written off. This results in an fast 50 to 120 point deduction on your credit score. However. This is greatly less damaging than maintaining an open ". Default". Or ". Written Off". account. This degrades your score continuously each month. By settling the account. You cap further credit damage. Halt negative reporting. Establish a stable baseline to rebuild your CIBIL score back above 750 over 12 to 24 months through secured credit instruments.
RBI Compromise Settlement & OTS Execution Framework
formal six-stage structured protocol for debt audit. Talks, and formal loan closure.
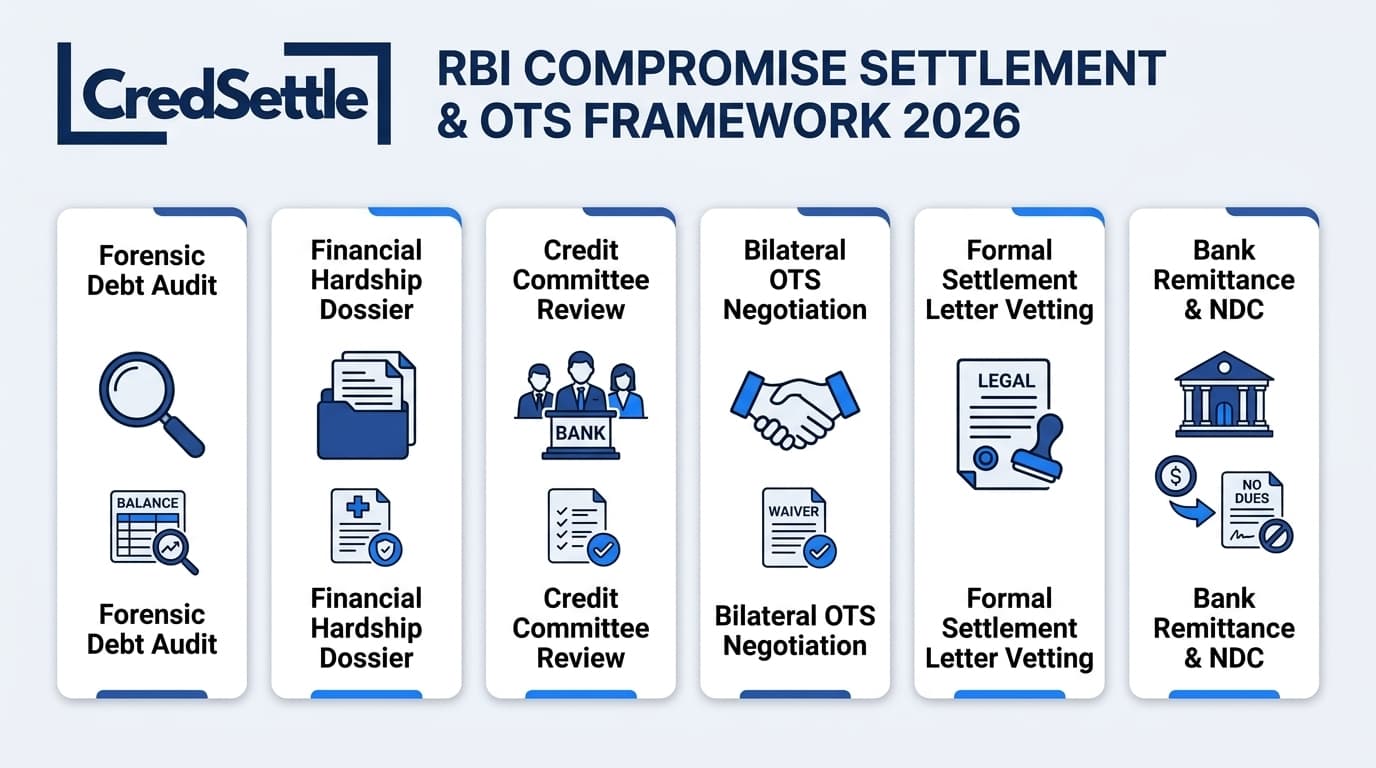
Figure 1: CredSettle procedural legal help of the RBI Prudential relief &. OTS deals rules.
5. Step-by-Step SOP: 6-Stage Compromise Settlement Protocol
Navigating an bank One-Time Settlement under the RBI OTS deals Circular requires strict adherence to banking protocols. CredSettle implements a structured six-stage standard operating procedure designed to eliminate illegal fees. Present verified economic hardship. Secure an ironclad No Dues letter straight from the bank.
Our legal team extracts your full account record. Isolating the true remaining main loan from inflated compound interest. Bounced cheque levies. Arbitrary claims surcharges to determine the actual legal base debt risk.
We compile verifiable documentary proof of involuntary economic distress. This includes medical discharge summaries. Termination letters. Or audited balance sheet declines. Establishing genuine non-willful default status.
A formal legal help is submitted straight to the bank&apos. S Zonal or National Stressed Asset Settlement boards. Showing why an fast OTS deals provides superior claims value compared to prolonged lawsuits.
Our senior debt relief specialists engage in rigorous bilateral talks with bank credit officers. Countering aggressive claims demands and securing maximum permissible waivers under board policies.
We review the formal OTS deal approval letter issued on bank letterhead to confirm explicit full-and-final settlement clauses. Verified payment milestones. strict commitments to withdraw legal proceedings.
You pay the settled payout sum straight to the bank via RTGS or NEFT. Our advocates follow up to ensure the prompt issuance of your full No Dues letter within the legal 30-day window.
6. Statutory Notice Defense: Borrower Legal Protections
When loan defaults occur. Banks often issue legal notices under various Indian legal provisions. Understanding your legal rights under each statute prevents panic and empowers you to respond effectively through authorized legal legal help.
Dishonour of automated electronic clearing mandates is a bailable legal offense under Section 25 of the Payment and Settlement Systems Act. 2007. Establishing demonstrable hardship and submitting an active OTS proposal provides valid legal grounds to resolve the underlying debt.
Cheque bounce notices require a formal response within 15 days of receipt. Section 138 matters are compoundable under Section 147 of the NI Act. Meaning the criminal complaint is promptly withdrawn upon executing a formal OTS deals with the bank.
Unilateral arbitrator appointments by lenders are void ab initio under Supreme Court rulings in Perkins Eastman and TRF Ltd. Clients can challenge unilateral arbitration notices. Compelling banks to engage in genuine bilateral OTS deal discussions.
For dues exceeding ₹20 Lakhs before Debt claims Tribunals. Filing a written record along with an OTS application under RBI rules creates a strong bank record. Encouraging banks to settle rather than incur years of tribunal fees.
7. 3-Tier Escalation Matrix: Institutional Grievance Redressal
If a bank officer acts arbitrarily. Demands illegal charges. Fails to adhere to RBI OTS deals rules. Clients have access to a structured three-tier legal escalation pathway.
Submit a formal written complaint to the bank&apos. s Branch Manager and designated Grievance Redressal Officer (GRO). The bank is required to respond within 7 to 10 working days.
If unresolved. Escalate the grievance to the bank&apos. s main loan Nodal Officer (PNO) at the company headquarters. The PNO possesses executive formal to review offers and correct daily work errors within 14 to 21 days.
If the lender fails to resolve the issue within 30 days or rejects a valid settlement arbitrarily. Lodge a formal escalation on the RBI Complaint handling System at cms.rbi.org.in for binding RBI adjudication.
8. Procedural Timeline: Delinquency to Settlement NDC
A structured overview of the typical default timeline. RBI milestones. Optimal intervention windows under the Reserve Bank of India rules.
| Timeline Stage | Regulatory Milestone. | Bank Action | Optimal Borrower Strategy. |
|---|---|---|---|
| Day 1 to 30 | SMA-0 Classification. | Automated SMS and reminder calls. | Evaluate payment capacity or initiate restructuring. |
| Day 31 to 90 | SMA-1 and SMA-2 Classification. | Internal claims follow-ups initiated. | Audit account ledger and gather hardship proofs. |
| Day 91 to 180 | NPA Classification. | 15% strict provisioning allocated. | Prime window to submit formal OTS proposal. |
| Month 6 to 9 | OTS deal OTS Approval. | Sanction letter issued &. remittance received. | Receive full No Dues letter (NDC). |
9. Specialized Scenarios: Layoffs, ARCs & Multi-Lenders
Debt relief dynamics differ across money situation. CredSettle designs tailored legal plans to match local real-world client situations.
Salaried individuals facing sudden job cuts or salary reductions can present formal severance records to secure extended EMI moratoriums or settled OTS waivers of 50% or more on unpaid private loans.
Proprietors and small shop owners dealing with supply chain breaks or unpaid client receivables can leverage the RBI MSME Restructuring rules to achieve structured debt write-offs without asset liquidation.
clients servicing multiple credit cards and instant digital app loans benefit from coordinated bilateral settlements across all lenders simultaneously. Preventing cascading legal notices and restoring peace of mind.
When banks sell stressed loan portfolios to ARCs at deep discounts. Our negotiators leverage the lower acquisition cost to secure large settlement discounts between 50% and 75% for the client.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions: RBI Loan Settlement & OTS
Authoritative answers to common legal and procedural questions regarding Reserve Bank of India OTS deals rules and One-Time Settlements.