Lok Adalat vs DRT for Loan Settlement: Which Option Is Better?
Struggling to choose between Lok Adalat talks and Debt claims Tribunal proceedings for your loan default? Compare legal formal, waiver percentages. Decree finality. And money timelines to pick the ideal legal path.
1. Legal Foundations: Lok Adalat vs Debt Recovery Tribunal (DRT)
When loan accounts encounter non-payment extending past the 90-day threshold. Reserve Bank of India prudential norms classify them as Non-Performing Assets (NPAs). This classification mandates that banks and NBFCs allocate large Tier-1 cash provisioning to offset balance-sheet risk. To recover cash and de-clog their distressed portfolios. Banks must select an appropriate legal forum based on the loan structure. Security availability. Total unpaid debt quantum.
For debts of ₹20 Lakhs and above. Banks routinely invoke Section 19 of the claims of Debts and Bankruptcy (RDB) Act. 1993. By filing an Original Application (OA) before the Debt claims Tribunal. The DRT is a specialized judicial body designed to expedite claims by bypassing ordinary civil courts. In contrast. For smaller retail loans. Credit card balances. High-volume NPA batches. Banks often approach the National Lok Adalat. Organized under the Legal Services officials Act. 1987.
The foundational divergence lies in judicial philosophy. The DRT functions as an adversarial tribunal where both parties present proof. Submit formal pleadings. Contest legal technicalities under procedural rules. Conversely. Lok Adalat is an Alternative Dispute relief (ADR) mechanism based entirely on mutual talks and equitable settlement. Understanding this structural difference enables clients to choose whether to engage in rapid talks or leverage formal procedural defenses to settle a discounted One-Time Settlement (OTS).
2. Financial Breakdown: Waiver Percentages and Claim Economics
A primary consideration for any client navigating debt relief is the achievable discount on total total dues. When a loan defaults. Banks automatically compound contractual interest. Penal interest. Bounce charges. Office overheads. Inflating the total demand by 40% to 70% over the original base loan. How these inflated claims are settled differs drastically between Lok Adalat and DRT.
During National Lok Adalat sittings. Banks operate under special NPA claims mandates approved by their board boards. In this forum. Bank agents are authorized to waive up to 100% of penal surcharges. Total interest. Even a portion of the original main loan to achieve fast cash claims. In DRT matters. However. Lenders often pursue the entire inflated figure until the client files a robust Written record challenging compounding practices under Supreme Court rulings. Once challenged. Banks settle a OTS deal OTS. Generally yielding 40% to 60% total relief.
Comparative Settlement Scenario: ₹25 Lakhs Defaulted Unsecured Loan
Note: Final figures depend on hardship paperwork. Loan age, and credit boards approval. All payments must be deposited straight to the bank against a formal written sanction letter.
3. Legal Forum Matrix: Lok Adalat vs DRT vs Other Recovery Paths
To make an informed decision on your debt relief plan. It is critical to compare Lok Adalat and the Debt claims Tribunal alongside alternative claims methods such as civil summary suits. Arbitration. Direct bilateral talks:
| Resolution Forum. | Pecuniary Jurisdiction. | Nature of Forum | Decree Finality & Appeal. | Court Fees | Target Settlement Waiver. |
|---|---|---|---|---|---|
| National Lok Adalat. | Any Value (No Limit). | Consensual ADR | Non-Appealable Civil Decree. | ₹0 (Zero Fee) | 50% to 75% Total Relief. |
| Debt claims Tribunal (DRT). | ₹20 Lakhs &. Above. | Adversarial Judicial. | Appeal to DRAT (25%. 50% Deposit). | Ad Valorem Tribunal Fee. | 40% to 60% OTS deal OTS. |
| Summary Civil Suit (Order 37). | Below ₹20 Lakhs | Civil Court lawsuits. | Regular Appeal in areas / HC. | Full State Court Fee. | 35% to 50% via Consent Terms. |
| Arbitration Tribunal. | Contractual Threshold. | Private Arbitral Body. | Section 34 Petition in Civil Court. | Arbitrator &. Admin Fees. | 30% to 45% during proceedings. |
| Complete Inaction / Default. | N/A | Uncontested Default. | Ex-Parte claims letter. | Execution Costs Added. | 0% Waiver (Full Attachment). |
4. CIBIL Algorithm Dynamics & Credit Bureau Restoration
Regardless of whether a settlement is finalized through a Lok Adalat consent award or a DRT OTS deal order. The relief impacts your credit profile across the four Reserve Bank of India authorized credit bureaus: TransUnion CIBIL. Equifax. Experian. CRIF High Mark. Credit scoring algorithms evaluate clients profiles across five primary weights: payment history (35%). Credit exposure and use (30%). Length of credit history (15%). Credit mix (10%). New credit inquiries (10%).
When an account is settled with a partial waiver. Banking software reports the account status as ". Settled". Or ". Post-Settlement Closed". rather than ". Closed". This flag registers a historical credit loss. This causes an initial score drop of 75 to 150 points and restricting fast access to fresh no-pledge credit. However. This is vastly preferable to an open ". Written Off". Or ". Suit Filed". status. This completely freezes loan eligibility.
Under Section 21 of the Credit Information Companies (Regulation) Act. 2005 (CICRA). Lenders are legally required to update bureau databases within 30 days of receiving settlement consideration and issuing a No Dues letter. Clients can restore their credit score above 750 within 12 to 24 months by establishing a new trade line. Using secured fixed-deposit credit cards with use below 30%. Maintaining flawless payment timeliness. Then paying the remaining balance to convert the record from ". Settled". To ". Closed".
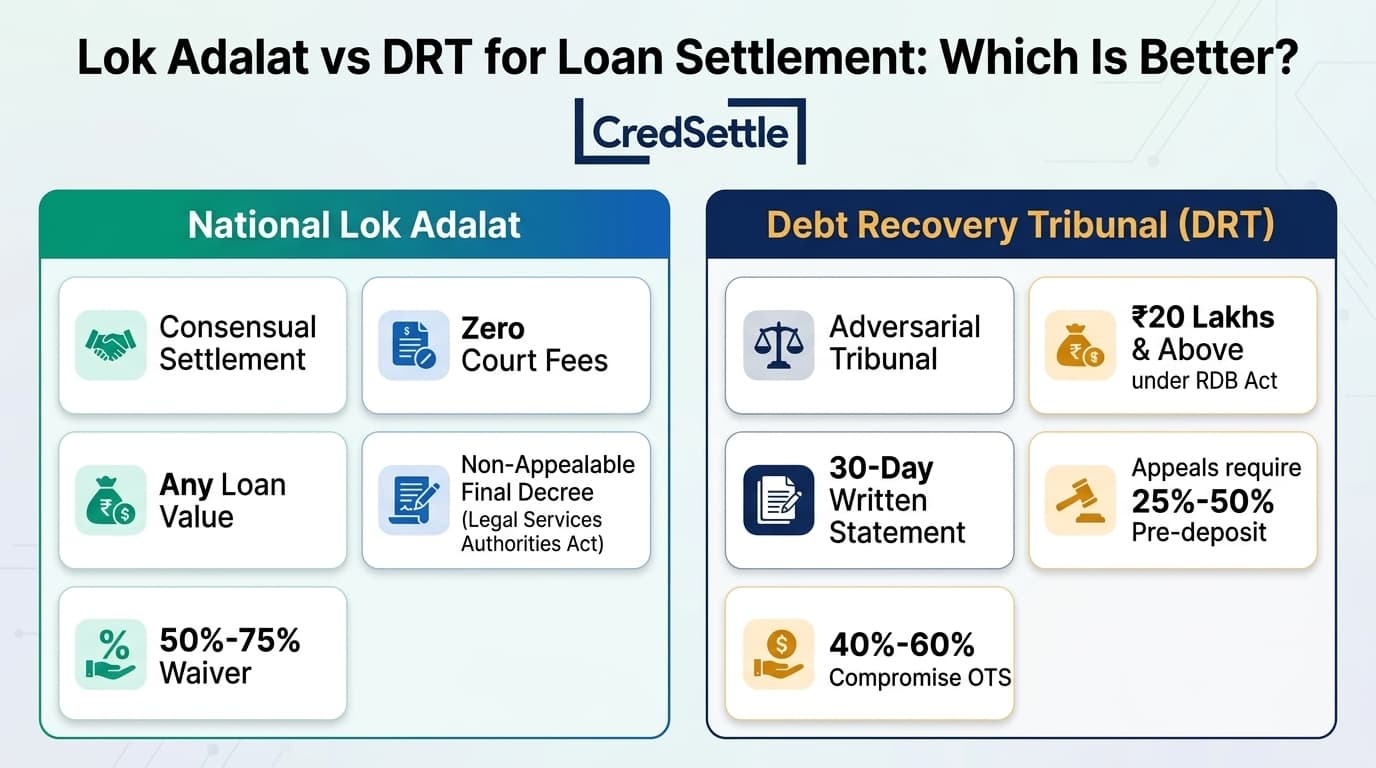
5. Visual Comparison: Lok Adalat vs DRT at a Glance
Review this comparative visual breakdown illustrating jurisdictional limits. Fee structures. Decree finality. Settlement waiver timelines between Lok Adalat talks and Debt claims Tribunal lawsuits:
6. 6-Stage SOP: Choosing and Navigating the Right Legal Forum
Navigating loan relief across either forum demands a disciplined. Step-by-step legal protocol. Follow this six-stage standard operating procedure to maximize waiver margins and safeguard your legal rights:
Debt Exposure Audit & Jurisdictional Assessment
Audit defaulted exposure across lenders to verify if total balances cross the legal ₹20 Lakhs DRT threshold.
Notice Verification & Response Preparation
Verify summons validity, note delivery dates. And track the 30-day response window to prevent ex-parte DRT decrees.
Hardship Dossier & Forensic Ledger Analysis
Assemble income loss and medical proof while auditing loan records to isolate unapproved penal interest compounding.
Forum Appearance & Strategic Negotiations
Attend DLSA talks sittings or submit a formal DRT Written record while initiating bilateral OTS deal talks.
Sanction Letter Vetting & Terms Finalization
Vet the bank sanction letter to confirm full satisfaction. Debt waiver. And strict withdrawal of pending lawsuits.
Direct Remittance, Final Decree & NDC
pay settlement funds straight to the lender. Obtain the final non-appealable award/order. And collect your NDC.
7. Statutory Rights & Legal Defenses Across Forums
clients facing claims actions in either Lok Adalat or the Debt claims Tribunal are protected by robust legal safeguards under Indian law. Whether defending an Original Application or settling in talks. These four legal pillars govern your rights:
Lok Adalat awards carry civil decree status with zero appeal rights. Permanently barring lenders from reopening settled claims.
strict 30-day legal window to file a Written record. Dispute unverified service. And block ex-parte decrees.
Supreme Court ruling barring capitalization of penal interest. Stripping phantom compounding from bank tribunal demands.
Strict prohibition against abusive claims agents. Workplace abuse. Or calling outside authorized RBI hours.
8. 3-Tier Escalation Matrix: Resolving Impasses and Grievances
If you encounter rigid bank claims desks. Incorrect debt calculations. Procedural irregularities during Lok Adalat or DRT proceedings. You should systematically escalate through this established 3-tier grievance matrix:
Internal Bank Escalation & Pre-Conciliation Referral
Submit written representations on ledger errors and request reference to the bank&apos. s Special OTS boards.
Appellate Tribunal Review & Legal Services Oversight
Appeal adverse DRT interim orders before the DRAT (Sec 20) or escalate talks impasses to the SLSA.
Regulatory Complaint on CMS Portal (cms.rbi.org.in)
Lodge RBI complaints for claims abuse. Refusal to honor settlement terms. Or delayed NOC issuance.
9. Chronological Milestones: Default to Final Resolution
The progression from initial loan default to final decree execution follows structured procedural phases across both relief avenues:
| Timeline | Loan Classification. | Lok Adalat Pathway. | DRT Judicial Pathway. |
|---|---|---|---|
| Days 1. 90 | SMA-0 to SMA-2 | Soft claims calls &. reminders. | Internal bank claims notices issued. |
| Days 91. 180 | NPA Classification. | Account referred to DLSA Pre-Lok Adalat list. | Legal demand notice under Section 138/PSSA/DRT. |
| Months 6. 9 | Sub-Standard Asset. | Pre-talks meetings &. OTS talks. | Section 19 OA filed in DRT (₹20L+ loans). |
| Months 9. 12 | Doubtful Asset | Final consent award executed on Lok Adalat day. | 30-day Written record filed &. OTS talks open. |
| Months 12. 24 | Loss / Deep NPA | N/A (Dispute already permanently closed). | Joint OTS deal Terms filed. DRT case closed. |
10. Real-World Scenarios: Which Forum Should You Choose?
Every client&apos. s money and legal situation are unique. Consider these four agent real-world scenarios to determine the most advantageous forum for your situation:
Clear Preference for Lok Adalat
Ideal for credit cards and retail loans below ₹20L with zero court fees and fast 50%. 75% debt waivers.
DRT Defense Combined with Parallel OTS
File a 30-day Written record to block ex-parte orders while settling a OTS deal OTS with the Zonal boards.
Deep Discount Settlements via Conciliation
ARCs buy distressed debt at steep discounts and often approve 60%. 75% cash settlements for quick closure.
Hybrid Resolution Strategy
Settle smaller facilities swiftly in Lok Adalat while dedicating legal resources to defend larger claims in DRT.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
10. Frequently Asked Questions: Lok Adalat vs DRT
Clear. Definitive answers to the most critical legal and money questions surrounding loan settlement through Lok Adalat and the Debt claims Tribunal:
Authoritative Legal Citations & Official Portals
This comparative legal analysis is anchored in the legal rules of the Legal Services officials Act. 1987. The claims of Debts and Bankruptcy Act. 1993. The Credit Information Companies (Regulation) Act. 2005. Authoritative Supreme Court rulings including Central Bank of India v. Ravindra (2002) 1 SCC 367.