Received a DRT Notice for Personal Loan Default? Legal Defense
Have you received a Debt claims Tribunal summons for an unpaid private loans exceeding ₹20 Lakhs? Understand your 30-day legal timeline to file a Written record. Challenge inflated penalty charges. settle a 40% to 60% OTS deals.
1. Debt Economics & DRT Thresholds for Personal Loans
When a client encounters severe debt stress such as firms downturns. Company downsizing. Critical health crises. High-value no-pledge private loans can transition into default. Under Reserve Bank of India prudential norms. Non-payment extending beyond 90 days triggers asset classification from Special Mention Accounts (SMA-0. SMA-1. SMA-2) to Non-Performing Asset (NPA) status. Once classified as an NPA. Lending institutions are statutorily mandated to allocate large Tier-1 cash provisioning. Creating strong balance-sheet incentives for lenders to initiate aggressive claims mechanisms.
For no-pledge credit portfolios where the aggregate defaulted exposure equals or exceeds ₹20 Lakhs. Banks and Non-Banking money Companies (NBFCs) invoke the specialized judicial machinery of the Debt claims Tribunal by filing an Original Application (OA) under Section 19 of the claims of Debts and Bankruptcy Act. 1993. Established mainly to expedite the claims of dues owed to banks and banks. The DRT bypasses standard civil courts.
Because private loans are entirely no-pledge. The lender possesses no mortgage deeds or pledged assets. Making the draconian home seizure mechanisms under Section 13(4) of the SARFAESI Act inapplicable. As a result. The bank must rely only on obtaining a formal monetary decree from the DRT. For the client. This legal distinction offers vital legal leverage. Engaging in strategic legal defense and contesting arbitrary accounting additions creates compelling trade reasons for the bank&apos. s senior credit boards to approve a heavily discounted One-Time settlement (OTS) rather than endure years of contentious tribunal lawsuits.
2. Financial Breakdown: Principal vs Inflated Claims
A primary source of confusion for clients served with a DRT summons is the massive disparity between their original borrowed main loan and the astronomical claim amount demanded in the bank&apos. s Original Application. When an account defaults. Banking software automatically overlays contractual interest with compounded penal interest. Late payment charges. Cheque dishonor fees. Legal processing overheads. Over an 18 to 24 month default cycle. These punitive additions can inflate the total claim by 40% to 75% above the authentic base loan.
The table below presents a realistic money audit of a agent ₹30 Lakhs no-pledge private loans default after 180 days of default. Showing how aggressive bank compounding creates phantom dues and illustrating the target OTS deal OTS window:
Representative Financial Breakdown & Compromise Target
Note: OTS deals are settled on verified hardship proof and legal defenses challenging unapproved compounding. All final payments must be remitted straight to the bank against a formal OTS sanction letter.
3. Legal Forum Matrix: DRT vs Other Recovery Routes
banks select their legal claims avenue based on loan structure. pledge availability. total claim quantum. Understanding how the Debt claims Tribunal operates relative to civil summary suits. hearing tribunals. Lok Adalats. Criminal cheque bounce steps enables clients to formulate an effective legal plan:
| Recovery Forum | Pecuniary Jurisdiction. | Governing Statute. | Arrest / Jail Powers. | Appeal Mechanism. | Key Defense Strategy. |
|---|---|---|---|---|---|
| Debt claims Tribunal (DRT). | ₹20 Lakhs &. Above. | RDB Act, 1993 | NO (Civil Tribunal). | DRAT (Sec 20) with 25%-50% Pre-deposit. | File 30-Day WS. Contest penal interest &. push OTS. |
| Summary Civil Suit (Order 37 CPC). | Below ₹20 Lakhs | Civil steps Code, 1908. | NO (Money claims). | Regular First Appeal (RFA) to High Court. | File Leave to Defend establishing triable issues. |
| hearing Tribunal. | Any Value (Contractual). | hearing Act, 1996. | NO (Private Forum). | Section 34 Petition in main loan Civil Court. | Challenge unilateral arbitrator under Sec 12(5). |
| National Lok Adalat. | Any Consensual Value. | Legal Services Act, 1987. | NO (Pure talks). | Non-Appealable (Final Consent Award). | Execute formal OTS with maximum compound waiver. |
| Cheque Bounce (Sec 138 NI Act). | Instrument Face Value. | NI Act. 1881 / PSSA 2007. | YES (Bailable. Up to 2 yrs). | Criminal Appeal to Sessions Court. | Secure bail. Challenge notice service &. compound. |
| Complete Inaction / Ignoring Summons. | N/A | Default Judgment. | Account Attachment. | High Cost Set-Aside Applications. | Guarantees ex-parte claims letter. |
4. CIBIL Impact & Credit Bureau Restoration Strategy
When a lender files an Original Application in the DRT. The bank Loan Origination System (LOS) automatically transmits high-severity negative reporting to all four licensed credit bureaus in India (TransUnion CIBIL. Equifax. Experian. CRIF High Mark). The credit scoring algorithm weights credit behavior across five standard parameters: payment history (35%). Credit exposure and use (30%). Credit history length (15%). Credit mix (10%). New credit inquiries (10%).
A default transitioning beyond 90 Days Past Due (DPD) results in an fast rating degradation of 90 to 150 points. Once the bank adds a ". Suit Filed (DRT)". Remark. Automated risk-engine models across all Indian banks impose an fast hard block on any future private loans. Credit card. trade credit applications.
Resolving the DRT matter through a settled OTS deal One-Time settlement halts ongoing deterioration. Upon receipt of the settlement consideration and issuance of the No Dues letter. The lender is legally obligated under Section 21 of the Credit Information Companies (Regulation) Act (CICRA). 2005 to update the bureau status to ". Settled". Or ". Post-settlement Closed". within 30 days. While a settled remark remains on the report. The unpaid dues is brought to zero. Stopping active DPD compounding and enabling clients to steadily rebuild their credit profile to 750+ over 18 to 24 months through disciplined secured credit products.
Visual Blueprint: 6-Step DRT Legal Defense Workflow
Examine the full visual roadmap below detailing the step-by-step procedural defense sequence under Section 19 of the RDB Act. 1993. From initial summons check to formal case withdrawal and credit closure:
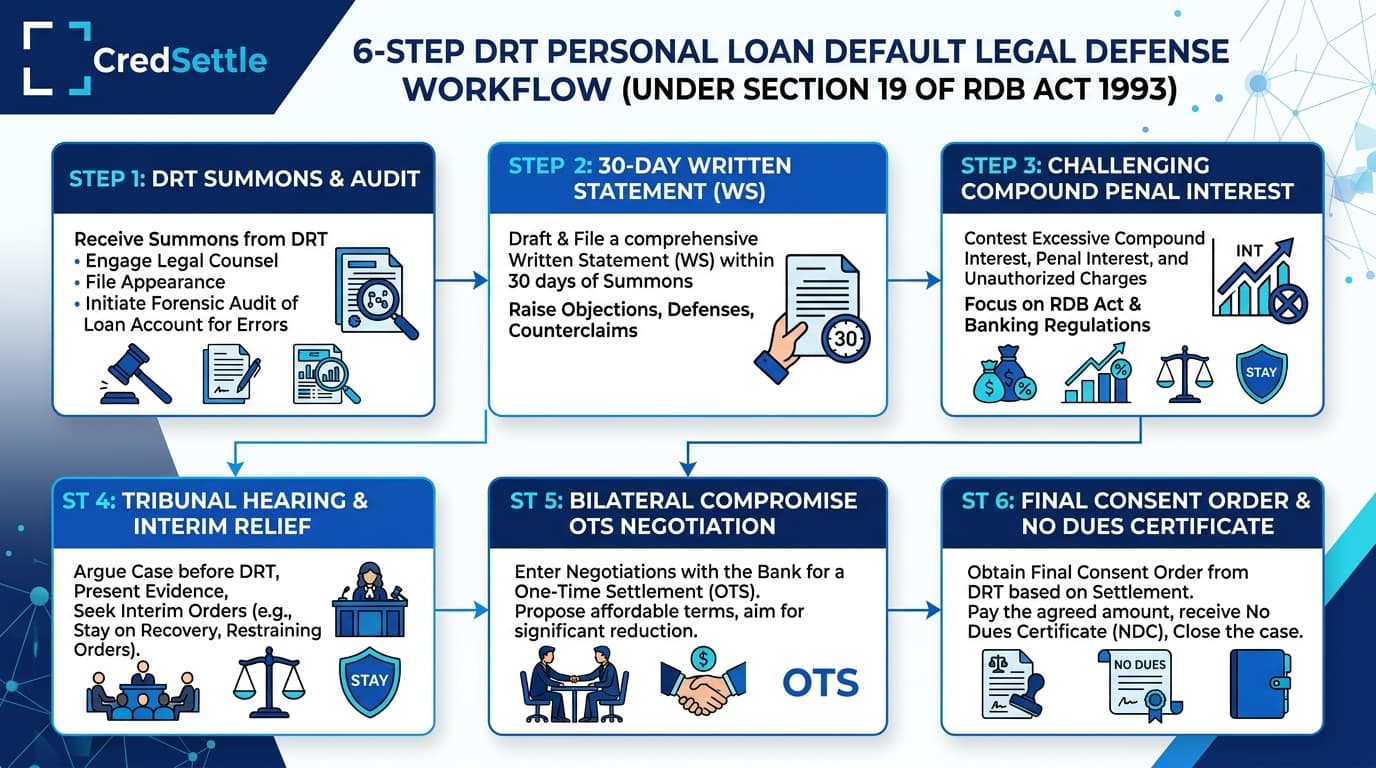
5. 6-Stage SOP: Step-by-Step DRT Defense Protocol
Navigating a Debt claims Tribunal steps requires methodical execution across procedural. Legal. And trade milestones. Follow this six-stage standard operating protocol:
Summons Verification & Loan Document Forensic Audit
Verify the formal service of the DRT summons. Recording the exact delivery date to preserve the 30-day legal response window. Conduct an in-depth audits of the bank&apos. S Original Application. Loan pacts terms. record of account under the Bankers&apos. Books proof Act to isolate unapproved fees and calculation errors.
Drafting & Filing Formal Written Statement (WS)
Prepare a full Written record under Section 19(5) of the RDB Act. Formulate parawise rebuttals to the bank&apos. S allegations. Plead legitimate hardship backed by health or jobs records. Assert legal counterclaims or set-off pleas under Section 19(6) to 19(8).
Challenging Compound Penal Interest & Ledger Calculations
File a dedicated interim application disputing the capitalization of penal surcharges. Cite the Supreme Court Constitution Bench ruling in Central Bank of India v. Ravindra to challenge illegal interest compounding. Forcing the tribunal to direct the lender to submit a revised contractual debt calculation.
Tribunal Appearance & Interim Protection Arguments
Enter formal appearance before the DRT Presiding agents through legal counsel. Contest any interlocutory prayers filed by the bank under Section 19(12) or 19(13) seeking asset disclosure or account freezing. Showing the client&apos. s genuine intent and preventing premature coercive orders.
Bilateral Compromise OTS Negotiation & Approval
Leverage the legal defense and ledger challenges to engage the bank&apos. s Zonal Stressed Assets relief boards. Settle a OTS deal One-Time settlement (OTS) securing a 40% to 60% waiver on inflated dues. Ensuring all terms are formalized in an formal bank sanction letter.
Consent Terms, DRT Case Withdrawal & No Dues Certificate
Upon paying the agreed settlement consideration. File Joint Consent Terms before the DRT. The Presiding agents disposes of the Original Application as settled. Following which the bank issues a final No Dues letter and updates credit bureau records to closed status.
6. Statutory Notice Defense: Section 19 RDB Act Rights
A robust defense against a Debt claims Tribunal summons is grounded in legal procedural safeguards established under the claims of Debts and Bankruptcy Act. 1993 and binding constitutional jurisprudence. When defending against an Original Application for an no-pledge private loans. Clients must assert four primary legal protections:
The statute grants defendant clients an absolute legal right of 30 days to submit a Written record from the date of summons service. Challenging improper substitute service (such as unverified newspaper publications or unsigned electronic notices) preserves your right to contest the case on merits and prevents premature ex-parte decrees.
clients are statutorily entitled to file claims of set-off or counterclaims against the bank within the Written record. Damages arising from unfair banking practices. Illegal debit freeze. Mis-sold loan safety cover can be claimed straight against the bank&apos. s demand balance.
The Constitution Bench of the Supreme Court categorically ruled that lending institutions cannot charge compound interest on penal interest or capitalize punitive charges into the base loan. Pleading this ruling forces the DRT to eliminate inflated compounding additions from the bank&apos. s claim.
Lenders initiating DRT lawsuits are strictly forbidden from employing abusive third-party claims agents. Calling clients at unreasonable hours. Intimidating workplace colleagues under the RBI Master Direction on Fair Practices Code. Making any abuse actionable before the Ombudsman.
7. 3-Tier Escalation Matrix: Institutional Redressal
When facing unyielding bank claims desks or arbitrary procedural actions during DRT lawsuits. Clients should systematically escalate through the formal 3-tier RBI and judicial rules:
Internal Grievance & OTS Compromise Referral
Serve a formal legal help upon the Bank main loan Nodal agents (PNO) and Internal Ombudsman. Highlighting calculation errors and requesting formal reference to the bank&apos. s Special OTS boards or DRT-annexed mediation center.
Appellate Tribunal & Constitutional Remedies
If the DRT passes an adverse or arbitrary interim order. File a legal appeal before the Debt claims Appellate Tribunal (DRAT) under Section 20 of the RDB Act. Invoke Article 226/227 writ police area before the High Court for violations of natural justice or jurisdictional excess.
Regulatory Complaint on CMS Portal (cms.rbi.org.in)
If the lender combines judicial steps with unlawful claims abuse. Third-party disclosure. Refusal to furnish audited account records. Lodge a formal RBI reports on the RBI reports handling System (cms.rbi.org.in) under the Integrated Ombudsman Scheme. 2021.
8. Chronological Milestones: Summons to Final Order
Understanding the chronological progression of an Original Application before the Debt claims Tribunal allows clients to execute their legal defense and talks with tactical precision:
| Procedural Phase. | Tribunal Milestone. | Statutory Limitation. | Strategic Borrower Action. |
|---|---|---|---|
| Day 1 | Service of DRT Summons &. OA Copy. | Section 19(4) service trigger. | Preserve postal envelope. Audit loan ledger &. engage counsel. |
| Days 15. 30 | Filing Written record (WS). | 30 days under Section 19(5). | Submit parawise defense. claims penal rates &. plead hardship. |
| Days 45. 60 | Preliminary Hearing &. Interim Applications. | Presiding agents schedule. | Argue interest re-computation application &. resist asset freeze. |
| Months 3. 4 | OTS deal OTS talks Window. | Bilateral discussion window. | settle 40% to 60% debt waiver with Bank Stressed Asset Desk. |
| Months 5. 6 | Joint Consent Order &. Case Disposal. | Final decree stage. | Pay settlement funds. Obtain NDC &. verify CIBIL closure. |
9. Specialized DRT Scenarios: High-Value Default Defense
High-exposure private loans defaults in the DRT often intersect with complex trade. Organizational. And third-party dynamics. Understanding these specialized scenarios helps clients craft tailored defenses:
Unsecured Jumbo Personal Loans Exceeding ₹20 Lakhs
Salaried executives and workers taking multiple no-pledge jumbo loans (₹25L to ₹75L) during company careers face acute DRT exposure upon sudden job loss or health crises. Because there is no mortgage pledge. Establishing honest inability to pay through bank records and income loss paperwork encourages banks to approve structured OTS deal OTS.
Personal Guarantees for Business Loans in DRT
Directors and trade proprietors who have executed private guarantees for firms credit facilities are often impleaded in Section 19 DRT applications alongside the main loan firm clients. Private guarantors possess distinct legal defenses under Sections 133 to 141 of the Indian Contract Act. 1872 regarding contract variance and lenders negligence.
Debt Assigned to Asset Reconstruction Companies (ARCs)
When banks sell overdue private loans portfolios to ARCs (such as ARCIL. Phoenix ARC. CFM ARC) under Section 5 of the SARFAESI Act. The ARC substitutes itself as the claimant in the pending DRT application. Because ARCs acquire bad loans at steep 70% to 80% discounts on face value. They are exceptionally receptive to fast. Deeply discounted OTS deals.
Consortium Banking & Multi-Lender Claims
Where multiple banking institutions form a claims consortium. person lenders cannot unilaterally proceed without inter-lenders alignment under RBI rules. Clients can propose a unified inter-lenders OTS deal. Consolidating debts under a single structured OTS rules.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions: DRT Personal Loan Notices
Click on any question below to explore authoritative legal answers verified by our banking compliance and debt relief workers:
Statutory References & Official Regulatory Citations
- Claims of Debts and Bankruptcy Act. 1993: Sections 1(4). 19(1) to 19(25). 20. And 21. Ministry of Law and Justice. state of India.
- Supreme Court of India: Central Bank of India v. Ravindra (2002) 1 SCC 367. (Prohibition of compounding penal interest and capitalization of punitive bank charges).
- Reserve Bank of India Master Directions: Master Direction on Fair Practices Code for Lenders. Grievance Redressal Mechanism. And Non-Performing Asset Prudential Norms (Updated 2026).
- Credit Information Companies (Regulation) Act. 2005: Section 21 (strict accuracy. Claims rectification. And timely credit bureau reporting post-settlement).
- Reserve Bank - Integrated Ombudsman Scheme. 2021: legal redressal against unfair debt claims practices and arbitrary penal interest calculations.