Is It Legal to Record Recovery Agent Calls in India?
Understand single-party consent rules. Section 65B and Section 63 BSA electronic proof letters. How to submit recordings against abuse.
- Single-Party Consent: India permits recording claims calls you join in without prior agent notice.
- legal Admissibility: Audio recordings constitute valid proof under Section 65B proof Act and Section 63 BSA.
- Electronic letter Mandate: Submitting audio requires a letter proving device custody and zero tampering.
- penal threats Defense: Recorded threats support police FIRs under Sections 308 and 351 BNS.
- RBI Fair Practices Enforcement: Recorded calling hour violations (outside 8 AM - 7 PM) escalate straight to the RBI agents.
- clients Forum Relief: areas clients Commissions admit checked audio to award mental abuse payout.
- Zero rights abuse: Documenting debt claims calls does not violate Article 21 rights protections.
- settlement Counter-Leverage: Recorded misconduct empowers clients to settle 40% to 55% One-Time deals.
1. Debt Economics, Banking Regulations & NPA Dynamics
When clients default on no-pledge private loans or credit cards due to acute hardship. Lending institutions must adhere to the Reserve Bank of India Prudential rules for relief of Stressed Assets. late accounts transition through successive Special Mention Account classifications: SMA-0 (1 to 30 days past due). SMA-1 (31 to 60 days past due). SMA-2 (61 to 90 days past due). Once default crosses 90 days. The exposure is formally classified as a Non-Performing Asset (NPA).
Under RBI prudential norms. NPA classification mandates Tier-1 cash bank reserves. Starting at 15% for sub-standard assets and rising to 100% for doubtful exposures. Because no-pledge loans lack pledged pledge and are exempt from SARFAESI Act asset seizures. Banks cannot attach homes without civil lawsuits. To reduce cash drag on balance sheets. Lenders outsource calls to third-party claims firms on harsh commissions. This pressure triggers coercive claims tactics. Making audio recording an essential safeguard for clients preparing for OTS deal One-Time deals (OTS).
2. Principal vs Penal Charges and Settlement Math
Following loan default. Lenders inflate unpaid dues by levying compound extra fees (24% to 36% per annum). Late payment charges. office fees. Over a 180-day default cycle. A main loan default of ₹10,00,000 routinely inflates into a gross claim exceeding ₹13,40,000.
Under RBI accounting directives. Penalty fees represent uncollected memorandum charges rather than released cash. In One-Time talks. Banks prioritize recovering core main loan while waiving uncollected extra fees. When clients prove agent misconduct with verifiable audio recordings. Lenders face RBI debt risk. Expediting deal sign-offs.
In a agent 180-day NPA case with a main loan of ₹10,00,000 and ₹3,40,000 in total charges (total ₹13,40,000 claim). An proof-backed settlement typically closes at ₹4,50,000 to ₹5,50,000. Securing an effective 45% to 55% reduction against main loan.
agent 180-Day NPA Settlement Calculation.
3. Strategic Comparison Matrix: Debt Resolution Pathways in India
Evaluating legal and money relief plans for distressed private loans and credit cards:
| Resolution Pathway. | Financial Impact. | Resolution Timeline. | Legal Protection & Risk. |
|---|---|---|---|
| OTS with Audio proof. | 40% to 55% main loan settlement. | 30 to 60 days timeline. | Cessation of abuse. Signed NDC. Zero court visits. |
| Loan Restructuring. | 100% main loan plus rates. | 3 to 5 years duration. | Postpones default. Increases lifetime rates. High re-default risk. |
| Civil Summary Suit. | 100% claim plus 18% rates and court fees. | 3 to 7 years trial. | Lawsuits risk. Potential salary or bank attachment decrees. |
| Lok Adalat | 15% to 30% nominal waiver. | Single hearing day. | Non-appealable award under Section 21 LSA Act. Requires fast payment. |
| Inaction | growing debt. | Indefinite distress. | Severe abuse. CIBIL collapse to 550. Potential ex-parte arbitral decrees. |
4. CIBIL Score Algorithm and Credit Rebuilding Strategy
Credit bureaus in India (TransUnion CIBIL. Experian. CRIF High Mark. Equifax) compute credit scores using proprietary algorithms weighted across Payment History (35%). Credit use (30%). Credit Mix (15%). History Length (10%). Inquiries (10%).
When an account reaches 90 DPD. The payment history component suffers damage. This causes an fast credit score drop of 150 to 220 points. Often plunging a 780 score down to 560. Following a settled settlement. The lender reports the trade line as ". Settled". While this stops further DPD deterioration. The remark indicates past OTS deal.
clients can restore their score back to 750+ within 12 to 24 months through disciplined credit rebuilding steps. Examples include managing a secured card with sub-20% use. Under Section 21 of CICRA 2005. Clients retain the legal right to claims incorrect reporting or convert ". Settled". To ". Closed".
5. Infographic: Single-Party Consent & Evidence Workflow
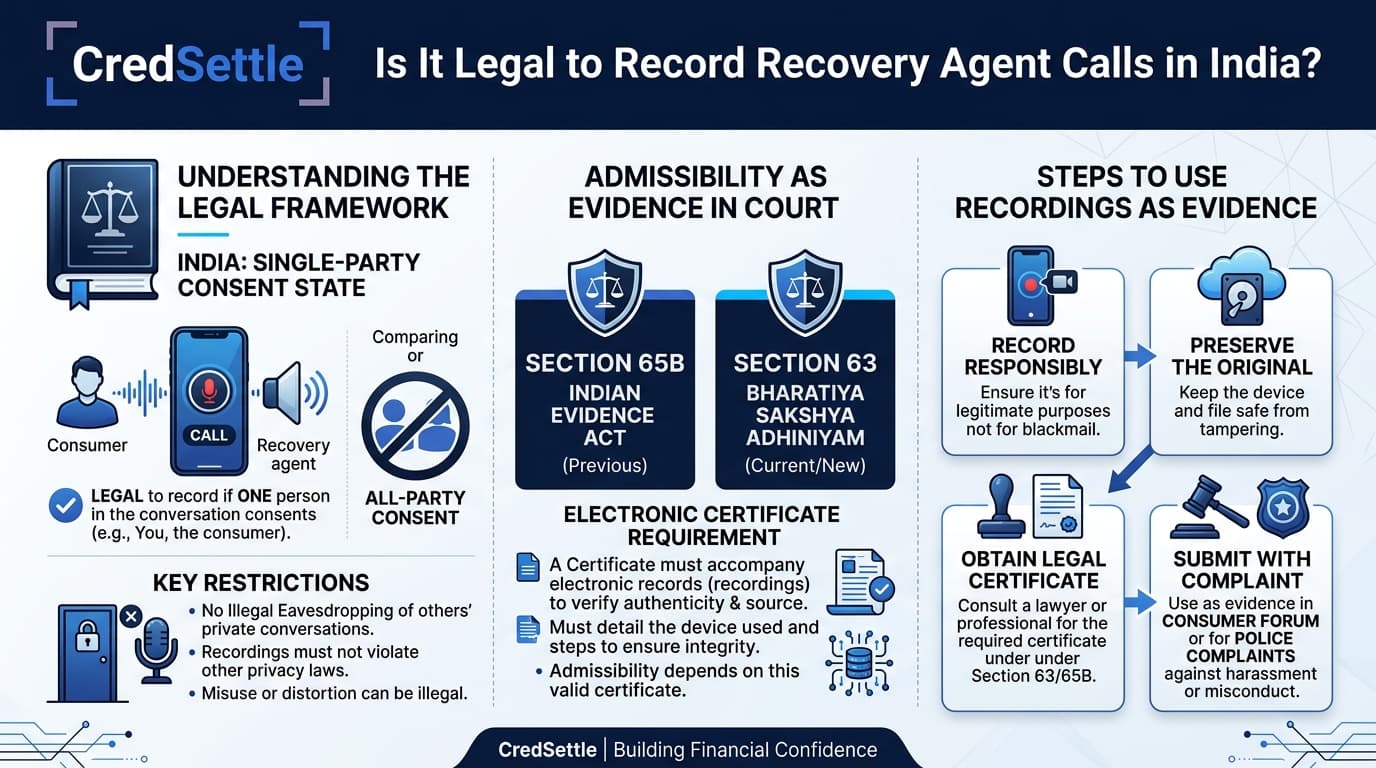
Visual blueprint detailing single-party consent recording rules in India. Section 65B and Section 63 BSA compliance letters. online custody protocols. Multi-forum proof submission channels.
View High-Res6. Step-by-Step SOP: 6-Stage Defense & Evidence-Backed Settlement
Activate native call recording. Save unedited master audio in original formats. Maintain metadata logs detailing timestamps. Caller IDs. And durations to preserve online custody.
Transcribe abusive calls verbatim with exact timestamps. Assemble documented hardship records. Cross-reference recorded agent threats against the RBI Fair Practices Code.
Submit formal legal legal help to the bank Grievance Redressal agents (GRO). Present audited call logs. Verbatim transcripts. And a cease-and-desist notice against third-party outreach.
Leverage recorded audio proof of RBI violations during settlement discussions to settle a complete 100% waiver of extra fees and reduce settlement demands to 40% to 55%.
Review the closure note issued on bank letterhead. Verify covenants including full-and-final discharge of debt. Waiver of remaining balances. And withdrawal of pending legal notices.
pay agreed settlement funds straight into your loan account via RTGS/NEFT. Secure a signed No Dues letter (NDC) and verify CIBIL desk updates under Section 21 CICRA within 30 days.
7. Statutory Notice Defense & Borrower Legal Safeguards
When loans default. Lenders issue legal notices requiring strategic legal responses:
Governs NACH bounces. clients must reply within legal timelines showing lack of fraudulent intent (mens rea) and showing default resulted from genuine hardship.
Governs bounced cheques. Clients must reply within 15 days of notice. Challenging inflated pledge cheque amounts and establishing genuine contractual debt claims.
Under Supreme Court rulings in Perkins Eastman. Lenders cannot unilaterally appoint sole arbitrators. clients can challenge judge eligibility under Section 12(5).
Applies to claims over ₹20 Lakhs before DRT. Under RBI Fair Practices Code. Agents are prohibited from calling outside 8 AM to 7 PM or intimidating relatives.
8. 3-Tier Escalation Matrix: Resolving Recovery Harassment
File a formal reports attaching call recordings and transcripts detailing RBI code violations. relief turnaround is 7 to 10 working days.
If unresolved within 14 days. Escalate to the bank main loan Nodal agents to discipline claims firms and propose structured deals within 14 to 21 days.
If unresolved after 30 days. Lodge an online reports at cms.rbi.org.in or file a petition before the areas clients Commission (DCDRC) for payout.
9. Chronological Procedural Timeline & Resolution Milestones
Procedural milestones from default to relief:
| Timeline Period | default Status. | Recommended Borrower Action. |
|---|---|---|
| Days 1-30 | SMA-0: First missed EMI. Automated SMS alerts. | Activate call recording on phone. |
| Days 31-60 | SMA-1: Third-party firm assignment. Frequent calls. | Maintain call logs. Record interactions. |
| Days 61-90 | SMA-2: Pre-NPA notices issued. | Compile hardship dossier and grievance notice. |
| Days 91-120 | NPA Classification: strict bank reserves triggers. | Formally submit audio proof and propose OTS. |
| Days 121-180 | Bilateral OTS &. Closure: Sanctioned OTS letter (40%-55% waiver). | Pay settlement. Obtain NDC. Update CIBIL. |
10. Specialized Real-World Default & Call Recording Scenarios
Managing complex claims scenarios across varied debt profiles:
clients facing dozens of daily claims calls across multiple cards and loans should centralize audio recordings by lender to maintain consistent proof files.
When harsh agents disregard documented termination letters or health crises. Recorded calls prove the lender ignored genuine hardship.
shop owners facing working cash distress must record calls to prevent banned agent visits to trade premises. Protecting trade goodwill.
When banks assign stressed loans to ARCs under Section 5 SARFAESI. Recording calls ensures firms verify chain-of-title before making claims demands.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions on Recording Recovery Agent Calls
Official Regulatory Citations & Judicial References
- Bharatiya Sakshya Adhiniyam. 2023: Section 63 (Electronic Records Admissibility).
- Indian proof Act. 1872: Section 65B (Electronic proof Admissibility).
- Bharatiya Nyaya Sanhita. 2023 (BNS): Sections 308 (Extortion) and 351 (penal threats).
- Reserve Bank of India: Master Direction on Fair Practices Code for Lenders.
- Clients safety Act. 2019: Sections 35 &. 47 (Banking Deficiency).
- Credit Information firms Act. 2005 (CICRA): Section 21 (claims relief).