IndusInd Bank Personal Loan Settlement
bank rules for resolving late IndusInd Bank private loans and linked credit card debt. Learn how to bypass third-party claims firms. Navigate Circle Debt relief Desks. Secure 40% to 55% OTS waivers with an formal No Objection letter.
- bank Mandate: Adjudicated straight by IndusInd Stressed Asset handling Group after 90 days of default (NPA).
- Zero SARFAESI Risk: no-pledge private credit facilities carry zero pledge mortgage or asset attachment powers.
- 100% Penal Waiver: Complete waiver across growing extra fees. late surcharges. NACH bounce fees.
- 40% to 55% Haircut: Realistic OTS deal target settled straight on core remaining main loan.
- Cross-Facility Consolidation: Combined relief packaging private loans alongside linked IndusInd credit card balances.
- Legal Notice Defense: Timely legal legal replies halt Section 25 PSSA and lawyers demand notices.
- Lok Adalat Accord: Opportunity to secure a non-appealable. Binding court decree under Section 21 of LSA Act.
- Guaranteed Closure: formal bank settlement sanction letter and No Objection letter within 30 to 45 days.
1. Debt Economics & NPA Classification in IndusInd Loans
IndusInd Bank actively disburses no-pledge private loans and premium credit cards to salaried executives and self-employed workers. When unforeseen economic shocks arise. Examples include unexpected firm layoffs. Trade cashflow contraction. Or severe health crises. Servicing monthly equated installments becomes impossible. This leads to rapid default under Reserve Bank of India prudential norms.
late accounts transition through Special Mention Account brackets: SMA-0 (1 to 30 days). SMA-1 (31 to 60 days). SMA-2 (61 to 90 days). Once non-payment exceeds 90 days. IndusInd Bank must classify the exposure as a Non-Performing Asset (NPA). Under RBI cash adequacy norms. This classification mandates setting aside 15% to 25% loan-loss provisions from Tier-1 cash reserves.
Because private loans lack underlying mortgage pledge. IndusInd Bank cannot invoke summary asset seizure under the SARFAESI Act of 2002. trade lawsuits is time-consuming and expensive. As a result. IndusInd Bank Stressed Asset handling Group is commercially incentivized to approve One-Time deals (OTS) to release locked cash and purge non-performing assets from balance sheets.
Understanding IndusInd Loan Charges and Settlement Options
Upon loan default. IndusInd Bank automated banking systems compound ledger balances by levying 24% to 36% extra fees per annum. Recurring NACH bounce charges of ₹500 plus GST. Progressive late fees. Within six months. These artificial non-legal additions inflate the gross ledger claim by 30% to 45% above genuine remaining main loan.
Strategic debt relief starts with deep ledger reconciliation to strip away banned charges. IndusInd Bank credit boards possess the formal to waive 100% of accrued extra fees. Bounce penalties. office fees. When backed by checked hardship paperwork. The bank routinely sanctions a 40% to 55% main loan haircut. Establishing an affordable OTS deal.
| Financial Component. | Pre-Settlement Ledger. | IndusInd Credit Committee Waiver. | Final Payable Amount. |
|---|---|---|---|
| remaining base loan. | ₹7,00,000 | 45% main loan Haircut (₹3,15,000). | ₹3,85,000 |
| Accrued Regular &. extra fees. | ₹2,40,000 | 100% Complete Charge Waiver. | ₹0 |
| Late Surcharges &. NACH Bounce Fees. | ₹60,000 | 100% office Waiver. | ₹0 |
| Total OTS deal Evaluation. | ₹10,00,000 | ₹6,15,000 Total Relief (61.5% Savings). | ₹3,85,000 Final OTS. |
3. Comparative Analysis: IndusInd Bank Debt Resolution Pathways
clients facing debt distress with IndusInd Bank must weigh their legal and money alternatives objectively. While loan restructuring merely extends loan tenors and inflates cumulative rates. Unmanaged default triggers harsh claims abuse and legal notices. An bank One-Time settlement provides superior money relief and complete legal finality.
| Resolution Mechanism. | Financial Relief. | Legal Protection. | CIBIL Bureau Remark. | Standard Timeline. |
|---|---|---|---|---|
| One-Time settlement (OTS). | 40% to 55% Total Reduction. | Complete Discharge &. Notice Withdrawal. | Settled / Zero Balance. | 30 to 60 Days |
| Tenor Restructuring. | 0% Haircut (Higher Cumulative rates). | Conditional upon Regular Servicing. | Restructured Account. | 45 to 90 Days |
| Civil Court lawsuits. | Heavy Legal &. Defense Costs. | Adversarial court Decrees. | Suit Filed / Wilful Default. | 2 to 5 Years |
| National Lok Adalat. | 35% to 50% Mutual OTS deal. | Section 21 Non-Appealable Decree. | Settled in Lok Adalat. | Sitting Date Basis. |
| Unmanaged Default. | Accelerated Penal growing. | Section 25 / Section 138 Warrants. | Written Off / Default. | Indefinite Distress. |
4. CIBIL Scoring Mechanics, Algorithms & Score Rehabilitation
TransUnion CIBIL and peer credit bureaus calculate creditworthiness using five key mathematical pillars: 35% Payment History. 30% Credit Exposure. 15% Credit Age. 10% Credit Mix. 10% Inquiries. Defaulting on an IndusInd private loans damages the 35% payment history pillar. This causes credit scores to plunge by 120 to 180 points.
Executing an authorized settlement prompts IndusInd Bank to update CIBIL desk records to ". Settled". With an unpaid ledger balance of zero. While this reflects a past OTS deal. It permanently halts monthly late Days Past Due reporting and stops harsh claims action.
Rebuilding a 750+ credit score is achievable within 18 to 24 months by using a secured credit card backed by a fixed deposit and keeping credit use below 30%. Under Section 21 of CICRA 2005. Clients can later pay the waived variance to convert ". Settled". Into ". Closed". status.
IndusInd Bank Personal Loan Settlement Roadmap
This dedicated visual flowchart details the six bank phases needed to transition an late IndusInd Bank private loans and credit card account from harsh claims firm abuse into an officially sanctioned. by law binding OTS deals.
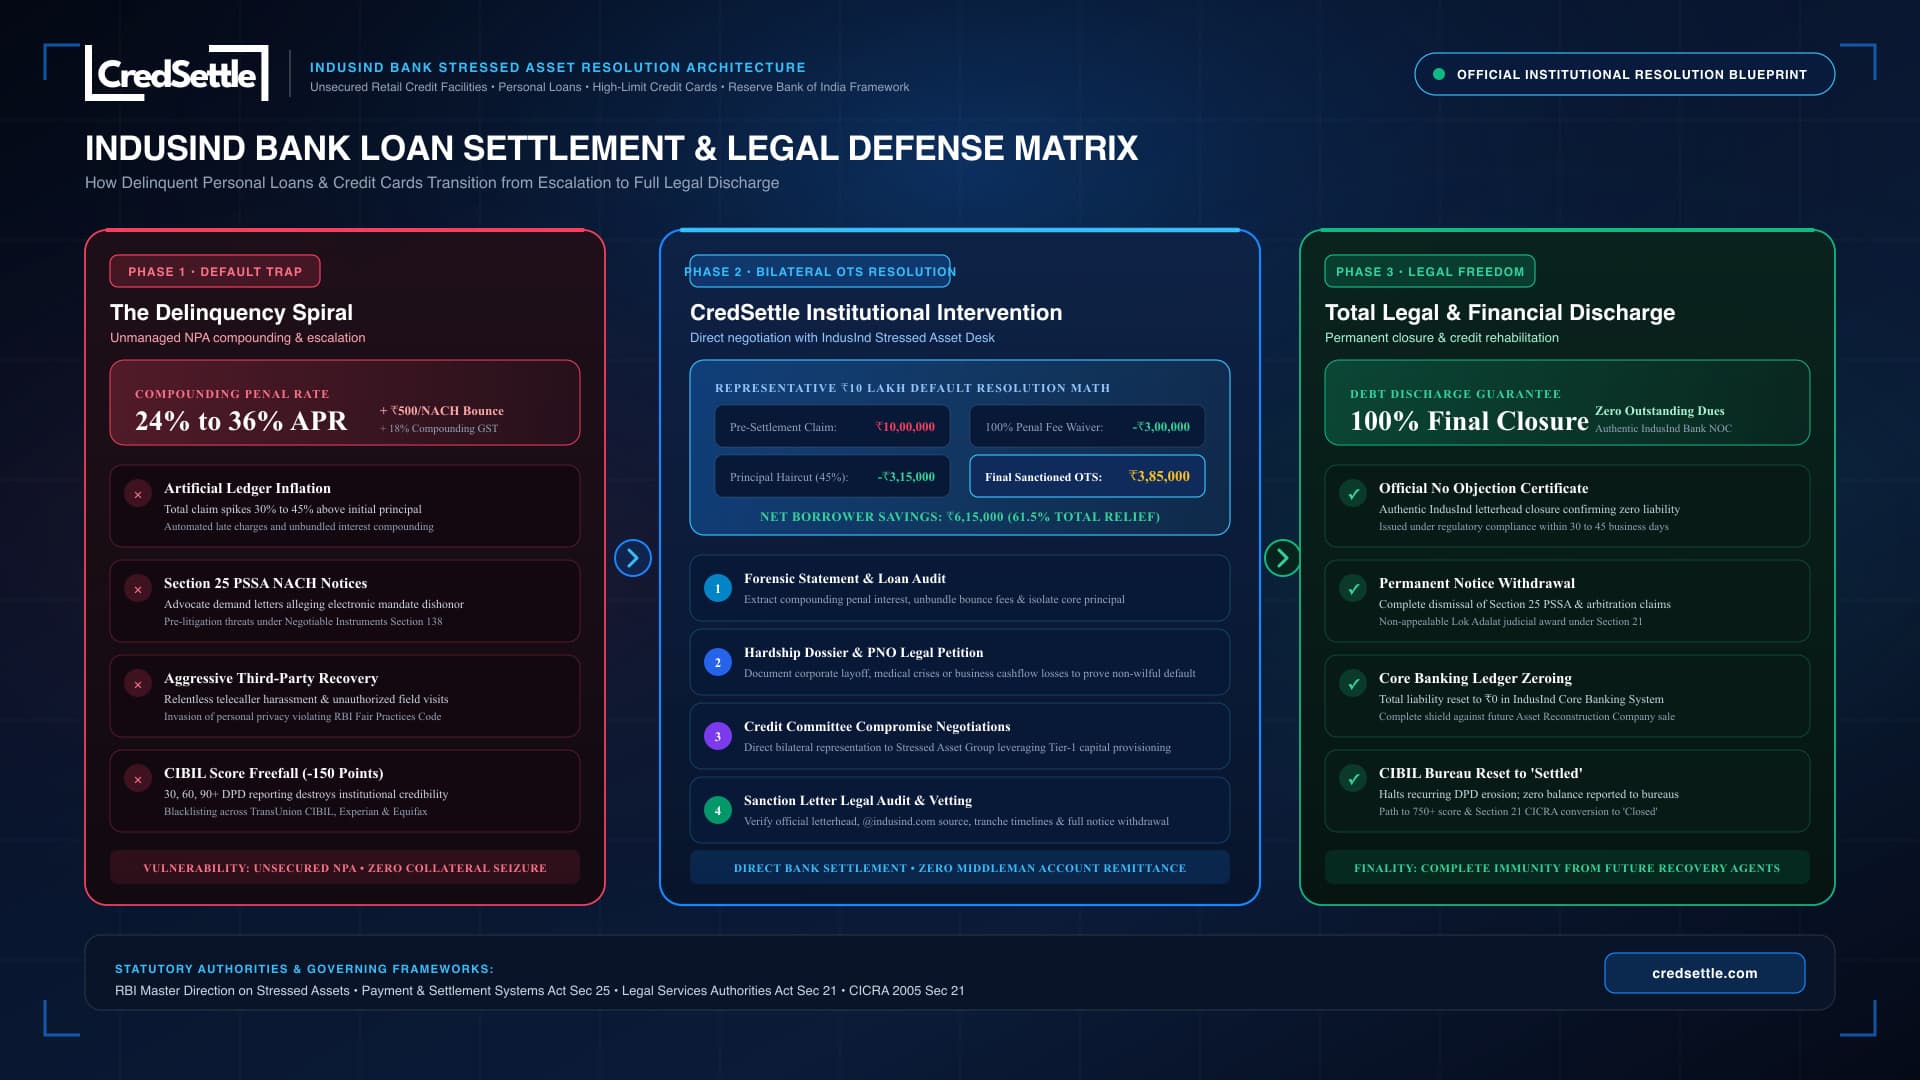
6. Six-Stage SOP: Negotiating IndusInd Bank Personal Loan Settlements
Navigating IndusInd Bank&apos. s settlement hierarchy requires following a structured protocol rather than speaking with third-party telecallers. Adhere to this six-stage bank rules to achieve an authorized OTS deal straight with the bank.
1Stage 1: Forensic Loan Account Audit
Examine complete account records from disbursal. Isolate initial main loan. Deduct cleared EMIs. Unbundle 24% to 36% growing extra fees. Strip away invalid bounce fees to determine the genuine net main loan baseline.
2Stage 2: Comprehensive Hardship Dossier Compilation
Assemble checked paperwork proving genuine debt stress. Compile firm layoff letters. health discharge records. Reduced bank cashflows. Audited trade loss records to prove legitimate non-wilful inability to service the debt.
3Stage 3: Stressed Asset Management Group Representation
Bypass third-party claims vendors by submitting a formal legal legal help to IndusInd Bank Stressed Asset handling Group and main loan Nodal agents. Invoking RBI Fair Practices Code protections and halting banned visits.
4Stage 4: Bilateral Credit Committee Negotiations
Engage in structured OTS deal dialogue with IndusInd circle credit officials. Leverage the lack of mortgaged pledge and RBI NPA bank reserves pressures to secure 100% extra fees waiver and a 40% to 55% main loan reduction.
5Stage 5: Settlement Sanction Letter Legal Vetting
Thoroughly examine the formal sanction letter. Verify that it is printed on formal IndusInd Bank letterhead. Originates from an authorized @indusind.com email. Specifies payment tranches. And guarantees the withdrawal of all legal notices.
6Stage 6: Direct Loan Remittance & NOC Procurement
Deposit the sanctioned payout sum straight into your IndusInd loan account through traceable RTGS or NEFT. Retain stamped bank challans. Confirm Core Banking System ledger zeroing. Obtain the formal No Objection letter within 30 to 45 trade days.
7. Statutory Notice Defense & Borrower Legal Rights
When an IndusInd private loans remains late past 90 days. Empanelled lawyers dispatch legal demand notices. Understanding your legal rights under each notice type eliminates threats and sets the stage for an amicable OTS deal.
Dispatched under the Payment and settlement Systems Act 2007 following electronic mandate dishonor. Serving a formal legal reply within 30 days establishing genuine debt stress disproves fraudulent intent and redirects steps toward an amicable One-Time settlement.
Issued when pledge cheques deposited during loan disbursal bounce. A formal legal reply served through counsel within 15 days establishes that instruments were given as pledge rather than for an ascertained debt. Barring summary magistrate steps.
IndusInd Bank often initiates hearing under Section 21. Following landmark Supreme Court rulings in Perkins Eastman and TRF Limited. Unilateral judge appointments are void. Clients can file Section 12(5) objections. Staying steps and compelling bilateral settlement.
Debts claims Tribunals have police area only over claims exceeding ₹20 Lakhs under the claims of Debts Act. For retail loans. The RBI Fair Practices Code strictly bans claims agents from calling before 8:00 AM or after 7:00 PM. Contacting employers and relatives.
8. Three-Tier Escalation Matrix for IndusInd Bank Grievances
When claims vendors violate conduct rules or local branches refuse hardship representations. Clients must escalate through IndusInd Bank internal grievance mechanisms and RBI oversight channels.
| Grievance Tier | Designated Banking Authority. | Turnaround Time | pay & Scope of Intervention. |
|---|---|---|---|
| Level 1: GRO | IndusInd Grievance Redressal agents. | 7 to 10 Working Days. | Investigation into abusive claims firm conduct. Disputed extra fees charges. And initial settlement review. |
| Level 2: PNO | main loan Nodal agents (Mumbai firm Office). | 14 to 21 Working Days. | Direct RBI review of Fair Practices Code violations. Abuse reports. And referral to circle stressed asset desks. |
| Level 3: RBI agents. | Reserve Bank Integrated agents. | 30 Days Post-PNO. | Binding RBI adjudication through cms.rbi.org.in for severe legal breaches. Predatory claims practices. And unfair banking conduct. |
9. Chronological Resolution Timeline: From Default to NOC
An IndusInd private loans default progresses through local RBI phases. Identifying where your late account sits along this timeline reveals the optimal window for initiating talks to secure maximum main loan waivers.
| Timeline Interval. | Asset Classification. | Bank Recovery Actions. | Recommended Borrower Strategy. |
|---|---|---|---|
| Day 1 to 30 | SMA-0 | Automated SMS alerts. Email reminders. And soft telephonic claims calls. | Assess budget viability. avoid taking fresh high-rates online credit to service EMIs. |
| Day 31 to 60 | SMA-1 | Intensified telecaller outreach and preliminary demand letters from claims teams. | Assemble authenticated hardship proofs including job severance letters and health bills. |
| Day 61 to 90 | SMA-2 | Final pre-NPA warnings and initial allocation of file to external claims firms. | Assert RBI Fair Practices Code rights against banned third-party abuse. |
| Day 91 to 120 | NPA Classification. | Tier-1 cash bank reserves triggered. file transferred to Stressed Asset Group. | Conduct deep account audit and engage bank debt settlement specialists. |
| Day 121 to 180 | Prime OTS Window. | Issuance of Section 25 PSSA NACH notices or pre-lawsuits Lok Adalat summons. | Execute bilateral OTS deal talks targeting a 40% to 55% loan cut. |
| Month 6 and Beyond. | Write-off / ARC Sale. | hearing steps initiated or portfolio assigned to Asset Reconstruction firms. | pay sanctioned payment steps straight and secure formal No Objection letter. |
10. Handling Complex Scenarios: Credit Cards & ARCs
Debt distress rarely follows a uniform pattern. Standard claims approaches fail to address complex multi-product debts and sudden economic shocks. Below are strategic relief tactics for expert IndusInd Bank loan scenarios.
Combined Personal Loan & Credit Card Exposure
clients holding an IndusInd private loans alongside high-limit credit cards face cross-default acceleration. Strategic relief consolidates all no-pledge facilities into a unified dossier. Settling a collective OTS deal to avoid piecemeal lawsuits.
Corporate Layoffs & Sudden Tech Retrenchment
Salaried firm executives often face sudden ruin following workforce reductions. Presenting formal severance letters and depleted bank records proves absence of wilful default. Accelerating credit boards approval for large main loan haircuts.
Business Proprietorship Cashflow Collapse
founders who availed private loans to sustain working cash during trade downturns can establish trade distress through audited money records and GST filings. Proving that non-payment stems from genuine trade loss rather than intentional evasion.
Asset Reconstruction Company (ARC) Portfolio Sales
When IndusInd Bank assigns late private loans to ARCs under Section 5 of SARFAESI. Claims formal transfers. Because ARCs acquire distressed retail debt pools at steep discounts. Seasoned negotiators can achieve deals with total waivers exceeding 60% to 70%.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions: IndusInd Bank Loan Settlement
Clear. by law checked answers addressing the most common client inquiries regarding IndusInd Bank&apos. S private loans steps. Waiver expectations. lawyers legal notices. Lok Adalat steps. Credit score rehabilitation.
Official Regulatory References & Legal Framework
- Reserve Bank of India: Master Direction on Fair Practices Code for banks and Stressed Asset Classification Norms (Updated 2026).
- Payment and settlement Systems Act. 2007: Section 25. Legal rules Governing Dishonour of Electronic Funds Transfer Mandates.
- Legal Services officials Act. 1987: Section 21. Finality and Non-Appealable Status of National and Pre-lawsuits Lok Adalat Awards.
- Hearing and talks Act. 1996: Sections 12(5), 16. 21. Invalidity of Unilateral judge Appointments and Supreme Court Rulings (Perkins Eastman / TRF Ltd).
- Credit Information firms (Regulation) Act. 2005 (CICRA): Section 21. Legal rules for CIBIL desk claims Rectification and Conversion of Account Remarks.