How to Sue Your Bank in Consumer Court for Harassment
clients across India possess enforceable legal rights against unlawful debt claims. banned charges. rights breaches. Learn how to petition the clients Commission. Secure large damages for mental agony. And enforce full debt relief.
- legal clients Rights: clients and cardholders are protected under CPA 2019 Section 2(7).
- Deficiency of Service: Coercive calls. Workplace visits. And abuse violate Section 2(11).
- payout for Agony: Commissions award monetary damages for abuse under Section 39.
- online e-Daakhil Filing: Cases can be filed online via edaakhil.nic.in with zero physical visits.
- OTS closure Leverage: Formal notices prompt bank boards to offer 40% to 65% waivers.
1. Banking Deficiency: Consumer Protection Act 2019
When a client experiences genuine debt stress due to firms slowdown. Severe illness. Unforeseen job loss. Trade lenders often deploy harsh third-party claims firms rather than engaging in constructive debt restructuring. In the Indian legal landscape. Banking services are explicitly covered under the clients safety Act. 2019. Any failure by a bank to maintain expert standards. Protect clients rights. Adhere to the Reserve Bank of India Fair Practices Code straight constitutes a deficiency of service under Section 2(11) of the Act.
The Supreme Court of India has established that lending institutions cannot treat defaulted clients as persons stripped of fundamental dignity. Deploying muscular claims staff. Calling clients before 8:00 AM or after 7:00 PM. Using intimidatory language. Contacting kin or employers. Public shaming represent egregious breaches of service dues. Such steps empower the client to institute formal legal steps before the clients claims Redressal Commission seeking heavy monetary payout. Punitive damages. Permanent injunctions against coercive claims tactics.
2. Financial Damages: Compensation Calculation Math
When filing a clients reports against a lending institution. Complainants are entitled to claim multiple distinct heads of monetary relief. Banks often inflate late accounts by levying excessive extra fees. Compound bounce penalties. And arbitrary claims overheads. Under Section 39 of the clients safety Act. 2019. The clients Forum possesses wide legal powers to order a complete refund of unfair money levies. Award direct restitution. Grant large punitive damages for mental agony and reputational harm.
In a typical clients petition involving an no-pledge loan or credit card debt where unlawful abuse has occurred. The total monetary payout awarded by the Commission regularly exceeds the unpaid contested penal balance. Creating large economic leverage for an affordable OTS deal.
Bank Claimed unpaid.
₹8,50,000
Includes ₹3.2L extra fees &. fees.
True Contractual main loan.
₹5,30,000
Base net disbursement balance.
Claimed Damages in Forum.
₹3,00,000
Mental agony + banned charge refund.
Effective OTS Target (40-55%).
₹2,40,000 - ₹2,90,000.
Full &. final closure with clean NOC.
3. Redressal Comparison: Consumer Court vs Other Forums
Selecting the correct legal forum is vital when confronting harsh banking practices. While the RBI staff provides office relief and police reports handle physical threats. The clients Commission remains the most potent civil tribunal for securing large monetary payout and binding court injunctions against lender malpractice.
| Resolution Pathway. | Governing Statute. | Damages Authority. | Average Duration. | Settlement Impact. |
|---|---|---|---|---|
| clients Court (DCDRC / SCDRC). | Clients safety Act. 2019. | High (Unlimited pecuniary damages). | 6 to 12 Months | Exceptional OTS Leverage. |
| RBI staff (CMS Portal). | RBI Integrated Scheme 2021. | Capped at ₹1 Lakh for mental agony. | 30 to 60 Days | Moderate office Pressure. |
| Civil Court Suit. | Code of Civil steps. 1908. | Full damages subject to high court fees. | 3 to 7 Years | Slow &. Expensive steps. |
| National Lok Adalat. | Legal Services officials Act. 1987. | Zero damages (Consensual waiver only). | Single Day Hearing. | fast Non-Appealable Consent. |
| Inaction / Non-Response. | Default &. NPA rules. | Zero (Escalating extra fees). | steady abuse. | Severe CIBIL Damage &. Legal Suits. |
4. CIBIL Rectification: Enforcing Credit Bureau Updates
Credit scores maintained by TransUnion CIBIL. Experian. CRIF High Mark. Equifax are calculated using advanced proprietary algorithms heavily weighted across five core dimensions: payment history (35%). Credit use ratio (30%). Credit mix duration (15%). New credit inquiries (10%). Total debt exposure (10%). When a bank wrongfully reports a disputed account as willful default or delays reporting an agreed closure. The clients credit score experiences an fast collapse of 120 to 250 points.
Under Section 21 of the Credit Information firms (Regulation) Act. 2005 (CICRA). Credit institutions are statutorily obligated to update accurate account data within 30 days of relief. When banks fail to do so. Clients Commissions regularly issue binding directives ordering fast CIBIL desk data rectification. Deletion of derogatory remarks. Monetary payout of ₹100 per day of delay under RBI rules.
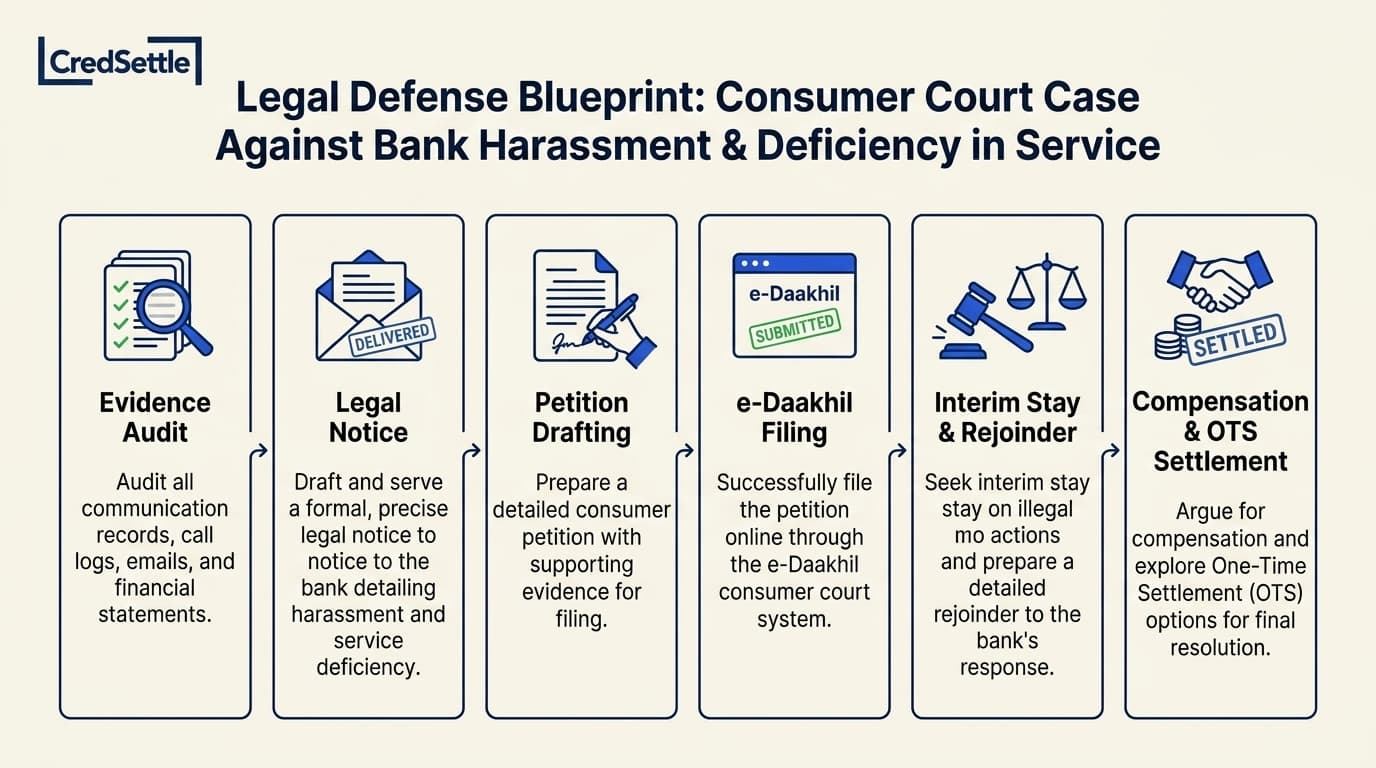
5. Infographic: Bank Harassment Consumer Court Roadmap
The visual rules below summarizes the end-to-end procedural trajectory from proof locking to filing on e-Daakhil and securing enforceable payout orders against banking malpractice.
6. Step-by-Step SOP: 6 Stages to File and Win in Court
Filing an effective clients court reports requires methodical legal execution. Following this standardized six-stage lawsuits protocol guarantees evidentiary integrity. Procedural compliance. maximum closure leverage.
Compile unedited audio recordings of abusive calls. Timestamped call logs. CCTV footage of unlawful visits. Written demands. Certified loan records. Categorize every violation under the RBI Fair Practices Code.
Serve a formal legal notice upon the bank Managing Director and main loan Nodal staff giving 15 days to halt abuse. Correct wrongful charges. Provide a fair relief roadmap before court steps.
Draft the full reports setting out facts. Establishing clients status under Section 2(7). Detailing local deficiencies under Section 2(11). Enumerating itemized claims for payout under Section 39.
Submit the indexed petition along with supporting affidavits and proof on edaakhil.nic.in. Paying the requisite nominal court fee based on the pecuniary police area of the areas or State Commission.
Argue preliminary admission. Obtain an interim stay order against claims staff contact under Section 38(8). Receive the bank written record. Submit a rejoinder dismantling frivolous lender defenses.
Present final arguments to secure an enforceable payout award or leverage the strong lawsuits position to conclude a 40% to 60% One-Time closure with a formal No Dues letter and clean CIBIL reporting.
7. Statutory Legal Rights: Consumer Protection Standards
Indian clients jurisprudence provides strong legal safeguards to shield citizens from firm banking malpractice. Understanding these core legal provisions ensures your defense is rooted in binding legal formal.
reports with consideration paid up to ₹50 Lakhs lie before the areas Commission. Claims between ₹50 Lakhs and ₹2 Crores are heard by the State Commission. Meanwhile. claims exceeding ₹2 Crores reach the National Commission (NCDRC).
Covers any fault. Imperfection. Shortcoming. Or inadequacy in banking quality or manner of performance. Unwarranted calls. rights breaches. And unverified penalty fees automatically constitute actionable deficiency.
Mandates that staff must be police-checked. Carry ID cards. Contact clients only between 8:00 AM and 7:00 PM. Maintain call recordings. Strictly refrain from intimidating or threatening steps.
In ICICI Bank v. Shanti Devi Sharma (2008). The Supreme Court ruled that banks cannot employ musclemen to recover loans and affirmed vicarious debt risk of senior banking handling for staff misbehavior.
8. 3-Tier Escalation: Redressal from Bank to Commission
An orderly reports plan establishes undeniable procedural diligence. This ensures that when your petition reaches the clients Forum. The bank cannot claim lack of notice or internal opportunity to resolve the grievance.
Bank GRO & PNO
Submit a formal grievance to the bank Grievance Redressal staff (7 to 10 days) and escalate to the main loan Nodal staff (14 to 21 days) demanding fast stoppage of claims misconduct.
RBI Ombudsman (CMS)
Lodge a online reports on cms.rbi.org.in if the bank fails to resolve the claims within 30 days. Invoking the Integrated staff Scheme 2021 for bank accountability.
Consumer Court (e-Daakhil)
File a formal civil reports under the clients safety Act. 2019 claiming monetary payout. Refund of banned extra fees. Permanent restraining orders against claims firms.
9. Chronological Timeline: Filing to Compensation Order
clients lawsuits follows a structured court timeline designed for swift claims adjudication. Moving systematically through distinct evidentiary and argumentative stages.
| Timeline Milestone. | Action Required | Expected Outcome. |
|---|---|---|
| Day 1 to 15 | proof Audit &. Legal Notice. | Establishes formal legal record and 15-day lender cure period. |
| Day 16 to 30 | Petition Drafting &. e-Daakhil Filing. | Formal registration of clients case and allotment of case number. |
| Month 2 to 3 | Admission Hearing &. Bank Summons. | Court issues notice to bank and grants interim anti-abuse stay. |
| Month 4 to 6 | Bank Reply. Rejoinder &. proof. | Submission of sworn affidavits. Call transcripts. And expert audits. |
| Month 7 to 12 | Final Arguments &. Award Execution. | court decree awarding damages or conclusion of bilateral OTS. |
10. Specialized Scenarios: Unauthorized Calls & Errors
clients court lawsuits addresses a wide spectrum of expert banking violations. This provides targeted legal remedies tailored to distinct factual situation.
Workplace & Third-Party Harassment
claims staff contacting employers. Colleagues. Distant relatives violates constitutional rights rights under the Puttaswamy verdict. Creating fast debt risk for large reputational damages in clients Court.
Unauthorized Credit Card Levies
Unilateral billing of unsolicited cover premiums. Annual maintenance charges on inactive cards. Hidden forex conversion fees are routinely struck down as unfair trade practices with full rates refunds.
Wrongful Post-Settlement CIBIL Status
When a bank accepts an OTS payment but continues reporting the account as written-off or active late. Clients commissions impose daily compliance penalties until CIBIL desk records are cleaned.
ARC Debt Assignment Coercion
Asset Reconstruction firms purchasing NPA portfolios must adhere strictly to RBI debt claims rules. Failing to provide formal assignment deeds while deploying claims firms constitutes severe service deficiency.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions: Consumer Court Bank Cases
Clear. Authoritative answers to essential questions regarding clients forum steps. Damages calculation. Legal defenses against bank claims misconduct.
Statutory Citations: Legal Authorities & Outbound Links
All legal interpretations and procedural rules detailed on this page are grounded in legal enactments. Binding Reserve Bank of India Master Directions. Landmark Supreme Court of India rulings.