Can a Loan Defaulter Go Abroad? Airport Immigration and LOC Rules
Unpack the legal reality of traveling overseas with unpaid private loans or credit cards. Learn why airport arrest threats are unlawful. How Lookout Circulars work under Ministry of Home Affairs rules. How to execute a remote closure from abroad.
Executive Summary: Can a Loan Defaulter Travel or Relocate Abroad?
Thousands of Indian workers and students face harsh claims staff threats claiming that unpaid private loans or credit cards will result in airport arrest or passport confiscation. Indian jurisprudence and immigration protocols establish unambiguous safeguards for cross-border travelers:
1. Debt Economics, Fundamental Rights & Civil Law Realities
When debt stress strikes due to job loss. health crises. Trade swings. No-pledge private loans and credit cards often turn into Non-Performing Assets (NPAs) after 90 days of steady non-payment. During this vulnerable phase. Clients often receive alarming contacts from claims firms asserting that defaulting on bank debt automatically revokes their right to travel outside India. Under Indian jurisprudence. These assertions are entirely baseless and by law unfounded.
The Supreme Court of India in the historic seven-judge bench ruling in. Maneka Gandhi v. Union of India (1978). established that the right to travel abroad is an integral component of private liberty guaranteed under Article 21 of the Constitution of India. This fundamental right cannot be curtailed through office overreach or private trade claims. A firm loans default between a client and a regulated lending institution is strictly a civil claims arising from a breach of contract under the Indian Contract Act. 1872. Banks. Non-Banking money firms (NBFCs). claims third parties possess zero sovereign policing formal and cannot restrict private mobility.
Lenders have the legal right to institute civil claims suits. File summary suits under Order XXXVII of the Code of Civil steps (CPC). Initiate private hearing under Section 21 of the hearing and talks Act. 1996. Approach the Debts claims Tribunal (DRT) for claims exceeding 20 Lakh Rupees. However. Civil money claims steps do not convert genuine money inability into a cognizable crime. Unless a client has engaged in deliberate penal fraud. Forgery. Money laundering. Non-payment of an no-pledge debt does not justify any international travel embargo.
2. Airport Immigration Reality: How the BOI Operates
A common scare tactic employed by harsh claims staff involves fabricating stories of immigration staff detaining clients at international departure terminals in Delhi. Mumbai. Bengaluru. Hyderabad. To understand why this is a legal impossibility. One must examine how the CIBIL desk of Immigration (BOI). Functioning under the Ministry of Home Affairs. Processes passenger clearances at international borders.
Immigration officials at airport checkpoints scan your passport to cross-reference travel papers against centralized state pledge databases. International INTERPOL red notices. Active penal warrants issued by court magistrates. formal Lookout Circulars (LOCs). The CIBIL desk of Immigration does not connect to credit information bureaus like CIBIL. Experian. Equifax. Nor does it maintain records of unpaid credit cards. Private loans. cars loans. Or late EMIs. Immigration staff are civil service border control workers whose legal mandate is national pledge. Immigration compliance. court warrant execution. Not private bank debt claims.
also. Foreign visa issuing officials. This includes consulates for the United States (USCIS). United Kingdom (UKVI). European Schengen zone. Canada (IRCC). Gulf help Council (GCC) nations. Evaluate applicants on visa-local criteria. Consular staff verify the validity of your passport. Biometric records. Clean Police Clearance letter (PCC) certifying the absence of pending penal convictions. Adequate funds for the intended stay. Foreign consulates have neither the police area nor the technical infrastructure to pull domestic Indian credit reports. This ensures that private debt defaults have zero impact on overseas visa adjudication.
3. Debt Categories & International Travel Restrictions Matrix
The legal repercussions on foreign travel vary largely depending on the nature of the debt. The court forum handling the claims. Whether penal steps have been invoked:
| Debt / Dispute Category. | Legal Classification. | Airport Immigration Impact. | Passports Act Restraint. | Recommended Legal Strategy. |
|---|---|---|---|---|
| no-pledge private loans. | Pure Civil Breach of Contract. | Zero Impact (Unrestricted Exit). | No legal Grounds for Impoundment. | Bilateral One-Time closure (OTS). |
| Defaulted Credit Card Dues. | no-pledge Revolving Credit Default. | Zero Impact (Unrestricted Exit). | No legal Grounds for Impoundment. | Waiver of penalty charges via Bank PNO. |
| Section 138 NI Act (Cheque Bounce). | Quasi-penal Bailable Offense. | Clear unless NBW is actively issued. | Section 6(2)(f) applies if court prohibits. | File Section 205 CrPC Exemption via lawyers. |
| DRT steps (>. ₹20 Lakhs). | legal Civil Debt claims. | Clear unless DRT passes Sec 19(12) Order. | Surrender only on local tribunal decree. | Appear through lawyer &. seek Lok Adalat OTS. |
| Major Economic Fraud / SFIO / CBI. | Cognizable penal Economic Offense. | High Risk (Active LOC &. Detention). | Passport Impounded under Section 10(3). | High Court Writ Petition under Article 226. |
4. MHA Guidelines & High Court Lookout Circular Precedents
A frequent source of anxiety among clients involves the concept of a Lookout Circular (LOC). Historically. The Ministry of Home Affairs issued an Office Memorandum in 2018 enabling Chairman and Managing Directors of Public Sector Banks (PSBs) to request LOCs against people whose departure was perceived to be detrimental to the economic interests of India. However. This power was repeatedly abused by banks attempting to use border control machinery as a claims arm for ordinary firm loans.
The constitutional validity of this practice was decisively challenged before constitutional courts. In the landmark judgment of. Viraj Chetan Shah v. Union of India (2024).The Division Bench of the High Court of Bombay quashed the clause empowering public sector bank chairmen to issue LOCs. Declaring it banned and violative of Articles 14 and 21. The Court unequivocally held that banks cannot curtail a citizen fundamental right to travel abroad simply to recover contractual debts in the absence of a registered cognizable penal investigation or legal court order.
Under current MHA rules and established court rulings. An LOC can only be legitimately generated by law enforcement firms (such as CBI. ED. SFIO. State Police) when a First Information Report (FIR) has been registered for severe penal breach of trust (Section 406 IPC / Section 316 BNS). Cheating (Section 420 IPC / Section 318 BNS). Large-scale money fraud involving national public rates. Standard no-pledge private loans defaults and credit card balances do not satisfy these legal thresholds.
Regarding the Passports Act. 1967. Section 6(2)(f) and Section 10(3)(e) empower Passport officials to refuse or impound a passport only when formal penal steps are pending before a penal court in India. When a non-bailable arrest warrant or summons for appearance has been issued. A standard civil notice. Loan demand notice. Bank hearing steps does not confer any legal right upon the local Passport Office (RPO) to impound or cancel a client travel papers.
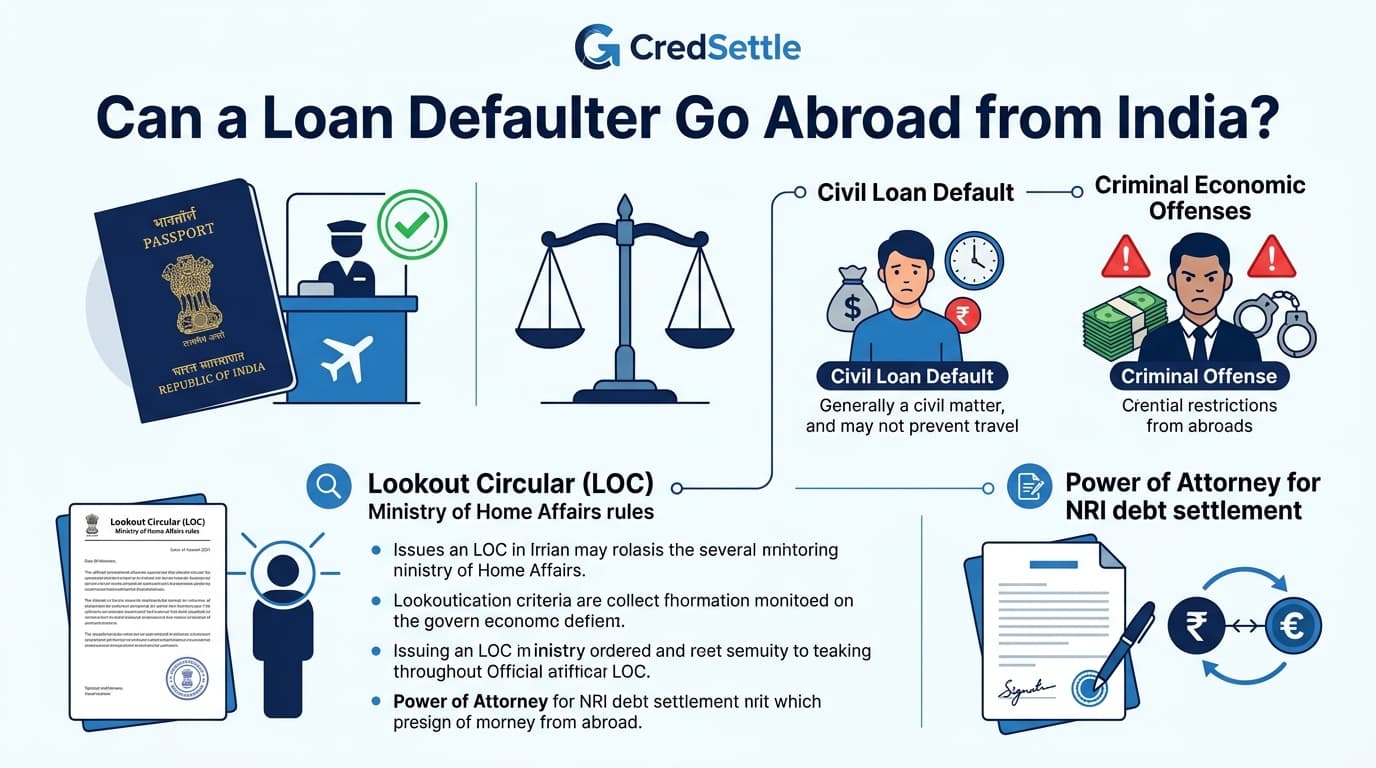
Visual Guide: Travel Rights & Cross-Border Debt Architecture
This infographic synthesizes constitutional travel rights. The clear demarcation between civil debt default and penal economic offenses. MHA Lookout Circular boundaries. The remote debt relief rules:
5. 6-Stage SOP for Overseas Travel & Remote Debt Settlement
If you are planning to relocate overseas or are already living outside India with unresolved banking debts. Adhering to a structured six-stage relief roadmap safeguards your legal standing and money future:
Stage 1: Comprehensive Loan & Judicial Warrant Audit
before overseas travel. Conduct a thorough audits of all active loan accounts. Credit cards. Pending court notices. Verify whether any lender has instituted steps under Section 138 of the Negotiable Instruments Act or Section 25 of the Payments and closure Systems Act in local magistrate courts. Ensure no non-bailable warrants exist on court dockets.
Stage 2: Execution of Special Power of Attorney (PoA)
Draft and execute a by law validated Special Power of Attorney under the Powers of Attorney Act. 1882. Appoint a trusted relative. Legal lawyer. Or authorized debt relief expert in India. If executed abroad. Get the paper attested by the Indian Embassy or Consulate and adjudicated before the areas Sub-Registrar in India within legal timelines.
Stage 3: Legal Representation & Personal Exemption Filings
If bailable quasi-penal summons under Section 138 or Section 25 are active. Instruct your appointed lawyers to file a vakalatnama along with an application under Section 205 CrPC (or Bharatiya Nagarik Suraksha Sanhita equivalent). This formally requests private exemption from physical court appearances. Ensuring steps continue seamlessly through legal lawyer without warrant reports.
Stage 4: Bilateral One-Time Settlement (OTS) Negotiations
Your debt relief workers present a verifiable hardship dossier to the bank closure alert boards and main loan Nodal staff. Talks strip away inflated extra fees. Compounded late fees. late charges. Establishing a realistic OTS deals figure typically between 40% and 60% of the legitimate base loan.
Stage 5: Forensic Verification of Formal Bank Sanction Letter
Never transfer closure funds based on verbal promises or unverified emails from claims staff. Demand an formal. System-generated OTS deals sanction letter issued on the bank formal letterhead. The paper must explicitly stipulate the agreed closure sum. Structured payment schedule. Waiver breakdown. Commitment to withdraw all pending legal notices.
Stage 6: Direct Remittance, No Dues Certificate & CIBIL Rectification
pay the agreed payout sum straight from your NRE/NRO bank account or domestic Indian account into the designated loan account. Within 30 days of final remittance. Obtain an formal No Dues letter (NDC) or No Objection letter (NOC). Ensure the bank files formal withdrawal memos in court forums and updates credit bureaus to Closed or Settled status.
6. Statutory Notice Defense and Borrower Legal Rights
When managing debt claims from overseas. Understanding the local legal mechanisms invoked by Indian banks is vital for maintaining legal compliance:
Section 138 Negotiable Instruments Act (Cheque Bounce)
If an undated pledge cheque submitted during loan onboarding is presented and dishonored. Lenders may issue a legal notices under Section 138 of the NI Act within 30 days of receipt of the bank return memo. This is a bailable quasi-penal steps. An lawyers can appear under Section 205 CrPC to defend the case or refer the matter to National Lok Adalat for a OTS deals without requiring your private presence.
Section 25 Payments & Settlement Systems Act (NACH Bounce)
Dishonor of an electronic National Automated Clearing House (NACH) mandate or e-mandate attracts steps under Section 25 of the PSSA. 2007. This parallels the legal rules of Section 138. Receiving a Section 25 notice does not trigger airport immigration alerts or border stops. You have 15 days from notice receipt to reply. claims banned presentations. Or seek an amicable closure.
Debts Recovery Tribunal (DRT) Section 19 Powers
For debt exposures exceeding 20 Lakh Rupees. Banks can file an Original Application (OA) before the DRT under Section 19 of the claims of Debts and ruin Act. 1993. Under Section 19(12). A DRT Presiding staff can direct passport surrender only when the bank conclusively shows that the defendant is attempting to transfer assets or abscond to defeat decree execution.
RBI Fair Practices Code Against Cross-Border Intimidation
The RBI Master Direction on Fair Practices Code strictly prohibits lenders and claims staff from calling clients before 8:00 AM or after 7:00 PM. Making threatening international calls. Contacting foreign employers or colleagues. Intimidating aged parents and relatives in India. Violations can be escalated straight to the RBI RBI staff for fast RBI censure.
7. 3-Tier Escalation Matrix Against Harassment & Travel Threats
If claims firms subject you or your kin to banned airport arrest threats or abusive contacts. Initiate formal grievance reports through regulated legal channels:
Grievance Redressal Officer (GRO)
Submit a formal written reports detailing call recordings. Abuse timestamps. staff staff IDs. Under RBI mandates. The bank GRO must investigate and provide a formal written relief within 7 to 10 working days.
Principal Nodal Officer (PNO)
If the GRO fails to resolve unlawful travel threats. Escalate the matter to the bank main loan Nodal staff. The PNO has executive formal to suspend third-party claims firms and initiate formal One-Time closure discussions within 14 to 21 days.
RBI Integrated Ombudsman (CMS)
If the bank remains unresponsive after 30 days. File an online reports at cms.rbi.org.in under the Reserve Bank - Integrated staff Scheme. 2021. The staff can award payout up to 20 Lakh Rupees for severe mental abuse and unfair debt claims practices.
8. Timeline: From Default to Remote Overseas Debt Resolution
The lifecycle of an unresolved debt transitioning into a successful remote closure follows structured procedural milestones:
| Timeline Period | Loan Account Classification. | Bank Operational Action. | Strategic Borrower Action. |
|---|---|---|---|
| Days 1. 30 | SMA-0 (Special Mention Account). | Automated SMS. Emails. And gentle payment reminders. | Communicate hardship in writing. |
| Days 31. 90 | SMA-1 &. SMA-2 Classification. | claims staff outbound calling and field visits. | Execute Special Power of Attorney (PoA). |
| Day 90+ | Non-Performing Asset (NPA). | 100% bank reserves allocation. legal notices issued. | Engage debt relief workers for OTS. |
| Months 4. 5 | Active Bilateral talks Window. | Credit boards reviews OTS deals proposals. | Secure formal closure sanction letter with 40%. 70% waiver. |
| Month 6 | Full Closure &. No Dues Issuance. | Issuance of NDC and withdrawal of court/tribunal memos. | Obtain NDC and verify CIBIL status updated to Closed. |
9. Scenarios: Students, GCC Job Seekers and Remote PoA
Cross-border debt relief involves distinct bank and daily work nuances across different client profiles:
Students Traveling Overseas on F-1, UK Student or Study Permits
Students who hold defaulted credit cards or clients loans taken before receiving an international university admit can travel without immigration hurdles. Foreign universities and embassy visa desks verify academic credentials. Tuition funding. Police records. Not domestic private loans statuses.
Professionals Relocating to UAE, Saudi Arabia, Singapore or Europe
workers relocating for jobs often worry that bank notices will reach their overseas employers. Indian banks have zero extraterritorial police area and cannot deduct salaries abroad. Executing a remote closure clears Indian money dues while building savings overseas.
Loans Assigned to Asset Reconstruction Companies (ARCs)
When Indian banks sell defaulted retail portfolios to ARCs (such as Phoenix ARC. Invent ARC. CFM ARC). The ARC acquires the debt at steep portfolio discounts (often 20% to 30% of face value). ARCs are commercially driven entities and readily approve deep OTS deals for overseas clients.
Remote Settlement via Embassy Attested Power of Attorney
Non-Resident Indians (NRIs) and expatriates can easily settle Indian loans without visiting India. By executing a Special PoA attested at the local Indian Consulate. An authorized staff in India conducts talks. Verifies closure letters. Collects the physical No Dues letter.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions: Loan Defaults & Going Abroad
Click on any question below to view detailed legal answers checked by our legal and debt relief workers:
Official Regulatory Citations & Judicial References
- Constitution of India: Article 21 (safety of Life and private Liberty - Right to Travel Abroad as upheld in. Maneka Gandhi v. Union of India. 1978 AIR 597.).
- High Court of Bombay: Viraj Chetan Shah v. Union of India (2024). (Quashing powers of Public Sector Bank Chairmen to issue arbitrary Lookout Circulars).
- Passports Act. 1967: Sections 6(2) and 10(3). Ministry of External Affairs. state of India.
- Negotiable Instruments Act. 1881 &. PSSA 2007: Section 138 and Section 25 (Bailable legal rules for money instrument dishonor).
- Reserve Bank of India: Master Direction on Fair Practices Code for Lenders and Reserve Bank - Integrated staff Scheme. 2021.