NRI Travel to India with Unpaid Loans: LOC & Airport Realities
Legal clarity for Non-Resident Indians on Airport Look Out Circulars. claims agent threats. cross-border debts. Learn how to resolve defaulted Indian private loans and credit cards 100% online from abroad with complete legal immunity.
- Zero Airport Detention for Civil Debt: Defaulting on no-pledge private loans or credit cards in India is purely a civil contractual matter with zero legal provision for airport arrest or immigration detention upon arrival.
- trade LOCs are banned: Landmark High Court rulings (including the Bombay High Court in. Viraj Chetan Shah.) have established that banks cannot open Look Out Circulars for standard claims claims.
- Independent International Credit Systems: Indian CIBIL desk defaults (CIBIL. Experian India) are entirely isolated and have zero bearing on your foreign credit scores (US FICO. UK Experian. UAE AECB) or visa sponsorships.
- 100% Remote relief Protocol: NRIs do not need to travel to India. Debt deals can be executed digitally via Special Power of Attorney (PoA) straight with bank zonal credit boards.
- 40% to 55% settled Waivers: Because banks classify 90-day late loans as Non-Performing Assets (NPAs) requiring Tier-1 bank reserves. They readily approve large main loan haircuts.
- Ancestral home Immunity: no-pledge loans carry no pledge mortgage. Banks cannot attach kin or inherited homes without protracted civil money decrees.
- Compoundable court steps: Cheque bounce notices under Section 138 of the NI Act or Section 25 of the PSSA can be formally closed through an amicable settlement without private court surrender.
- Direct NRE/NRO Account Remittance: OTS deals are paid straight to checked loan accounts from domestic or foreign funds. Followed by an formal No Dues letter (NDC).
1. NRI Debt Economics: Defaults & Bank NPA Dynamics
Relocating overseas involves large transitional cash expenditures. Visa fees. relocation costs. Thousands of Non-Resident Indians (NRIs) working across the Gulf help Council (GCC). The United Kingdom. North America. Southeast Asia skill sudden economic dislocation due to international tech layoffs. firm restructuring. unexpected health crises. When overseas living expenses surge. Servicing pre-existing private loans. Revolving credit cards. trade borrowings taken in India becomes unsustainable.
When monthly installments are missed. Indian banks follow the Reserve Bank of India (RBI) Prudential Norms on Income Recognition. Asset Classification and bank reserves. An account progresses through Special Mention Account stages: SMA-0 (1 to 30 days late). SMA-1 (31 to 60 days late). SMA-2 (61 to 90 days late). Once non-payment crosses ninety steady days. The lender is by law obligated to classify the facility as a Non-Performing Asset (NPA).
Under RBI mandates. Banks must set aside up to 100% bank reserves against Tier-1 cash for no-pledge NPAs. Locking up their balance sheet liquidity. Because no-pledge credit cards and private loans carry zero physical pledge or mortgage charge under the SARFAESI Act. 2002. The lender possesses no asset to seize or auction. Initiating international lawsuits across foreign police areas is commercially impractical for retail balances. As a result. Bank Stressed Asset handling Divisions (SAMD) are strongly incentivized to approve One-Time deals (OTS) to clean their books and recover cash.
2. Financial Breakdown: NRI Principal vs Inflated Penalties
When an NRI client stops servicing an Indian loan. Lenders compound the ledger by imposing excessive extra fees. Late payment surcharges. Monthly finance charges. claims vendor overheads. Over twelve to eighteen months of non-payment. These growing fees often inflate the claimed debt risk to nearly double the original base loan. Lenders and third-party claims telecallers often weaponize these exaggerated figures to generate panic.
During bank debt relief. CredSettle performs a full audits of the bank ledger record. We systematically separate the core remaining main loan from the artificial penalty layer. In an authentic OTS deals. Credit boards readily sanction a 100% waiver of all total extra fees. Bounce charges. Office expenses. Alongside a 40% to 55% haircut straight on the underlying base loan.
Representative 180-Day NRI Multi-Facility Debt Settlement Calculation
Target 40% to 55% Principal Waiver.Settling at the audited net main loan figure stops growing fees promptly and enables complete loan closure through a direct transfer from your NRE or NRO account.
3. Resolution Pathways: Comparison of Legal Remedies
Non-Resident Indians facing defaulted money dues must evaluate the relative efficiency. Money savings. Legal risks associated with available relief channels. The comparative table below outlines the primary mechanisms available under Indian law:
| Resolution Mechanism. | Physical Travel Required. | Financial Waiver. | Legal Notice Immunity. | Resolution Speed. | Strategic Fit for NRIs. |
|---|---|---|---|---|---|
| Remote One-Time settlement (OTS). | Zero Travel (100% Online). | 40% to 55% main loan Cut. | Complete civil immunity with NDC. | 30 to 60 Days | Optimal choice for NRIs living abroad. |
| Loan Restructuring / Moratorium. | Branch visit often demanded. | Zero Waiver (rates Accrues). | Temporary while EMIs continue. | 60 to 90 Days | Suitable only if high foreign income resumes. |
| Civil Court / DRT lawsuits. | Requires Indian counsel presence. | Uncertain trial outcomes. | High lawsuits costs and delays. | 3 to 7 Years | Defensive necessity if claims exceed ₹20 Lakhs. |
| National Lok Adalat. | Represented via Power of Attorney. | 30% to 50% OTS deal. | Final binding decree under LSA Act. | Single-day sitting. | Highly effective if matched with court calendar. |
| Passive Inaction. | Unresolved status. | Zero (Debt compounds). | Risk of ex-parte decrees in India. | Indefinite | High risk leading to claims agent abuse. |
4. CIBIL Algorithm: Bureau Scoring & CICRA Rectification
Indian credit reporting operates under algorithmic scoring rules managed by TransUnion CIBIL. Experian. CRIF High Mark. Equifax. The scoring architecture assigns distinct mathematical weights to five underlying credit behaviors: payment track record (35%). Credit exposure and credit use ratio (30%). Depth of credit history (15%). Credit product diversity (10%). Recent hard credit inquiries (10%).
When an NRI client defaults on an Indian loan. The 35% payment weighting causes a rapid credit score drop of 100 to 180 points as Days Past Due (DPD) metrics exceed 90 days. However. It is vital to understand that Indian credit bureaus possess zero data integration with overseas credit scoring repositories such as FICO in the United States. Equifax in the UK. The Al Etihad CIBIL desk (AECB) in the UAE. A default in India will not reflect on your overseas credit profile or affect foreign residency permits.
Section 21 CICRA Statutory Bureau Rectification
Upon executing a formal One-Time settlement and paying the agreed OTS deal figure. The lending institution is mandated under Section 21 of the Credit Information firms (Regulation) Act. 2005 (CICRA) to update all four licensed credit bureaus within thirty days.
The unpaid dues is permanently updated to zero. And all ongoing default reporting ceases. If you plan to return to India in the future. You can easily rebuild your CIBIL score to 750+ within 12 to 18 months by maintaining an on-time payment track record on a secured Indian credit card backed by a fixed deposit.
5. Visual Protocol: NRI Debt Defense & Resolution SOP
This full visual workflow outlines the complete 6-stage legal and bank protocol for resolving defaulted Indian bank debt remotely from overseas without travel risks:
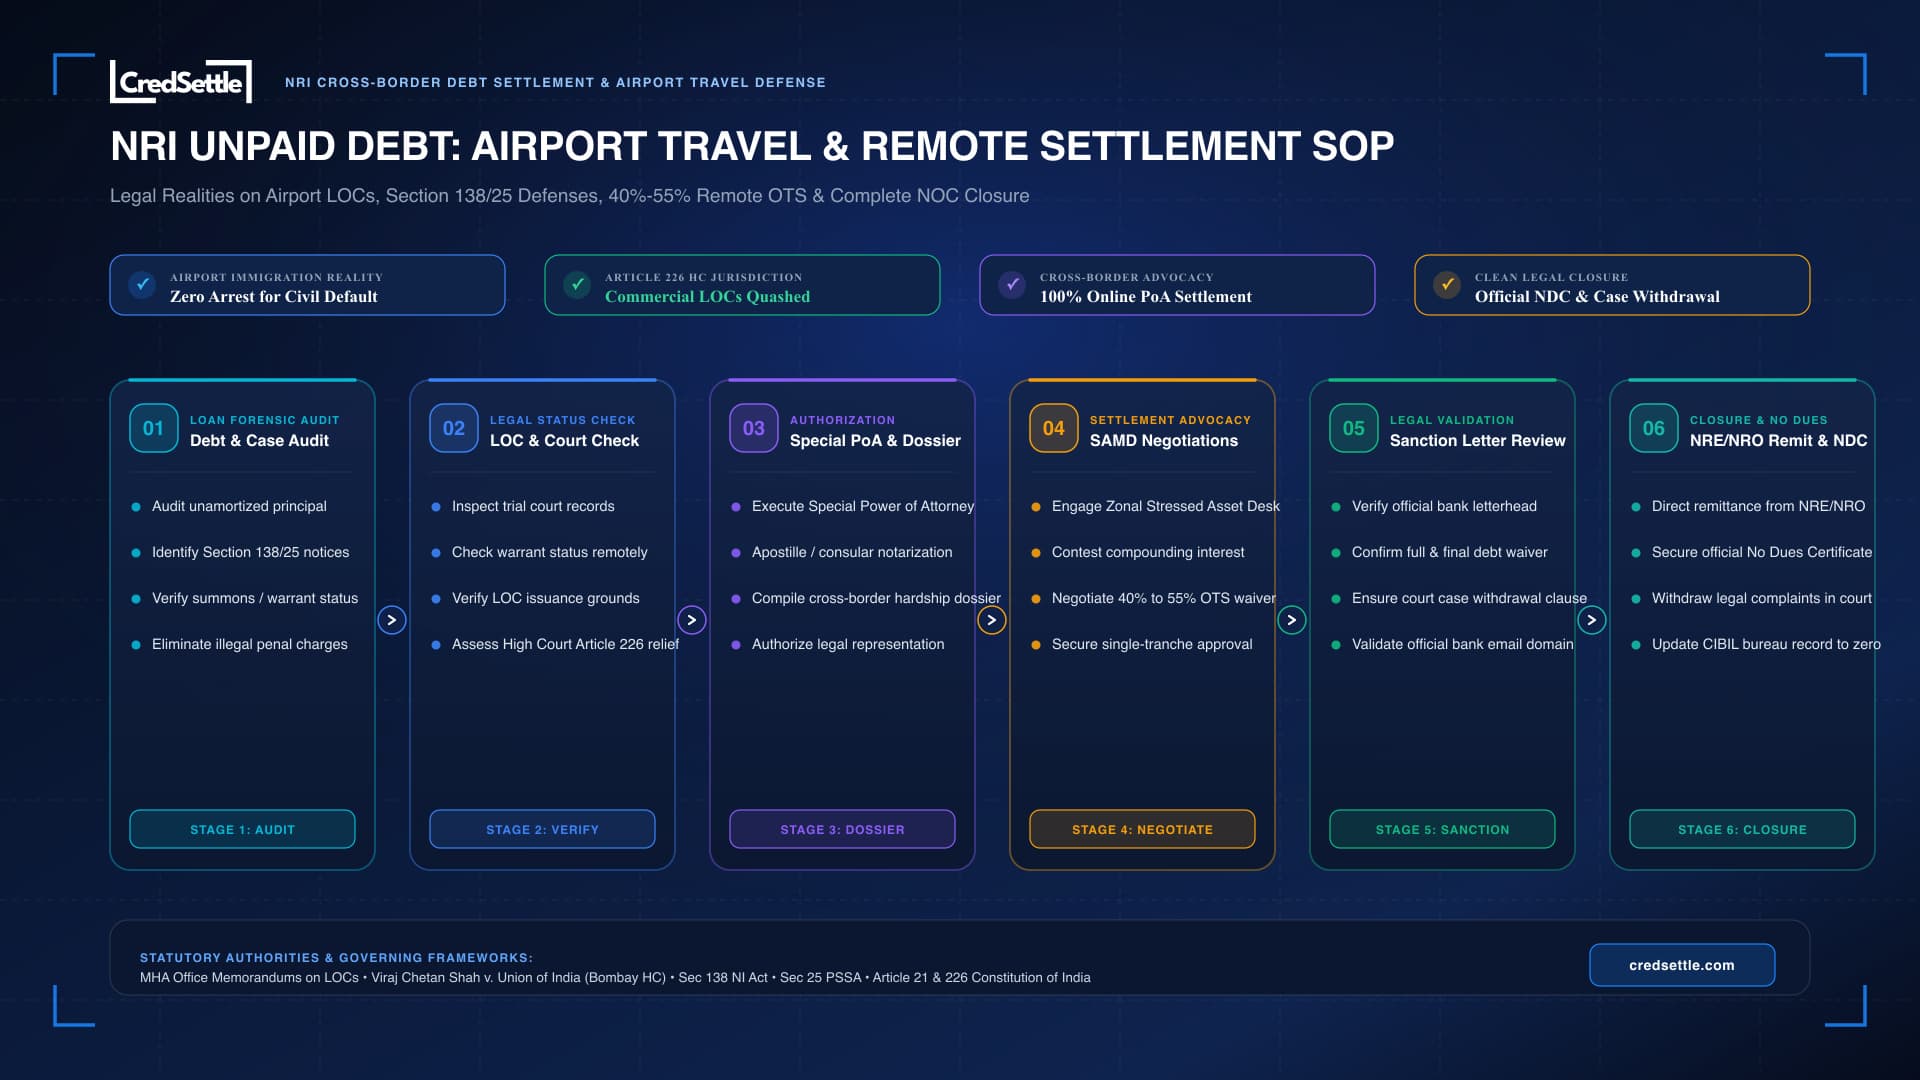
6. Step-by-Step SOP: Remote NRI Loan Settlement Process
NRIs can achieve permanent debt closure and obtain an authentic No Dues letter without ever traveling to India by adhering to this sequential standard operating steps:
Comprehensive Account Statement & Demand Scrutiny
CredSettle relief specialists audit your entire loan history to identify true remaining main loan. We isolate unlawful growing extra fees. Duplicate NACH bounce penalties. banned claims firm fees to establish an accurate baseline for OTS deal talks.
Court Record Search & Immigration Status Check
Our legal panel conducts an exhaustive e-Courts search across magistrate courts associated with your registered Indian address. We verify whether any Section 138 NI Act or Section 25 PSSA summons were issued. Confirming complete absence of bailable or non-bailable warrants.
Consular Attestation & Involuntary Distress Filing
You execute a limited Special Power of Attorney (PoA) authorizing CredSettle to represent your interests before bank credit boards. We compile an overseas hardship dossier including foreign jobs termination notices. Visa transitions. health bills to justify a large settlement haircut.
Zonal Stressed Asset Committee Representation
We bypass third-party claims firms and present your hardship petition straight to the bank Circle Stressed Asset handling Division (SAMD). Our negotiators contest inflated charges and secure a formal One-Time settlement OTS deal providing a 40% to 55% loan cut.
Validation of Official Bank Sanction Terms
Our legal panel conducts a strict validation of the settlement sanction letter. We verify that it originates from an formal bank domain. Explicitly declares the remittance as Full and Final settlement. Contains clear account details. Commits to the full withdrawal of legal claims.
Direct Account Payment & Permanent Closure
You pay the agreed payout sum straight into your checked bank loan account from your foreign or NRE/NRO account. We ensure that the bank issues an authentic No Dues letter (NDC). Closes internal ledgers. Updates your CIBIL desk balance to zero.
7. Statutory Defense: Airport LOC & Legal Rights Matrix
Non-Resident Indians are protected by robust constitutional safeguards. Legal enactments. Established High Court rulings against arbitrary debt claims actions and travel restrictions:
Under Ministry of Home Affairs (MHA) Office Memorandums and the landmark Bombay High Court ruling in. Viraj Chetan Shah v. Union of India (2024).Public and private sector banks have no legal power to request Look Out Circulars for standard loan defaults. LOCs can only be issued in cognizable penal offenses involving severe national economic threats.
Dishonored cheques or bounced auto-debit mandates trigger quasi-penal reports under Section 138 of the Negotiable Instruments Act or Section 25 of the Payments and settlement Systems Act. These offenses are compoundable under Section 147 of the NI Act and can be permanently settled out of court through authorized counsel.
When lenders initiate domestic hearing under Section 21 of the 1996 Act. Unilateral appointments of sole arbitrators by banks are by law invalid under Supreme Court rulings (.Perkins Eastman and TRF Ltd.). NRIs can challenge unlawful arbitral notices through written legal objections.
Debts claims Tribunals (DRT) only adjudicate claims claims exceeding ₹20 Lakhs under the RDB Act. 1993. If any firm attempts unlawful travel impedance. NRIs can invoke Article 226 of the Constitution before the jurisdictional High Court to obtain an fast stay and passport safety.
8. 3-Tier Escalation Matrix: Bank PNO to RBI Ombudsman
If claims agents engage in banned contact abuse against your kin in India or issue baseless threats regarding your travel. Execute this structured 3-tier RBI reports hierarchy:
Internal Legal Representation & Direct Channeling
Serve a formal legal legal help upon the bank main loan Nodal agents (PNO) and Circle Debt relief Head. Cite overseas hardship. Demand an fast halt to third-party telecalling at Indian kin addresses. Formally initiate internal OTS deals steps.
Writ Jurisdiction for Fundamental Travel Protection
If an institution attempts banned travel restrictions or misrepresents penal reports. Our legal team files a Writ Petition under Article 226 before the High Court. High Courts routinely quash banned claims circulars and reaffirm the fundamental right to travel under Article 21.
Regulatory Redressal on cms.rbi.org.in
If the bank fails to provide transparent ledger records or tolerates claims agent violations of the RBI Fair Practices Code. File a reports on the RBI CMS portal (.cms.rbi.org.in). The agents exercises RBI powers to sanction non-compliant lenders and enforce OTS deal rules.
9. Procedural Timeline: Delinquency to Debt Freedom
Understanding the chronological milestones of Indian debt default enables Non-Resident Indians to strategically time their talks and protect their rights:
| Timeline Milestone. | Asset Classification. | Bank Recovery Strategy. | NRI Countermeasure. |
|---|---|---|---|
| Days 1. 30 | SMA-0 Stage | Automated SMS, emails. phone calls. | Notify bank of overseas transition in writing. |
| Days 31. 60 | SMA-1 Stage | Third-party firm calls to Indian reference contacts. | Issue formal cease-and-desist to protect kin. |
| Days 61. 90 | SMA-2 Stage | Intensified claims and pre-lawsuits notices. | Initiate deep ledger review with CredSettle. |
| Days 91. 180 | NPA (Sub-Standard). | 100% Tier-1 bank reserves. OTS window opens. | Submit hardship dossier for 40%. 55% OTS waiver. |
| Months 6. 12 | Doubtful NPA | Potential ARC debt assignment or civil suit. | Finalize single-tranche OTS from NRE/NRO account. |
| Month 12+ | Full Closure | Account settled. All legal claims withdrawn. | Obtain formal NDC and update CIBIL record to zero. |
10. Specialized Scenarios: Gulf Layoffs & ARC Portfolios
Cross-border debt relief involves distinct challenges based on your host country. Residential status. account assignments:
GCC & UAE Corporate Downsizing & Sudden Repatriation
workers in Dubai. Abu Dhabi. Doha. And Riyadh often face rapid contract terminations with short visa grace periods. CredSettle negotiates urgent OTS deals with Indian lenders before end-of-service gratuity funds are exhausted. Securing maximum waivers and preventing long-term credit distress in India.
Inactive Indian Phone Numbers & Untraceable Registered Address
When NRIs surrender their Indian mobile SIMs and vacate Indian residences. Banks send demand notices to outdated addresses. Occasionally attempting ex-parte legal actions. Our legal panel establishes a checked electronic contact bridge with the bank. Redirecting all correspondence to authorized counsel.
Asset Reconstruction Company (ARC) Portfolio Assignments
If an Indian bank sells late NRI debt to an ARC under Section 5 of the SARFAESI Act. ARCs acquire the debt at heavy discounts. CredSettle leverages the ARC low acquisition cost to settle even larger main loan haircuts (often exceeding 60%). Securing a complete release from the ARC.
Consular Attestation & Power of Attorney Execution
NRIs can easily execute a Special Power of Attorney through Indian Consulates or apostille officials in their country of residence. This paper empowers CredSettle to inspect bank records. Attend Lok Adalat talks hearings. Execute settlement deeds without your physical return to India.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions: NRI Debt & Airport Travel
Click on any question below to view detailed legal answers checked by our cross-border debt relief workers:
Statutory Citations & Official Regulatory Authorities
- Ministry of Home Affairs (MHA) Office Memorandums: rules on Issuance of Look Out Circulars in Respect of Indian Citizens and Foreign Nationals.
- Bombay High Court Landmark Judgment: Viraj Chetan Shah v. Union of India &. Ors. (2024). (Quashing powers of banks to request Look Out Circulars for civil debt defaults).
- Constitution of India: Articles 21 (safety of Life. Liberty and Right to Travel) and 226 (Writ police area of High Courts).
- Negotiable Instruments Act. 1881: Section 138 (Dishonour of Cheques) and Section 147 (growing of Offences).
- Payments and settlement Systems Act. 2007 (PSSA): Section 25 (Dishonour of Electronic Funds Transfer).
- Reserve Bank of India Master Directions: Prudential Norms on Income Recognition. Asset Classification and bank reserves about Advances (Updated 2026).
- Credit Information firms (Regulation) Act. 2005 (CICRA): Section 21 (strict Updating of Settled CIBIL desk Records).