Executive Brief: Non-Bailable Warrants in Cheque Bounce
1. Debt Economics & Legal Rationale Behind NBW Issuance
Defaulting on a own loan or credit card is fundamentally a civil contract breach under the Indian Contract Act. 1872. Yet. Trade banks routinely convert clean debts into quasi-penal disputes by depositing post-dated security cheques or presenting online NACH mandates collected during disbursement. Following an EMI bounce. Lenders issue a legal demand notice under Section 138(b) of the Negotiable Instruments Act. 1881. Followed by a penal complaint under Section 200 CrPC.
Banks favor penal complaints over civil suits due to RBI prudential norms. Once an overdue account breaches 90 Days Past Due. It becomes a Non-Performing Asset (NPA). Requiring mandatory Tier-1 capital provisioning. Because civil suits take years. Lenders use Section 138 trials to exert own liberty pressure. When postal summons fail to reach clients due to changed addresses or flawed process service. Magistrates presume willful evasion and escalate from summons to Non-Bailable Warrants under Section 70 CrPC (Section 72 BNSS).
The Supreme Court of India in Inder Mohan Goswami v. State of U.P. (2007) and Raghuvansh Dewanchand Bhasin (2012) established that courts must protect own liberty under Article 21. Non-Bailable Warrants must never be issued mechanically in trade money disputes without proof of deliberate evasion.
2. Financial Breakdown: Penalty Stacking vs Settlement Math
During penal cheque bounce litigation. Lender claim statements are heavily inflated. Banks stack overdue rates. Bounce fees. Monthly penal rates at 24% to 36%. 18% GST. legal expenses. Consequently. A borrowed main sum of ₹6,50,000 often doubles into an inflated demand of ₹12,00,000 within 180 days of default.
Once counsel recalls the NBW and secures bail. The bank loses coercive leverage. This enables bilateral One-Time closure (OTS) talks to waive penal charges and close the dispute at 40% to 55% of the total claim.
3. Legal Remedy Comparison: NBW Recall vs Alternative Paths
Evaluating available legal remedies against an active NBW ensures fast safety from custodial detention while progressing toward debt relief.
| Resolution Pathway | Legal Forum | Custodial Risk | Timeline | Case Outcome |
|---|---|---|---|---|
| Section 70(2) Recall Petition | Issuing Magistrate Court | Zero Risk with Surety | 24 to 48 Hours | Warrant cancelled. regular bail granted. |
| High Court Sec 482 Quashing | State High Court | Stay on Police Arrest | 7 to 15 Days | Warrant stayed. trial quashed if notice invalid. |
| Surrender &. Bail Application | Judicial Magistrate / MM | Released on Bond | Same Day Hearing | Bail granted on own bond &. local surety. |
| National Lok Adalat OTS | NALSA Lok Adalat Bench | Zero Arrest Risk | 1 to 3 Weeks | Full growing under Sec 147 NI &. case closure. |
| Ignoring Active NBW | Police &. penal Court | Imminent Jail Arrest | Indefinite Risk | Sec 82 proclamation &. Sec 83 home attachment. |
4. CIBIL Impact: Credit Score Damage and Restoration Plan
While an arrest warrant is not straight published to credit desk feeds. Underlying loan defaults severely damage your CIBIL score. CIBIL computes scores based on five core factors: 35% Payment History. 30% Utilization Ratio. 15% History Length. 10% Credit Mix. 10% Inquiries. Delinquency tags like ". Suit Filed". or ". Written-Off". drop credit scores from 750+ down to distress ranges (520 to 580).
Restoring credit requires securing an unconditional No Dues letter (NDC) post-closure. Under Section 21 of the Credit Information Companies (rule) Act. 2005 (CICRA). Submitting the NDC mandates the desk to update the status to ". Closed". or ". Settled". Combined with secured credit builder products. Your score can recover to 750+ within 18 to 24 months.
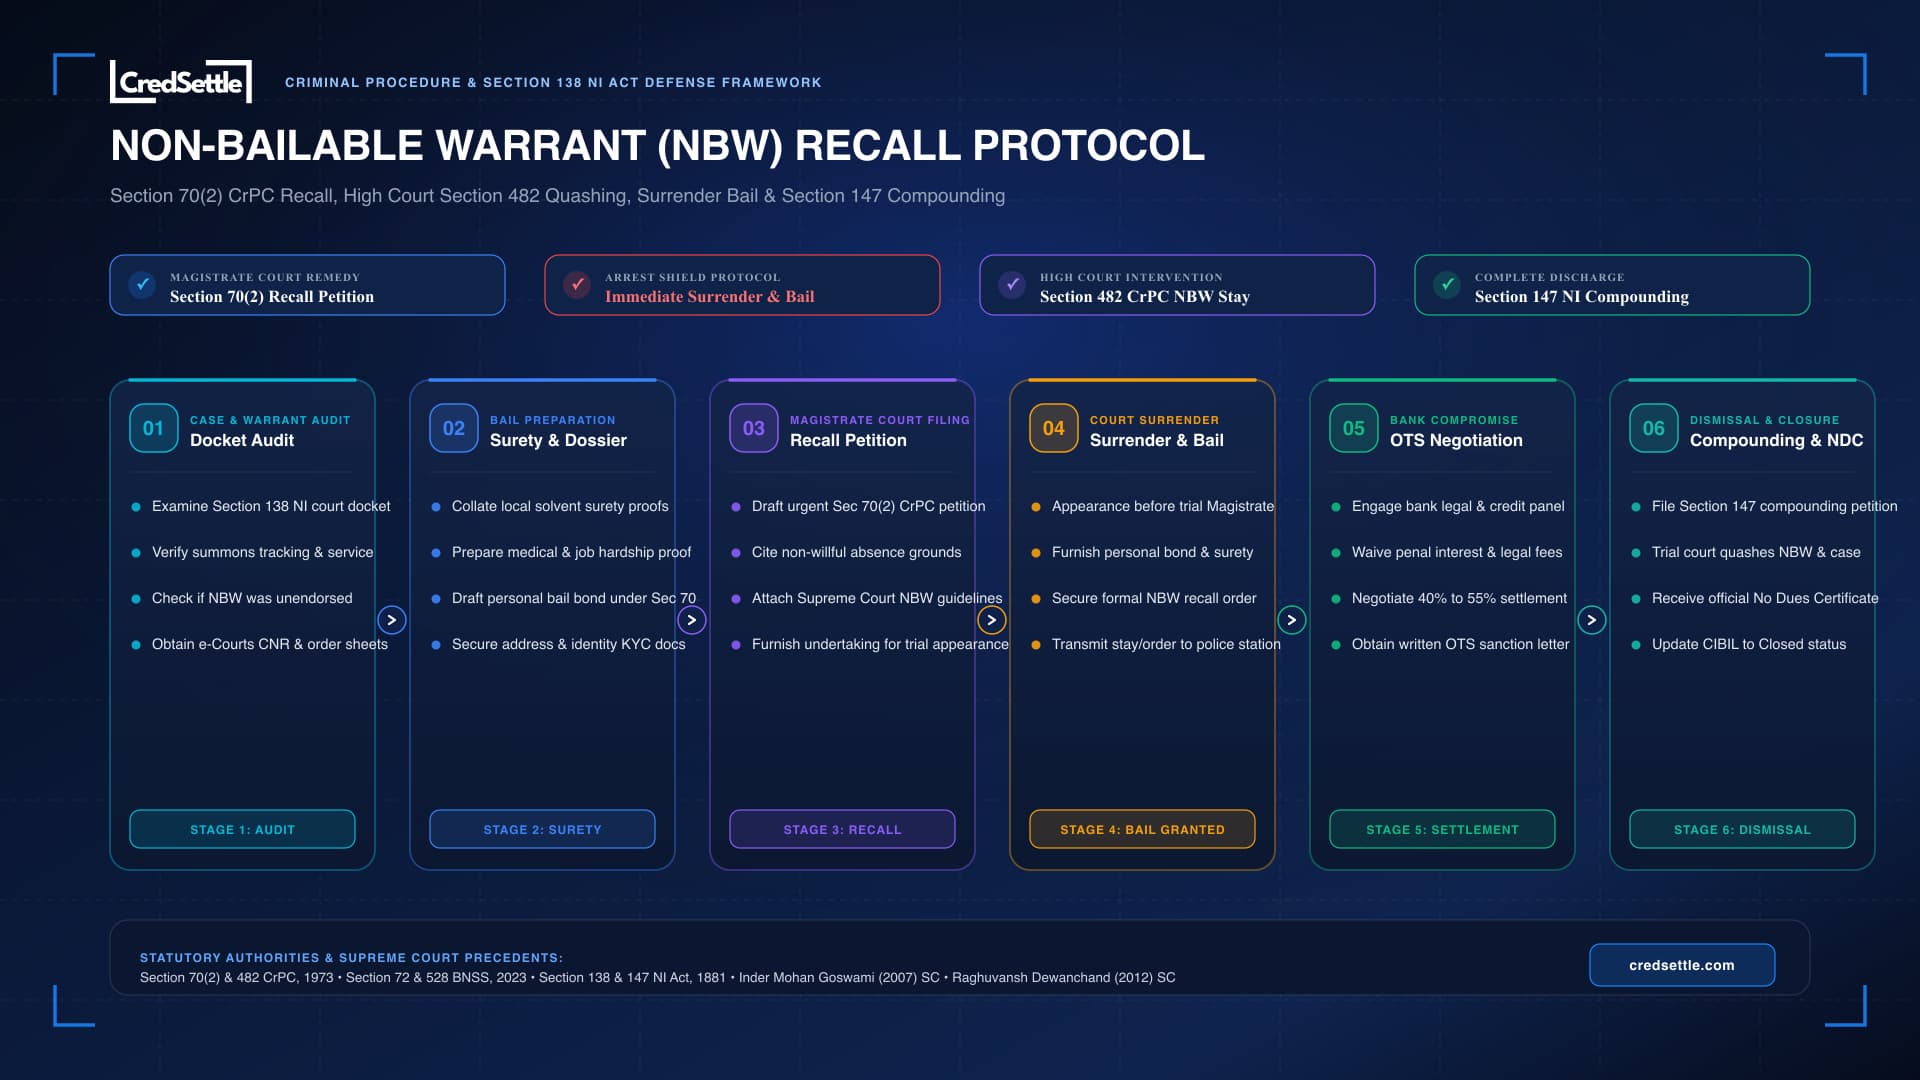
Infographic: 6-Stage Non-Bailable Warrant Defense Protocol
5. Step-by-Step SOP: Protocol to Recall NBW and Avoid Arrest
CredSettle executes a structured six-stage protocol before Magistrate Courts across India to neutralize arrest risks and achieve legal case dismissal.
Stage 1: Forensic Docket &. Warrant Audit
Counsel audits the e-Courts CNR docket. Extracts signed order sheets. Verifies whether postal summons were returned unserved or delivered to an outdated address. Establishing procedural non-service.
Stage 2: Hardship Dossier &. Solvent Surety Preparation
We compile proof prove non-appearance (medical letters or job transfer records) while arranging local solvent surety proofs and own bail bonds to fulfill court bail conditions.
Stage 3: Urgent Section 70(2) Recall Petition Filing
Counsel drafts and files an urgent Section 70(2) CrPC recall application with an affidavit. Establishing absence was non-willful and citing Supreme Court guidelines in Inder Mohan Goswami.
Stage 4: Court Appearance. Surrender &. Bail Grant
Our counsel appears before the Magistrate. Surrenders the clients to court jurisdiction. Furnishes bail bonds. Secures an fast order cancelling the NBW. With copies sent to the local police station.
Stage 5: Bilateral OTS talks with Bank
With arrest risks resolved. CredSettle negotiates straight with the bank Credit board to strip unearned penal charges and secure a formal OTS sanction letter offering a 40% to 55% waiver.
Stage 6: Section 147 growing &. No Dues letter
Upon remitting closure funds. A growing application under Section 147 NI Act is filed. The court dismisses the complaint. Acquits the clients. the bank issues a final No Dues letter.
6. Statutory Notice Defense: Legal Shield Against Section 138
clients possess strong legal defenses against defective cheque bounce steps. penal courts cannot sustain prosecution if the lender failed to meet mandatory legal preconditions.
Demand notices must be issued within 30 days of cheque dishonor. Failure to serve notice at the valid address or premature filing before the 15-day cure period invalidates prosecution.
NACH/ECS bounce complaints under Section 25 PSSA must strictly follow legal notice windows. Repeated presentations without fresh notices violate settled procedure.
Under the Perkins Eastman ruling. Lenders cannot unilaterally appoint sole arbitrators for parallel claims. Such awards are null. Void. by law unenforceable.
clean loans cannot face home attachment without adjudication. RBI Fair Practices Code strictly prohibits claims contact before 8:00 AM. After 7:00 PM. to relatives.
Establishing procedural defects enables your counsel to seek fast discharge or petition the High Court under Section 482 CrPC to quash the warrant and complaint.
7. 3-Tier Escalation Matrix: Trial Court to High Court Quash
CredSettle deploys a three-tier legal strategy based on the procedural stage of the warrant and lender cooperation.
We appear before the issuing Magistrate. Present bona fide grounds for prior non-appearance. Furnish own appearance bonds. secure same-day recall of the Non-Bailable Warrant.
If onerous bail terms are imposed. We file a penal Revision under Section 397 CrPC while referring the dispute to the National Lok Adalat for an bank deal closure.
Where prosecution is time-barred or lacks legal notice service. We petition the High Court under Section 482 CrPC (Section 528 BNSS) to obtain an interim stay and quash the complaint.
8. Procedural Timeline: Default to Compounding Milestones
grasp Section 138 procedural milestones enables timely legal action before coercive warrants are executed.
| Timeline Milestone | Governing Law | Bank Action | Borrower Protection Strategy |
|---|---|---|---|
| Day 1 to 30: EMI Dishonor | Sec 138(b) NI Act | Lender dispatches 30-day legal notice | Send detailed legal reply explaining hardship. |
| Day 45 to 60: Court Filing | Sec 142 NI / Sec 200 CrPC | Private complaint filed in trial court | Engage counsel to track CNR docket on e-Courts. |
| Month 3 to 4: Court Summons | Sec 61 to 69 CrPC | Magistrate issues real summons | Appear through counsel. seek Section 205 exemption. |
| Month 5 to 6: Warrant Escalation | Sec 70 &. 71 CrPC | Bailable warrant followed by NBW order | File Section 70(2) recall with local solvent surety. |
| Month 6+: relief &. NDC | Sec 147 NI Act | deal OTS sanctioned by bank | Joint growing petition filed. complaint dismissed. |
9. Specialized Scenarios: Outstation & Commercial Defaults
NBW defense requires specialized tactics when complicated by interstate jurisdictions. Firm roles. third-party debt assignments.
National lenders often file cases in metro hubs. Our local panel counsel file recall petitions and Section 205 appearance exemptions. Eliminating interstate travel burdens.
For defaults caused by job loss or medical crises. We present checked hardship evidence. Courts routinely recall warrants and grant time for OTS deal.
Under Section 141 NI Act. Non-executive directors are often wrongly impleaded. We establish non-involvement in daily handling to recall warrants against uninvolved partners.
When debts are assigned to ARCs. Assignees must properly substitute themselves on court records. We challenge defective substitutions to settle 50% to 70% OTS waivers.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions: Non-Bailable Warrant Defense
Statutory Citations and Outbound Authority References
CredSettle legal guidance is rooted in legal codes. Reserve Bank of India Master Directions. binding Supreme Court of India precedents:
• Negotiable Instruments Act. 1881: Sections 138. 141. 142. 143A &. 147 (growing of Offenses).
• Code of penal Procedure. 1973: Sections 70(2) (Recall of Warrant). 71. 82. 83. 205. 397 &. 482 (Inherent Powers of High Court).
• Bharatiya Nagarik Suraksha Sanhita. 2023: Sections 72. 73 &. 528 (Modernized penal Procedural Code).
• Supreme Court Precedents: Inder Mohan Goswami v. State of U.P. (2007). Raghuvansh Dewanchand Bhasin v. State of Maharashtra (2012). Damodar S. Prabhu v. Sayed Babalal H. (2010).
valid Legislative &. Redressal Portals: