state staff in India face unique systemic vulnerabilities when private loans defaults occur. Beyond standard money claims. Public servants risk office complications. Departmental inquiries under service conduct rules. harsh workplace abuse by claims agents. Here is the definitive legal summary:
- Civil Matter. Not Misconduct: Loan default is a civil contractual claims. Not a ground for automatic suspension or dismissal.
- Rule 16 CCS Conduct Safe Harbor: Departmental inquiry applies only to habitual misconduct. genuine hardship is by law protected.
- Salary &. Pension Immunity: Section 60 CPC protects basic salary. Meanwhile. GPF. EPF. Gratuity. And pensions are 100% exempt from attachment.
- Zero Workplace abuse: RBI Fair Practices Code strictly prohibits claims agents from visiting offices or calling superiors.
- Confidential 40%. 60% OTS: Direct bank OTS deals eliminate debt cleanly without generating adverse vigilance entries.
1. Debt Economics & Service Vulnerabilities in Government Jobs
state staff across Central Ministries. State Secretariats. PSUs. Defense establishments are often offered pre-approved private loans and credit cards due to secure monthly payrolls. However. Unforeseen life crises such as major health treatments or kin crises can quickly overwhelm a fixed salary structure. This leads to missed EMIs and severe debt stress.
When payments stop. Accounts progress from SMA-0 to SMA-2 and cross into Non-Performing Asset (NPA) status at 90 days. Requiring banks to make strict cash bank reserves. Because no-pledge private loans carry no pledge to seize under the SARFAESI Act. claims firms often exploit the staff&apos. s reputational sensitivity and fear of workplace inquiries rather than pursuing standard civil adjudication.
Crucially. A bank loan default is strictly a civil breach of contract under the Indian Contract Act. Established legal protections exist under service rules and civil law to safeguard the dignity. Livelihood. office standing of public servants facing genuine ruin.
2. Financial Breakdown: Principal vs Inflated Penal Dues
Following default. Trade lenders rapidly inflate dues by adding 24% to 36% annualized extra fees. NACH bounce charges. Legal fees. Within months. Claimed unpaid dues can surge by 35% to 60% above the genuine main loan owed.
Under RBI Fair Lending Directions. Capitalizing extra fees into main loan balances is strictly prohibited. In a One-Time settlement (OTS). The starting baseline is strictly the. Net base loan.Waiving total penalties and late charges.
Representative 180-Day NPA Stressed Asset Audit
Typical Case Profile.For a state staff with an original ₹15,00,000 private loans inflated to ₹19,85,000 after 180 days default. A structured hardship settlement establishes an achievable OTS deal target:
Settling at this realistic threshold clears the bank&apos. s bad debt provision while permanently shielding the staff from ruin.
3. Debt Resolution Matrix: OTS vs Restructuring vs Litigation
Compare the office. Legal. And money trade-offs of key debt relief mechanisms for state staff:
| Resolution Route. | Financial Relief. | Service Record Impact. | Legal Exposure | Timeline | Feasibility |
|---|---|---|---|---|---|
| One-Time settlement (OTS). | 40% to 60% total waiver. | Zero adverse entries. complete rights. | All civil &. Sec 138/25 notices closed. | 30. 60 Days | Recommended |
| Restructuring | 0% waiver. extended tenure. | Service safe. monthly burden stays. | Notices paused if EMIs paid. | 60. 90 Days | Moderate |
| Lok Adalat | 30% to 50% OTS deal. | court consent decree. no vigilance impact. | Non-appealable consent order. | Quarterly | Good Option |
| Court lawsuits. | Zero waiver. high legal fees. | Risk of Sec 60 CPC salary decree. | Prolonged civil summons &. trial. | 2. 5 Years | Risky |
| Passive Default | Penalties compound continuously. | Risk of workplace abuse &. Rule 16 query. | Ex-parte decrees &. bailable warrants. | Indefinite | Avoid |
4. Technical CIBIL Algorithm & Credit Rebuilding Pathways
Loan default does not permanently damage creditworthiness. Credit bureaus (CIBIL. Experian. CRIF. Equifax) calculate scores based on five standardized weight factors:
DPD track record across active accounts.
unpaid debt vs total credit limit.
Longevity of established credit lines.
Balance between secured and no-pledge debt.
Hard credit checks within trailing 12 months.
Once an OTS is finalized and a No Dues letter is issued. Section 21 of the Credit Information firms (Regulation) Act (CICRA) enables clients to ensure accurate CIBIL desk reporting. By using a secured fixed-deposit credit card and maintaining low use. Credit scores recover back to 750+ within 12 to 18 months.
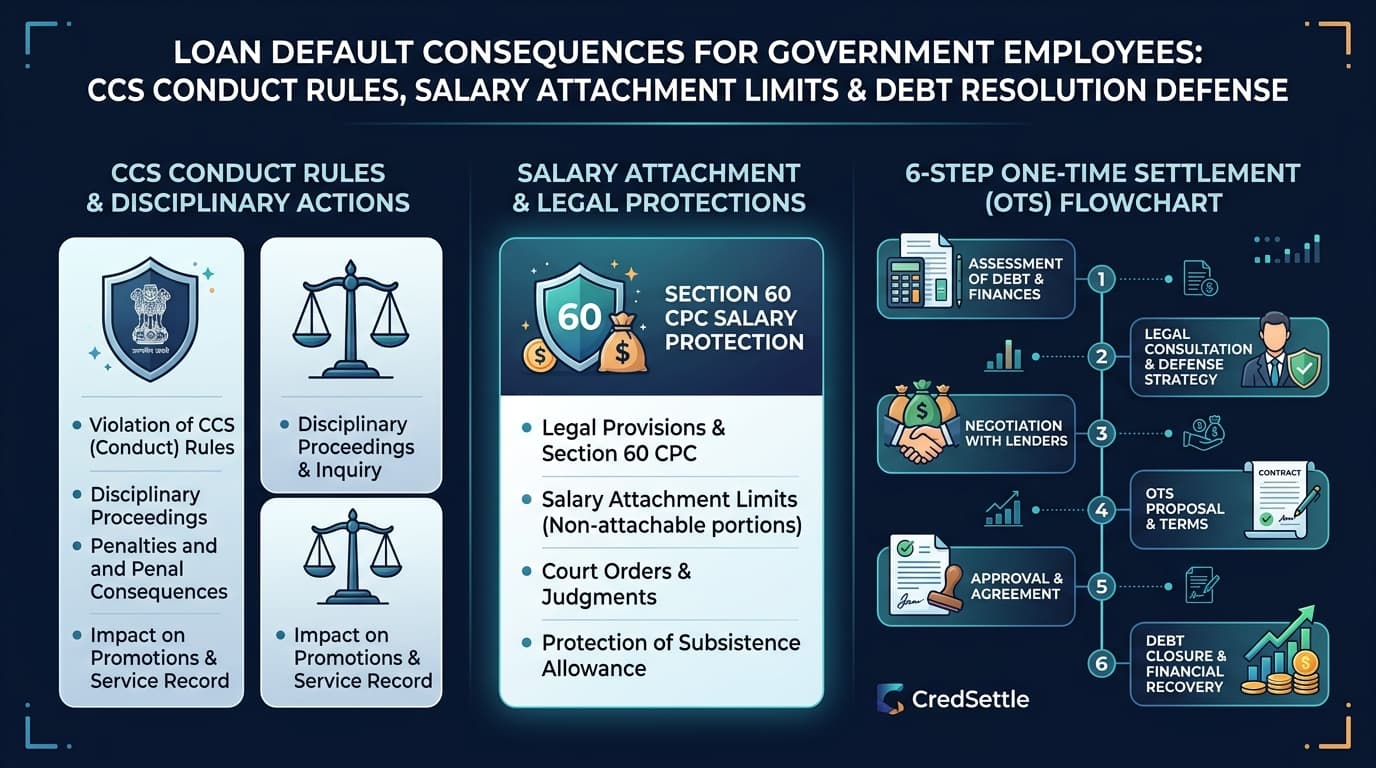
Visual Blueprint: Government Servant Debt Defense Protocol
Review the full visual architecture covering CCS conduct rules. Section 60 CPC salary exemptions. The 6-step One-Time settlement roadmap engineered mainly for state staff:
5. Step-by-Step SOP: 6-Stage Government Servant Resolution
Our structured 6-stage settlement protocol resolves debt while protecting service standing:
We audit the complete loan record. Disputing compound extra fees. Unlawful bounce charges. Unapproved fees to establish the genuine main loan baseline.
We compile documented health and kin hardship proofs alongside CCS Conduct Rule declarations. Showing genuine unforeseen ruin rather than habitual indebtedness.
Formal legal help is served straight to the bank Stressed Asset boards. Asserting RBI Fair Practice protections to bar agent visits to state secretariats.
Our specialists settle straight with bank nodal executives. Leveraging NPA bank reserves mandates to secure a 40% to 60% OTS deal waiver across all dues.
We vet the bank formal OTS sanction letter to ensure full debt waiver. Withdrawal of legal notices. Guaranteed issuance of a No Dues letter.
The payout sum is remitted straight to the loan account. Followed by acquiring the formal NDC and updating CIBIL records in compliance with CICRA norms.
6. Statutory Notice Defense: CCS Rules, NI Act & CPC Rights
Understanding the exact legal scope of legal notices empowers state servants to respond effectively:
Rule 16 mandates avoiding habitual indebtedness. However. Submitting a timely factual hardship report to the Disciplinary formal for unforeseen money ruin insulates the staff from misconduct charges.
lenders cannot attach full pay. Section 60 strictly exempts the first ₹1,000 plus two-thirds of remainder salary. Capped at 24 months. Meanwhile, GPF, EPF. Pensions are 100% immune from attachment.
Notices for bounced cheques or NACH auto-debits require a prompt lawyers response establishing lack of fraudulent intent and proposing bilateral settlement. Averting court summons.
Under Supreme Court rulings in. TRF Ltd. and Perkins EastmanBanks cannot unilaterally appoint a sole judge. Such arbitrations can be challenged under Section 12(5) as voidable.
Workplace claims abuse is Strictly Prohibited by RBI.
RBI Master Directions strictly prohibit claims agents from visiting state offices. Contacting superiors or colleagues. Calling outside 8:00 AM to 7:00 PM. Any breach can be reported straight to the RBI agents.
7. 3-Tier Escalation Matrix: Institutional Redressal Hierarchy
If lenders use coercive tactics. Invoke this 3-tier legal redressal mechanism:
Principal Grievance Redressal Officer (GRO)
Written reports to the bank internal GRO detailing agent abuse or demanding account correction. relief: 7. 10 days.
Principal Nodal Officer (PNO)
Appellate reports to the bank main loan Nodal agents to suspend harsh claims. relief: 14. 21 days.
RBI Integrated Ombudsman (cms.rbi.org.in)
Online legal reports under the RBI Integrated agents Scheme. 2021 for binding RBI claims adjudication.
8. Chronological Timeline: Default to Complete Debt Discharge
Strategic legal countermeasures at every stage of the loan default lifecycle:
| default Phase. | Banking Milestone. | Lender Actions & Risks. | Recommended Action. |
|---|---|---|---|
| Days 1. 30 | SMA-0 Stage | Automated calls. Initial late fees. | Review budget. halt high-rates roll-overs. |
| Days 31. 60 | SMA-1 Stage | claims calls &. firm assignment. | Issue anti-abuse notice against office visits. |
| Days 61. 90 | SMA-2 Stage | Final demand notices. Section 25 warnings. | Conduct audits &. claims penalty fees. |
| Days 91. 180 | NPA Classification. | Bad debt status. cash bank reserves starts. | Initiate formal One-Time settlement (OTS) proposal. |
| Months 6. 9 | OTS Sanction &. Closure. | Bank issues OTS deal sanction letter. | pay OTS amount straight. secure No Dues letter. |
9. Specialized Scenarios: Central, State, Defence & PSU Staff
Tailored debt relief plans across different wings of public service:
Central Civil Services (CCS) & Secretariat Personnel
Officials governed by CCS (Conduct) Rules. 1964 receive confidential legal legal help straight with bank headquarters. Ensuring complete rights from departmental vigilance.
State Government & District Administration Staff
We defend state staff from banned local bank salary deductions. Asserting Section 60 CPC exemptions and settling direct OTS terms.
Defence & Paramilitary Forces (Army, Navy, Air Force, CAPF)
Armed forces personnel facing strict service discipline receive expedited settlement legal help to safeguard unit service records and pledge clearances.
PSU & Nationalised Bank Staff (ARC Assignments)
For PSU staff whose debt is sold to Asset Reconstruction firms (ARCs). We capitalize on the ARC&apos. S deep portfolio purchase discounts to secure fast. High-waiver deals.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
10. Frequently Asked Questions: Government Employee Debt Rights
Click on any question below to explore authoritative legal answers checked by our debt relief workers: