Ex-Parte Decree in a Bank Loan Case: How to Set It Aside
Has a bank secured a default decree without serving summons? Learn how to file under Order 9 Rule 13 CPC. Stay coercive execution. Dispute compound rates. settle an affordable OTS.
1. Debt Economics & Ex-Parte Default Dynamics in Loan Recovery
When retail clients face severe money disruptions from job loss. Medical emergencies. Firm downturns. Clean loans often fall delinquent. Once non-payment crosses 90 days. Lenders classify the account as a Non-Performing Asset (NPA) under Reserve Bank of India prudential norms. This mandates substantial Tier-1 capital provisioning. Creating pressure on claims wings to secure fast judicial decrees.
To expedite claims. Banks file summary suits under Order XXXVII CPC. Ordinary money suits. DRT Original Applications. Yet. Summonses are routinely dispatched to outdated tenancy addresses or served via substituted newspaper publication in obscure daily papers. Unaware of the court steps. The clients fails to appear. Leading the civil court to proceed ex-parte under Order IX Rule 6(1)(a) CPC and pass a default monetary decree with high post-decree rates.
clients usually discover the decree when executing courts issue attachment warrants or salary garnishee orders. Fortunately. Indian civil law provides clear legal safeguards under Order IX Rule 13 CPC to set aside default decrees. Halt coercive execution. restore the clients&apos. s right to defend the case and settle the debt.
2. Financial Breakdown: Principal vs Inflated Decree Claims
In uncontested ex-parte steps. Banks present computerized statements that add contractual rates. Compound penal levies. Late charges. legal fees. Without defense counsel to cross-examine ledger calculations under the Bankers&apos. Books Evidence Act. Courts decree the entire claim with future rates at 18% per annum.
The table below illustrates a representative money audit of a ₹25 Lakhs clean loan default that swelled into an ex-parte decree. Contrasting the claimed dues against realistic deal OTS targets:
Representative money Breakdown &. deal Target
Note: deal closures are settle on checked hardship and summons service defects. Payments are remitted straight against an valid bank OTS letter.
3. Legal Remedies Matrix: Setting Aside vs Appeal vs Inaction
clients facing an ex-parte decree have distinct procedural remedies under the Code of Civil Procedure. 1908 depending on whether they challenge service defects or legal merits:
| Judicial Remedy | Governing Statute | Limitation Period | Court Forum | Pre-Deposit | Strategic Value |
|---|---|---|---|---|---|
| Set Aside Application | Order IX Rule 13 CPC | 30 Days from Knowledge | Same Trial Court | NO | Reopens trial on merits and stays coercive execution |
| Regular First Appeal (RFA) | Section 96(2) CPC | 30 to 90 Days | Appellate Court / HC | Security discretionary | Challenges substantive errors and rates computations |
| Review Petition | Section 114 / Order 47 | 30 Days from Decree | Same Trial Court | NO | Rectifies patent errors of law or overlooked payments |
| Lok Adalat closure | Legal Services Act 1987 | Any Stage with Consent | Lok Adalat Bench | NO | Final consent decree with full waiver of compound fees |
| Inaction / Ignoring Notice | Default Enforcement | N/A | Executing Court | 100% Demand Due | Leads to salary garnishee and bank account freeze |
4. CIBIL Impact & Credit Bureau Restoration Strategy
When a court enters an ex-parte decree. Lenders report a ". Suit Filed". or ". Decreed". Remark to TransUnion CIBIL. Equifax. Experian. CRIF High Mark. This triggers an fast score decline of 120 to 180 points and results in automated rejections across bank risk engines for any future credit cards. Home loans. firm credit.
Setting aside the decree halts ongoing deterioration. Once resolved via deal OTS. Lenders are statutorily required under Section 21 of the Credit Information Companies (rule) Act. 2005 to update the account balance to zero with ". Settled". or ". Closed". status within 30 days. clients can then rebuild their score above 750 over 12 to 18 months through disciplined secured credit.
Visual Blueprint: 6-Step Defense Roadmap to Set Aside Ex-Parte Decrees
Review the step-by-step roadmap below for challenging default decrees. Obtaining an execution stay. reaching a final loan closure:
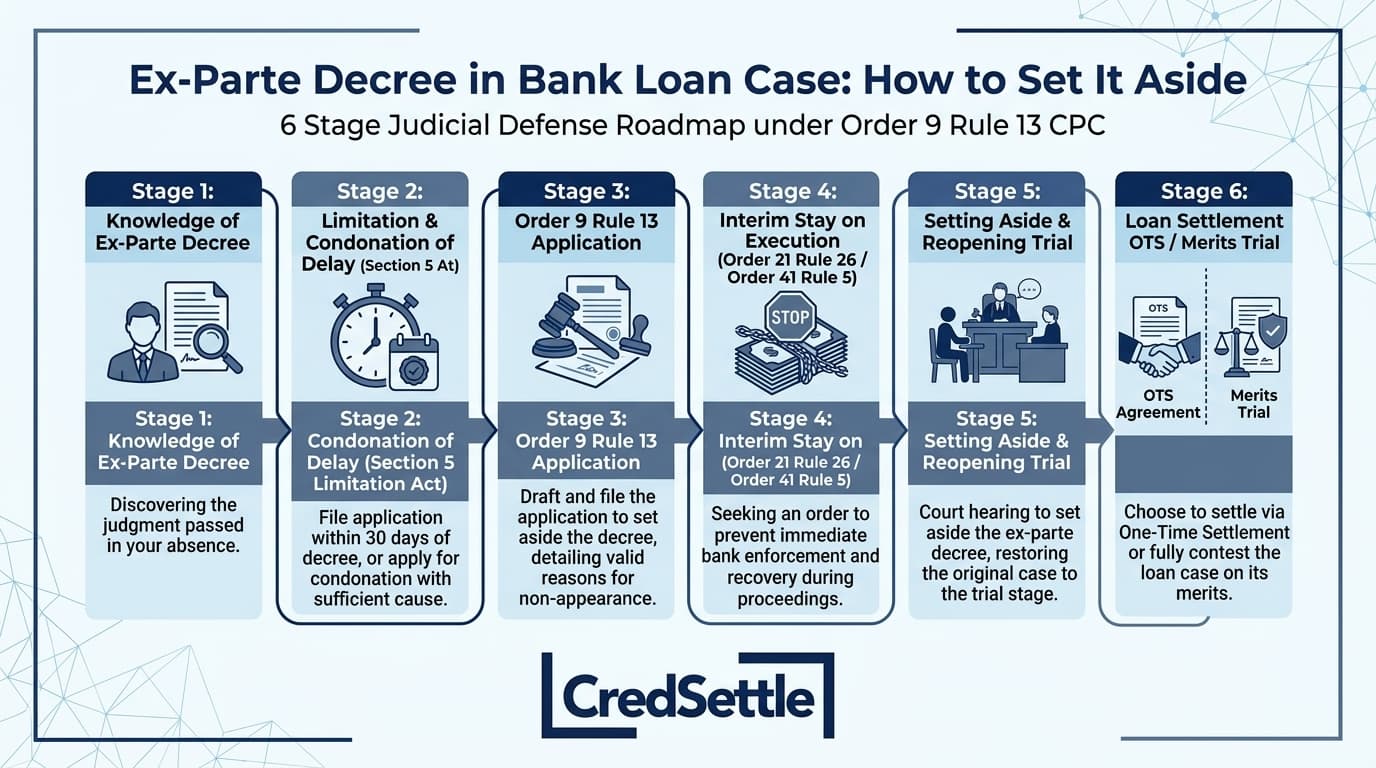
5. 6-Stage SOP: Protocol to Set Aside Bank Loan Default Decrees
Vacating a default decree requires methodical execution across judicial timelines. Follow this six-stage standard operating protocol:
Decree Discovery &. Judicial File Inspection
Obtain signed copies of order sheets. Plaint. process server reports to establish whether summons was sent to an outdated address or published improperly.
Drafting Order 9 Rule 13 Application &. Delay Condonation
Prepare the set-aside application with a supporting affidavit. If beyond 30 days. Attach a Section 5 Limitation Act petition citing genuine reasons for absence.
Filing Interlocutory Stay on Execution steps
Move an urgent application under Order XXI Rule 26 and Section 151 CPC to restrain bank account freezes and asset attachments during the set-aside plea.
Judicial Arguments &. Establishing Sufficient Cause
Argue before the court citing Supreme Court precedents (G.P. Srivastava. Sushil Kumar Sabharwal) to prove defective service and secure an order setting aside the decree.
Decree Set Aside. Trial Reopened &. Written Statement Filed
With the suit restored to trial. Submit a thorough Written Statement challenging unapproved compound penal rates and presenting documented hardship.
Bilateral deal OTS. Suit Withdrawal &. Closure NDC
Engage the bank&apos. S Zonal Stressed Assets Desk to finalize a 40% to 60% deal OTS. Remit closure funds. File joint withdrawal terms. obtain your No Dues letter.
6. Statutory Notice Defense: Order 9 Rule 13 CPC & Summons Rights
Defending against default bank claims decrees is based on four core legal safeguards under the Code of Civil Procedure and Supreme Court rulings:
Affixation without verifying residence or newspaper publication in obscure daily papers violates mandatory service rules and renders ex-parte orders voidable.
Under G.P. Srivastava v. R.K. Raizada (2000). Courts must adopt a liberal approach to ensure disputes are decided on substantive merits rather than procedural default.
The Supreme Court held in (2002) 5 SCC 377 that general knowledge of litigation does not dispense with the strict legal duty of proper summons service under Order 5 CPC.
Executing courts hold power under Order 21 Rule 26 and Section 151 CPC to stay claims steps. Preventing account attachment while set-aside pleas are heard.
7. 3-Tier Escalation Matrix: Judicial & Institutional Redressal
When facing execution steps or unresponsive bank desks after an ex-parte decree. Escalate through this structured 3-tier framework:
fast Execution Restraint &. Grievance Escalation
File an urgent stay plea under Order 21 Rule 26 CPC and submit a formal representation to the Bank PNO requesting a hold on coercive claims pending OTS review.
Appellate &. legal watch Remedies
If the trial court rejects the set-aside application. File a miscellaneous appeal under Order 43 Rule 1(d) CPC or invoke High Court watch jurisdiction under Article 227.
RBI Complaint on CMS Portal (cms.rbi.org.in)
If the bank deploys abusive agents or violates RBI Fair Practices Code. Lodge a formal RBI complaint on cms.rbi.org.in for rapid RBI officer action.
8. Chronological Milestones: Summons to Set-Aside & Resolution
Key procedural milestones in challenging an ex-parte bank claims decree and concluding an out-of-court closure:
| Procedural Phase | Judicial Milestone | Statutory Limitation | Strategic Action |
|---|---|---|---|
| Day 1 | Knowledge of Ex-Parte Decree | Article 123 trigger | Apply for signed copies and inspect service records |
| Days 15-30 | Order 9 Rule 13 &. Stay Filing | 30 days under Article 123 | File set-aside petition. Section 5 condonation &. stay application |
| Days 45-60 | Stay Hearing &. Arguments | Court schedule | Argue summons defect and secure interim execution stay |
| Months 3-4 | Decree Set Aside &. Suit Restored | Trial reopening | Submit Written Statement and initiate OTS talks |
| Months 5-6 | deal OTS &. Suit Withdrawal | Final closure | Remit OTS funds. Secure NDC and update CIBIL records |
9. Specialized Scenarios: Complex Ex-Parte Loan Disputes
Ex-parte decrees often arise in exact scenarios requiring tailored legal responses:
clients Relocation &. Outdated KYC Defaults
clients who relocated often find summonses were dispatched to old rental addresses. Providing lease pacts and updated Aadhaar records serves as conclusive evidence of non-service under Order 9 Rule 13.
own Guarantors &. Co-clients Impleaded Unbeknownst
Co-clients or guarantors decreed without separate summons can assert independent legal defenses under Sections 133 to 141 of the Indian Contract Act. 1872 regarding creditor laches and contract variations.
Ex-Parte claims letters in DRT
For loans above ₹20 Lakhs in DRT. Clients can apply to recall ex-parte claims letters under Section 19(25) of the RDB Act and Rule 12(5) of the DRT Procedure Rules by proving non-receipt of notice.
Debt Assigned to Asset Reconstruction Companies (ARCs)
When bad debts are assigned to ARCs at steep discounts. Challenging default decrees provides significant leverage to conclude deeply discounted closures with swift No Dues letters.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions: Setting Aside Ex-Parte Bank Decrees
Click on any question below to explore authoritative legal answers checked by our banking compliance and debt relief experts:
Statutory References & Official Regulatory Citations
- Code of Civil Procedure. 1908: Order V Rules 17 to 20 (Summons Service). Order IX Rules 6 and 13 (Ex-Parte Decrees and Setting Aside). Order XXI Rule 26 (Stay of Execution). Section 151 (Inherent Powers).
- Limitation Act, 1963: Article 123 (30-day limitation for setting aside ex-parte decrees) and Section 5 (Condonation of delay for sufficient cause).
- Supreme Court Precedents: G.P. Srivastava v. R.K. Raizada (2000) 3 SCC 54 (Liberal sufficient cause doctrine) and Sushil Kumar Sabharwal v. Gurpreet Singh (2002) 5 SCC 377 (Strict summons service rules).
- Claims of Debts and Bankruptcy Act. 1993: Section 19(22), 19(25). DRT Procedure Rules. 1993. Rule 12 (Recalling ex-parte claims letters).
- Credit Information Companies (rule) Act. 2005: Section 21 (Mandatory credit desk updates post-closure).