Armed Forces & Military Personnel Loan Default Consequences
Authoritative legal roadmap for Indian Army. Navy. Air Force. And Paramilitary personnel facing loan defaults. Understand service rules. Stop claims calls to your unit. And secure 40% to 55% waivers.
- Civil police area: no-pledge loan default is purely a civil contractual claims. Never a military crime.
- Court Martial Myth: Serving personnel cannot be court-martialed. Demoted. Or dismissed for civil money debts.
- Unit abuse Prohibited: Calls. Visits. Or demand notices to Commanding agents violate RBI conduct directives.
- Pay Attachment Immunity: Section 28 Army Act and Section 60 CPC bar automatic extrajudicial salary deduction.
- daily work Deployment Shield: The Indian Soldiers (lawsuits) Act grants legal protections during forward postings.
- bank Haircuts: Bank credit boards routinely sanction 40% to 55% waivers on genuine hardship grounds.
- Service Record safety: Formal One-Time settlement prevents lawsuits warrants and safeguards pledge clearance.
- Definitive Legal Closure: Traceable loan remittance secures an formal No Dues letter and closes the debt risk.
1. Military Service Rules: Army Act vs. Civil Recovery
Members of the Indian Armed Forces. This includes the Army. Navy. Air Force. Paramilitary forces like CRPF and BSF. Occasionally encounter severe debt stress from private loans or kin crises. harsh claims firms often exploit a soldier&apos. S discipline by threatening court-martial steps. Service dismissal. military arrest.
Under Indian law. An unpaid loan is purely a civil contractual breach governed by the Indian Contract Act. 1872. Military courts-martial under the Army Act. 1950 apply strictly to service misconduct and disciplinary infractions. Never to civil ruin. Service personnel cannot be discharged or demoted for trade debt default.
Additionally. Section 28 of the Army Act and Section 60(1)(g) of the CPC protect military pay and pensions from summary attachment. Once an late loan reaches 90-day NPA classification. RBI bank reserves rules encourage banks to settle a One-Time settlement rather than pursuing protracted lawsuits.
2. Financial Forensics: Principal vs. Inflated Penal Charges
When installments default during field postings or health crises. Banking software rapidly inflates balances with 24% to 36% compound extra fees. Repetitive ₹500 NACH bounce penalties. Office fees. Swelling total claims 35% to 50% above actual borrowed main loan.
A audits isolates genuine remaining main loan from penal additions. Backed by authenticated hardship proofs. Bank credit boards grant 100% waivers on penalty charges and approve 40% to 55% main loan haircuts for final OTS deal closure.
| Financial Component. | Pre-Settlement Ledger. | Credit Committee Waiver. | Final Payable Amount. |
|---|---|---|---|
| remaining base loan. | ₹10,50,000 | 45% Core Haircut (₹4,72,500). | ₹5,77,500 |
| Accrued Penal &. late rates. | ₹3,75,000 | 100% Complete Waiver. | ₹0 |
| NACH Bounces &. Late Surcharges. | ₹75,000 | 100% office Waiver. | ₹0 |
| Total OTS deal Evaluation. | ₹15,00,000 | ₹9,22,500 Total Relief (61.5% Savings). | ₹5,77,500 Final OTS. |
3. Debt Resolution Pathways: Defense Personnel Comparison
Evaluating debt relief options requires weighing legal safety against cost and service impact. An bank One-Time settlement delivers definitive closure and main loan relief while halting claims abuse.
| Resolution Mechanism. | Financial Relief. | Service & Legal Protection. | CIBIL Bureau Status. | Standard Timeline. |
|---|---|---|---|---|
| One-Time settlement (OTS). | 40% to 55% loan cut. | Full Legal Immunity &. Notice Withdrawal. | Settled / Zero Balance. | 30 to 60 Days |
| Tenure Restructuring. | 0% main loan Haircut (Higher rates). | Conditional on Timely Servicing. | Restructured Account. | 45 to 90 Days |
| Civil Court lawsuits. | High Legal legal help Costs. | Adversarial Decrees &. Summons. | Suit Filed / Wilful Default. | 2 to 5 Years |
| National Lok Adalat. | 30% to 45% Mutual Haircut. | Non-Appealable Consent Award. | Settled in Lok Adalat. | Quarterly Sittings. |
| Unmanaged Default. | Exponential Penal growing. | PSSA 25 / NI 138 Summons Risk. | Written Off / late. | Indefinite Stress. |
4. CIBIL Bureau Dynamics & Military Security Clearance
Credit bureaus assess credit scores primarily based on payment history (35%) and use (30%). Loan defaults trigger consecutive 30. 60. 90+ DPD marks. Depressing credit scores by 130 to 200 points.
While money debts do not impact day-to-day duties. Pending court summonses can raise flags during sensitive intelligence or foreign deployment pledge screenings. An authorized settlement eliminates active default flags and allows rebuilding a 750+ score over 18 to 24 months. Under Section 21 of CICRA 2005. Paying the waived variance later converts the entry to ". Closed".
5. Defense Personnel Loan Settlement Roadmap
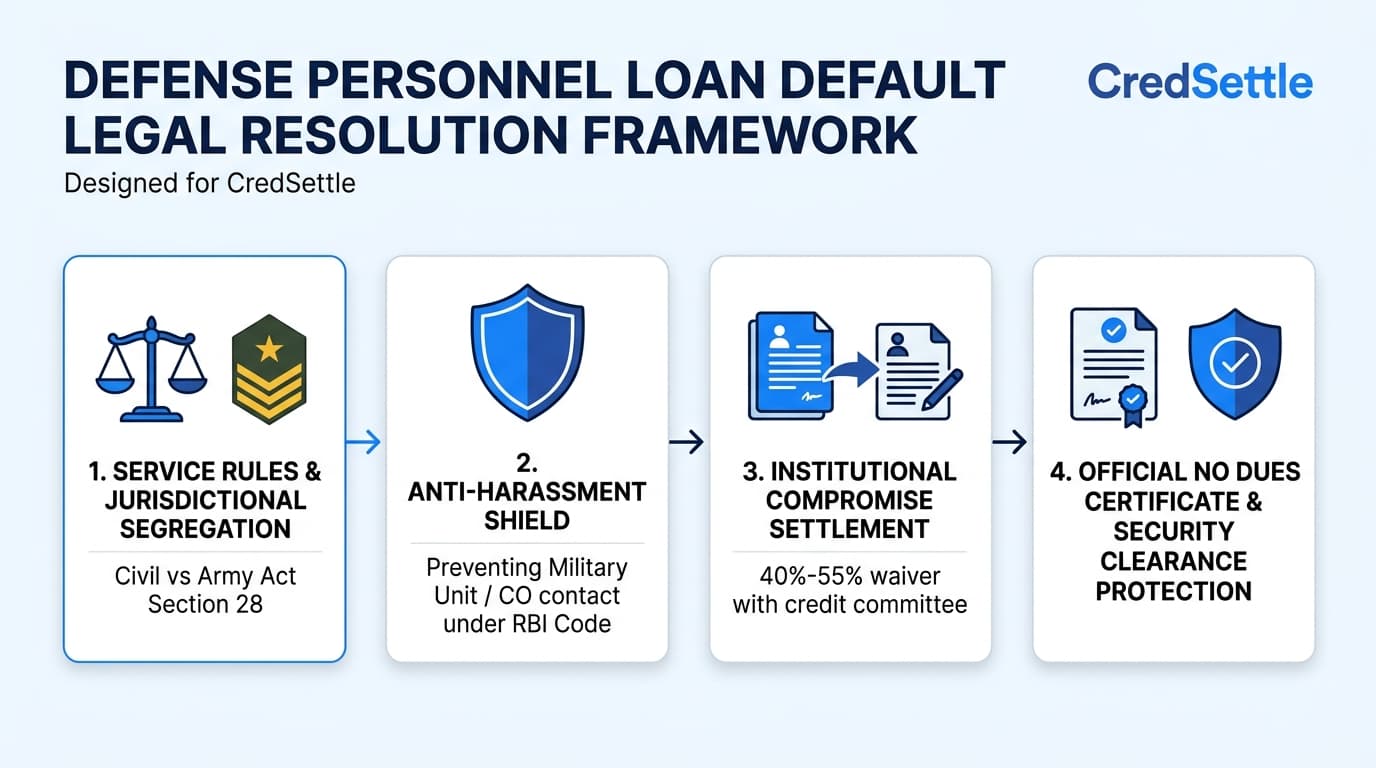
This visual flowchart outlines the 4-step rules to shield defense personnel from unit contact. Protect salary rights. Secure sanctioned bank OTS deals.
6. Six-Stage SOP: Negotiating Armed Forces Loan Relief
Resolving debt as a defense staff requires strict bank protocol. Follow this 6-stage rules to achieve an formal settlement without third-party interference.
1Stage 1: Forensic Loan Account Audit
Audit loan records from disbursal. Segregate core remaining main loan from 24% to 36% compound extra fees and bounce charges to establish the true net baseline.
2Stage 2: Military Hardship Dossier Compilation
Assemble checked hardship paperwork including deployment records. Dependent health bills. Pay slips proving genuine non-wilful inability to repay.
3Stage 3: Legal Representation & Anti-Harassment Notice
Serve formal legal notice to the bank zonal head and PNO citing RBI rules. Expressly prohibiting calls or visits to military units or commanding agents.
4Stage 4: Bilateral Credit Committee Negotiations
Present the hardship petition before the credit boards. Leveraging salary safety under Section 28 Army Act to secure 100% penal waiver and a 40% to 55% haircut.
5Stage 5: Official Settlement Sanction Letter Vetting
Verify that the sanction letter is on formal bank letterhead with authorized email provenance. Correct tranche schedules. An explicit legal notice withdrawal clause.
6Stage 6: Direct Remittance & No Dues Certificate
pay the OTS deal sum straight into your loan account via RTGS/NEFT. Verify ledger balance zeroing. Receive the formal No Dues letter within 30 to 45 days.
7. Statutory Defense: PSSA 25, NI 138 & Commanding Officer Rights
When default reaches 90 to 120 days. Banks issue legal notices. Timely legal replies protect your service standing and redirect claims toward settlement.
Issued for bounced electronic mandates. Serving a formal reply within 30 days proving debt stress refutes penal intent and steers steps into OTS deals.
Served for dishonored pledge cheques. A reply within 15 days establishing that cheques were undated pledge pledge bars summary magistrate steps.
Under Supreme Court rulings in Perkins Eastman and TRF Ltd. Unilateral judge appointments by banks are void. Filing Section 12(5) objections stalls steps.
RBI Fair Practices Code strictly prohibits contacting employers or military units. Sending claims letters to cantonments is a severe breach subject to agents penalties.
8. Three-Tier Escalation Matrix for Defense Personnel
If claims firms harass your unit or refuse settlement. Escalate through the 3-tier RBI redressal rules.
| Grievance Tier | Designated Banking Authority. | Turnaround Time | pay & Scope of Intervention. |
|---|---|---|---|
| Level 1: GRO | Bank Grievance Redressal agents. | 7 to 10 Working Days. | Investigates banned abuse. Removes disputed penal fees. And transfers file to settlement teams. |
| Level 2: PNO | main loan Nodal agents (Bank HQ). | 14 to 21 Working Days. | Intervenes on unit contacts. Cancels claims mandates. And oversees credit boards waivers. |
| Level 3: RBI agents. | Reserve Bank Integrated agents. | 30 Days Post-PNO. | Binding adjudication via cms.rbi.org.in with power to award damages for code violations and abuse. |
9. Procedural Default Timeline: Default to Resolution
Identifying your loan default stage helps pinpoint the optimal window for settling deep main loan haircuts.
| Timeline Interval. | Asset Classification. | Bank Recovery Actions. | Recommended Borrower Strategy. |
|---|---|---|---|
| Day 1 to 30 | SMA-0 | Automated payment reminders and soft telephonic claims calls. | Assess cashflow. avoid taking fresh high-rates app loans. |
| Day 31 to 60 | SMA-1 | Escalated telecaller outreach and preliminary loan recall notices. | Compile health. Deployment. And military hardship paperwork. |
| Day 61 to 90 | SMA-2 | Final pre-NPA warnings and third-party claims firm allocation. | Assert RBI Fair Practices Code rights against abusive telecallers. |
| Day 91 to 120 | NPA Classification. | strict loan bank reserves. transfer to Stressed Asset Desk. | Initiate audits and engage debt settlement specialists. |
| Day 121 to 180 | Prime OTS Window. | Issuance of Section 25 PSSA notices or hearing demand letters. | settle with credit boards for 40% to 55% waiver. |
| Month 6 and Beyond. | Write-off / ARC Transfer. | Ex-parte arbitral filings or debt sale to Asset Reconstruction firms. | pay sanctioned OTS deal sum and obtain stamped NDC. |
10. Specialized Military Scenarios: Postings & ARCs
Tailoring debt relief plans to unique military conditions ensures legal safety and money claims.
Forward & High-Altitude Postings
Under the Indian Soldiers (lawsuits) Act. 1925. Legal steps against personnel serving in remote or daily work zones can be formally stayed. This provides time for OTS deals.
Defence Salary (DSP) Account Liens
Unilateral debit freezes on salary accounts violate Section 28 Army Act and RBI norms. Legal legal help promptly revokes banned bank liens.
Emergency Medical Debt Spirals
Unplanned healthcare costs often lead to multi-lender app debt. Consolidating these claims into a unified dossier allows deep collective haircuts.
ARC Portfolio Assignments
When debts are transferred to Asset Reconstruction firms at deep discounts. Skilled negotiators routinely secure deals exceeding 60% relief.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions: Defense Loan Default
Clear. checked answers addressing critical questions on military loan defaults. Service regulations. settlement protocols.
Official Regulatory Framework & Military Citations
- The Army Act. 1950 (Act No. 46 of 1950): Section 28. Immunity from Arrest for Debt and safety of Military Pay.
- Indian Soldiers (lawsuits) Act. 1925 (Act No. 4 of 1925): safety of Soldiers in Court lawsuits and Suspension of steps.
- Code of Civil steps. 1908 (CPC): Section 60(1)(g). Inviolable Exemption of Military Stipends and Pensions from Attachment.
- Reserve Bank of India (RBI): Master Direction on Fair Practices Code for Banks and NBFCs (Updated 2026).
- Payment and settlement Systems Act. 2007: Section 25. Rules Governing Electronic Mandate Dishonour.
- Hearing and talks Act. 1996: Section 12(5) and Section 21. Ineligibility of Unilateral Arbitrators (Perkins Eastman / TRF Ltd).