Legal Notice to Bank for Mental Harassment
Facing abusive claims agents. Unlawful home visits. Or workplace defamation? Learn how to serve an authoritative legal notice. Hold bank leadership vicariously liable. Claim legal damages while securing debt relief.
- Vicarious debt risk: Banks are legally accountable for threats and abuse by claims agents.
- Strict Calling Hours: claims calls and visits are permitted strictly between 8:00 AM and 7:00 PM.
- Third-Party Ban: Calling relatives. Employers. Or friends is strictly illegal under RBI rules.
- Notice to Bank MD: lawyers notice halts agent abuse and transfers your file to bank legal.
- OTS settlement: Documented agent abuse provides leverage to settle a 40% to 55% waiver.
1. Legal Basis: Bank Liability for Recovery Abuse
When an person encounters genuine economic distress such as company downsizing. Severe health crises. Firms liquidity crises. No-pledge private loans and credit cards rapidly transition through default stages. Under RBI prudential norms. An account past due for 30 days becomes Special Mention Account 1 (SMA-1). Advances to SMA-2 at 60 days. Is classified as a Non-Performing Asset (NPA) upon crossing the 90-day threshold. This RBI reclassification mandates 15% to 100% Tier-1 cash provisioning by the lending institution. Creating intense internal pressure on credit risk divisions to recover cash at any cost.
To bypass daily work constraints and avoid costly lawsuits in civil courts. Banks and Non-Banking money Companies (NBFCs) routinely outsource overdue loan portfolios to third-party claims firms. These firms operate on high-incentive contingency commission models. Often earning 15% to 30% of every rupee extracted from overdue clients. Because claims agents have no direct employment ties with the bank and work under cutthroat monthly targets. They systematically resort to coercive tactics. Steady abusive telephone calling. Unannounced home invasions. Unlawful contact with employers.
The Supreme Court of India has firmly established that banks cannot insulate themselves behind outside claims contracts. Under the established doctrine of vicarious debt risk. A main loan is legally accountable for wrongful acts executed by its authorized agents during the course of debt claims. Issuing a formal legal notice straight to the Managing Director and main loan Nodal Officer pierces this company shield. Exposing systemic non-compliance with the Reserve Bank of India Fair Practices Code and creating undeniable bank accountability.
2. Financial Compensation: Calculating Mental Damages
When clients default. Lenders routinely inflate unpaid dues by loading compounding penal interest rates (often 24% to 36% per annum). Bounce charges, claims visit fees. Arbitrary legal office levies onto the ledger. A main loan debt of ₹5,00,000 can rapidly snowball into a claimed balance exceeding ₹8,20,000 within twelve months of default. This inflated figure is then used by claims agents as psychological leverage to intimidate clients into desperate. Unsustainable refinancings.
In Indian tort jurisprudence and clients law. Unlawful claims practices generate enforceable money claims against the bank. Under Section 39 of the clients safety Act. 2019. Clients claims Redressal Commissions are empowered to award large punitive damages for mental agony. Physical trauma. Abuse. Loss of expert reputation caused by deficiency in banking services. Concurrently. Serving a structured legal notice that quantifies documented abuse allows clients to neutralize inflated penalty charges and settle a clean One-Time settlement (OTS) calculated purely against the unbundled base loan.
Representative 180-Day Default: Ledger Inflation vs. Legal OTS Target
Case Study: no-pledge private loans with ₹5,00,000 released main loan.
Includes ₹3,45,000 in compound penalty charges. Late fees. GST levies. And third-party claims commissions.
Net actual base loan after deducting previously serviced EMIs from the original disbursement.
Realistic 40% to 50% settlement window secured by CredSettle through legal notice and abuse defense.
Strategic Insight: Serving a legal notices shifts the discussion from raw numbers to bank debt risk. When faced with documented proof of agent misconduct. Bank legal officers readily eliminate total penal interest and accept a OTS deals to avert RBI audits and clients court penalties.
3. Legal Forum Matrix: Comparing Redressal Routes
When confronting relentless claims abuse. Clients have several legal avenues available under Indian law. Choosing the correct sequence of actions determines whether abuse stops promptly and whether you obtain money relief or remain entangled in protracted claims:
| Redressal Avenue. | Governing Authority & Law. | Immediate Harassment Halt. | Damages & Compensation. | Timeline to Result. | Settlement Impact. |
|---|---|---|---|---|---|
| lawyers Legal Notice to Bank. | Law of Torts &. RBI Master Directions. | fast (48 to 72 Hours). | Demands up to ₹20 Lakhs in notice. | 15 to 30 Days | Maximum OTS Leverage (40%-55%). |
| RBI Integrated Ombudsman. | RBI Ombudsman Scheme 2021. | High (upon notice admission). | Up to ₹1 Lakh mental agony + ₹20L loss. | 30 to 60 Days | High (regulator scrutiny forces waiver). |
| Police FIR / GD Entry. | BNS Sections 308, 351, 79. | Moderate (halts physical visits). | Zero (Criminal court penalty only). | Variable (police discretion). | Moderate (criminal pressure on agents). |
| clients Forum reports. | clients safety Act 2019. | Moderate (subject to stay application). | Unlimited (legal payout). | 6 to 18 Months | High (settled via Lok Adalat/mediation). |
| Passive Inaction &. Silence. | None (Unrepresented Default). | Zero (abuse escalates). | Zero (forfeits all rights). | Indefinite distress. | Zero (ex-parte legal actions). |
4. CIBIL Impact: Dispute Tagging and Credit Repair
Credit Information Bureau (India) Limited (CIBIL) and peer bureaus (Experian. Equifax. CRIF High Mark) calculate your three-digit credit score based on five strict algorithmic parameters: Payment History (35% weight). Credit use Ratio (30% weight). Credit History Duration (15% weight). Credit Mix (10% weight). New Credit Inquiries (10% weight). When an account defaults. 30-plus DPD (Days Past Due) and subsequent NPA tags decimate your score by 120 to 250 points. Locking you out of formal banking channels.
Crucially. When a bank engages in unlawful abuse or misreports disputed amounts. Clients can invoke legal remedies under Section 21 of the Credit Information Companies (Regulation) Act (CICRA). 2005. Under CICRA rules. Credit institutions are legally obligated to ensure data accuracy and must log an active ". Disputed". Tag within 30 days of receiving a formal grievance. Once your legal notice prompts an internal inquiry and an agreed OTS deals. The lender must report the account as settled or closed and update the balance to zero within 45 days.
Following settlement remittance and issuance of the No Dues letter. Clients can submit the settlement proof straight through the CIBIL online claims relief portal. By combining your bank NOC with the legal notice relief dossier. Your CIBIL record is updated to a clean status. This allows your credit score to steadily recover to 750+ over a 12 to 18-month credit rebuilding trajectory.
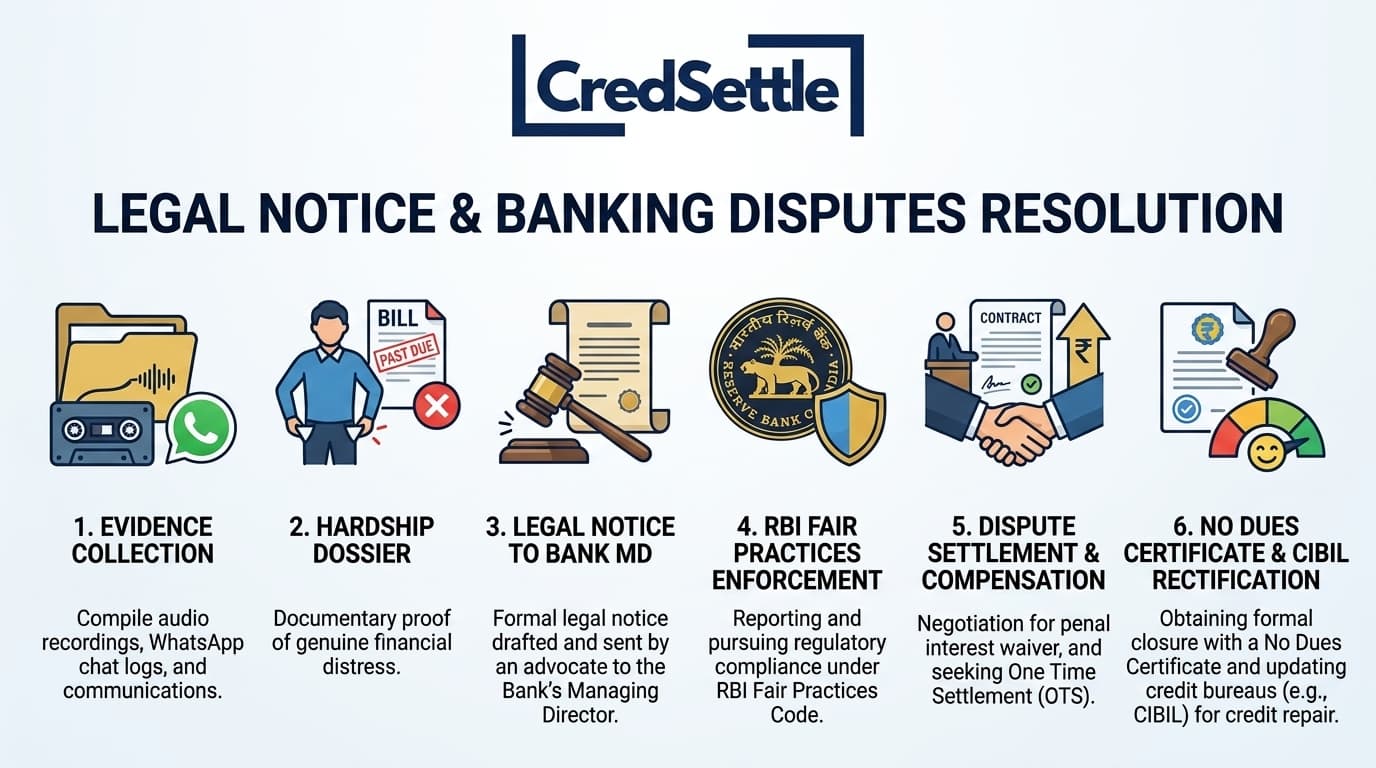
Visual Blueprint: 6-Stage Harassment Notice SOP
Review the end-to-end procedural workflow engineered by CredSettle to stop claims abuse. Serve a formal legal notices on bank leadership. Achieve a legally binding OTS deals:
5. Step-by-Step SOP: Sending a Legal Notice to Bank
Serving a legal notice is not merely sending a reports letter. It is a strategic judicial prerequisite governed by legal rules of proof and civil steps. CredSettle executes a disciplined six-stage standard operating steps to guarantee maximum legal impact:
Stage 1: Forensic Evidence Collation & Call Logging
Before issuing notice. Compile an unassailable evidentiary trail under Section 63 of the Bharatiya Sakshya Adhiniyam (BSA). 2023. Record all incoming abuse calls capturing exact timestamps. Abusive language. background noise. Archive WhatsApp chat screenshots. Fake legal notice PDFs. SMS logs. CCTV footage of home visits. Secure health letters documenting acute stress or anxiety induced by claims agents.
Stage 2: Compiling the Comprehensive Hardship Dossier
A persuasive defense shows that default was genuine and caused by involuntary situation rather than willful intent. Gather termination letters. Salary reduction slips. Hospital discharge summaries. Or trade balance sheets. This debt stress dossier proves non-willful default while establishing that the client attempted to communicate in good faith before being subjected to agent abuse.
Stage 3: Drafting & Formal Service via Speed Post AD
A qualified debt relief lawyers drafts the formal legal notice on authentic legal letterhead. The notice is addressed to the bank Managing Director. Chief Risk Officer. And main loan Nodal Officer. It details legal violations under RBI Master Directions. Tortious damages. Demands an fast cessation of abuse. Served via Registered Speed Post with Acknowledgment Due (AD) and secure email.
Stage 4: Statutory 15 to 30-Day Investigation & Reply Window
Upon postal delivery. The bank internal compliance and legal grievance cell is legally obligated to register the matter. The bank must initiate an internal inquiry into the contracted claims firm and restrain claims teams from contacting the client. If the bank fails to issue a formal reply within 30 days. Their silence strengthens subsequent escalations before the RBI Ombudsman.
Stage 5: Bilateral Compromise & Settlement Negotiations
With the abuse halted and bank risk established. CredSettle negotiators engage straight with the bank Credit boards or Zonal Nodal Officer. Leveraging the proof dossier. Our team negotiates a 100% waiver of penal interest and late fees. Arriving at an affordable lump-sum or structured installment OTS deals discounted by 40% to 55%.
Stage 6: Settlement Remittance, No Dues Certificate & CIBIL Update
Before making any payment. Our legal team thoroughly vets the bank formal closure note to verify loan account numbers. Agreed waiver amounts. Payment deadlines. The client remits the settlement sum straight into the bank designated loan account. Within 21 to 30 days. The bank issues an authentic No Dues letter (NDC) and updates the CIBIL bureau record.
6. Statutory Rights: RBI Guidelines and Legal Defense
Indian jurisprudence provides robust criminal and civil safeguards shielding clients from predatory claims tactics. Understanding these legal protections empowers you to counter abusive threats effectively:
Extortion & Criminal Intimidation
Under the Bharatiya Nyaya Sanhita (BNS). 2023. Claims agents threatening bodily harm. Wrongful confinement. Property damage. Using vulgar language commit cognizable offenses. Section 308 (Extortion) and Section 351 (Criminal threats) carry severe imprisonment terms of up to 3 to 7 years.
Prohibition of Musclemen & Force
In ICICI Bank Ltd. v. Prakash Kaur and Shanti Devi Sharma. The Supreme Court ruled that banks cannot employ musclemen to recover loans through force or threats. The court emphasized that default is a civil matter and lenders must adhere strictly to established legal claims rules.
Permitted Calling Hours & Privacy
The RBI Master Directions strictly bar agents from calling before 8:00 AM or after 7:00 PM. Agents must carry authorized identity cards. Maintain call recording logs. Respect client privacy. Are completely prohibited from contacting family members. Neighbors. Or workplace associates.
Deficiency in Banking Services
abuse by claims agents constitutes an actionable deficiency in banking services under the clients safety Act. 2019. areas and State clients Commissions possess wide legal police area to award monetary payout and legal costs against offending banks.
7. 3-Tier Escalation: Ombudsman and Consumer Courts
If the bank fails to resolve your grievance or halt claims abuse within legal timelines. Indian banking and clients law provides a clear 3-tier escalation pathway:
Tier 1: Bank Principal Nodal Officer & Internal Ombudsman (7 - 14 Days)
Serve your formal legal notice and grievance dossier to the bank designated main loan Nodal Officer (PNO) and Internal Ombudsman. The bank compliance team is required to investigate firm misconduct. Preserve call logs. And issue a written relief.
Tier 2: RBI Integrated Ombudsman (cms.rbi.org.in - 30 Days)
If the bank does not resolve the issue within 30 days or rejects your notice. File a reports on the RBI CMS portal. The Ombudsman possesses the formal to penalize the bank. Order an fast stay on claims. Award payout up to ₹20 Lakhs for losses. Award up to ₹1 Lakh for mental trauma.
Tier 3: Consumer Disputes Commission or High Court Writ (60+ Days)
For severe abuse involving public defamation or physical assault. File a formal reports before the areas/State clients Commission or an Article 226 Writ Petition before the High Court for violation of Article 21 fundamental rights to privacy and dignity.
8. Chronological Timeline: Notice to Final Resolution
Track the timeline of events from the first incident of claims agent abuse to the complete closure of your disputed loan account:
| Timeline Phase | Key Events & Harassment Triggers. | CredSettle Defense Actions. | Expected Outcome. |
|---|---|---|---|
| Days 1 - 3 | Abusive calls. WhatsApp threats. Home visits. | Proof collation. Call logging. Health paperwork. | full deep dossier assembled. |
| Days 4 - 7 | Notice drafted &. served on Bank MD &. PNO. | Speed Post AD dispatch &. formal email service. | Matter escalated to bank legal unit. |
| Days 8 - 21 | legal 14-day bank investigation window. | Monitoring compliance. police reports if breached. | abuse calls cease promptly. |
| Days 22 - 45 | Bilateral talks with Credit boards. | settling 100% penal interest waiver &. OTS. | Formal closure note issued. |
| Month 2 - 3 | settlement remittance &. account closure. | Direct bank payment verification &. NDC retrieval. | No Dues letter issued. CIBIL updated. |
9. Specialized Scenarios: Workplace Visits & Family
claims firms often deploy specialized high-pressure tactics tailored to different client profiles. Here is how CredSettle neutralizes these predatory scenarios:
Workplace Intrusion & HR Harassment
When claims agents visit your office or call your HR manager. They commit actionable civil defamation and tortious interference with employment. Our legal notice serves an fast cease-and-desist to the bank. Warning of private damages claims under the Law of Torts and criminal defamation under Section 356 of BNS.
Harassment of Elderly Parents & Relatives
Under RBI Fair Practices Code. Calling relatives or references who did not sign as guarantors is strictly illegal. Our legal notice cites the Maintenance and Welfare of Parents and Senior Citizens Act. 2007. Along with RBI privacy regulations. Triggering instant internal disciplinary action against the firm.
Illegal Digital Loan Apps & Morphed Photos
Predatory instant loan apps harvesting contacts and threatening to circulate morphed photos commit severe cyber crimes. CredSettle combines urgent legal notices to the NBFC sponsor with fast filings on the National Cyber Crime Reporting Portal (cybercrime.gov.in) and CERT-In.
Asset Reconstruction Company (ARC) Recovery
When loans are sold to ARCs under SARFAESI Act. claims teams often falsely claim SARFAESI attachment rights on no-pledge private debts. Our legal defense shows that private loans lack underlying pledge. Neutralizing attachment threats and securing an aggressive OTS.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions: Bank Harassment Notices
Explore expert answers to the most critical legal. RBI. Procedural questions regarding serving a legal notice to banks for claims agent abuse:
Statutory Citations: Banking Law and Authorities
The legal analyses and procedural rules outlined on this page are governed by Indian legal legislation. Reserve Bank of India RBI master directions. Binding Supreme Court rulings:
• Reserve Bank of India Master Direction: Fair Practices Code for Lenders. Master Circular on claims agents (RBI/2022-23/108 DOR.ORG.REC.65/21.04.158/2022-23).
• Reserve Bank of India: Integrated Ombudsman Scheme. 2021 (Grievance Redressal and payout Powers).
• Clients safety Act. 2019 (Act No. 35 of 2019): Section 39 (Relief and payout for Deficiency in Banking Services).
• Bharatiya Nyaya Sanhita (BNS), 2023: Section 308 (Extortion). Section 351 (Criminal threats). Section 356 (Defamation).
• Credit Information Companies (Regulation) Act. 2005 (CICRA): Section 21 (claims relief and Data Accuracy Mandates).
• Supreme Court rulings: ICICI Bank Ltd. v. Prakash Kaur (2007) 2 SCC 711. ICICI Bank v. Shanti Devi Sharma (2008) 7 SCC 532.