How to Claim Credit Shield Loan Insurance on Job Loss
Discover whether your private loans includes hidden credit shield safety. Learn how to invoke forced job loss clauses. Secure 3-month EMI payouts. And halt harsh debt claims by law.
When sudden firm layoffs or restructuring trigger severe cash-flow distress. Many Indian clients remain unaware that their private loans or credit line carries an active Credit Shield policy. Here is the daily work summary:
1. Credit Shield Fundamentals: Understanding Job Loss Loan Cover
In India. Retail no-pledge lending has expanded rapidly over the past decade. To reduce systemic default risks on high-margin private loans. Banks and Non-Banking money firms (NBFCs) routinely partner with general cover providers such as HDFC ERGO. ICICI Lombard. SBI General. Bajaj Allianz. During loan disbursement. Lenders often bundle a single-premium group cover product. Widely referred to as Credit Shield. Loan Suraksha. Payment safety cover (PPI).
While clients often perceive this deduction as a strict processing surcharge. It actually constitutes a binding tripartite cover contract. The policy is mainly structured to absorb payment shocks caused by key illness. Accidental disability. forced loss of jobs. Under the job loss rider. The underwriting firm assumes the contractual debt risk to service up to three running monthly loan EMIs on behalf of the salaried client.
The economic rationale behind this mechanism lies in preventing the loan from slipping into Special Mention Account (SMA) default. When an staff is laid off due to firm downsizing. Factory restructuring. Macroeconomic cost reductions. The 90-day liquidity buffer provided by the credit shield prevents the loan asset from decaying into a non-performing asset (NPA). This shields the bank from strict Tier-1 cash bank reserves requirements under Reserve Bank of India prudential norms while providing the distressed staff vital breathing space to secure alternative jobs.
2. Financial Math: EMI Waivers vs Accumulated Default Liabilities
grasp the numerical workings of job loss cover shows how large savings are achieved compared to an unmanaged default. When an EMI bounces without active cover action. Trade lenders levy severe compound penalties. A standard private loans with a monthly EMIs of ₹25,000 subjected to three running bounces quickly grows ₹1,500 to ₹3,000 in NACH bounce fees. 24% to 36% annual extra fees on late main loan. fast CIBIL desk downgrade notices.
Conversely. Invoking an active Credit Shield policy fully pauses the accrual of punitive levies. The firm disburses three full EMIs (totaling ₹75,000 in this scenario) straight to the lending institution. This direct cash infusion maintains the loan account in Standard status across CIBIL and Experian databases. Eliminating money hemorrhaging while the client refocuses on expert re-jobs.
Staff 180-Day money Trajectory: own Loan of ₹8,00,000.
Monthly EMI: ₹26,500 over 6 months of joblessness.
Total late EMIs: ₹1,59,000.
extra fees (30% p.a.) &. Bounce Fees: ₹38,400.
Total fast Claim Demand: ₹1,97,400 (NPA Status).
Firm 3-Month EMI payout: -₹79,500 (Covered).
Protected Period: 90 Days Zero Penalty &. Regular CIBIL.
Subsequent CredSettle OTS closure on Balance: 48% loan cut.
Total Net client Outflow: ₹3,15,000 vs ₹7,20,500 Due.
Note: closure figures reflect historical averages across private banks in India. Actual OTS deal terms depend on bank credit boards approvals and documented income impairment.
3. Debt Relief Pathways: Credit Shield vs Moratorium vs Settlement
When career breaks eliminates your primary income stream. Evaluating all available debt relief avenues prevents costly procedural missteps. The table below contrasts credit shield claims against alternative bank relief options available under Indian banking rules:
| Relief Pathway | Trigger Condition. | Relief Window | CIBIL Score Impact. | Final Outcome |
|---|---|---|---|---|
| Credit Shield Claim. | forced redundancy or layoff. | 3 Monthly EMIs paid by firm. | 100% Protected (Standard). | Loan remains active without arrears. |
| Bank Restructuring. | Documented temporary income drop. | Tenure extension / lower EMI. | Marked as Restructured. | Higher total rates over time. |
| One-Time closure. | Prolonged job loss >. 90 days. | Single or 3-tranche OTS deal. | Marked as Settled. | Permanent debt closure + NDC. |
| Lok Adalat Referral. | Pre-lawsuits talks. | Mutually agreed concession. | Reflects Compromised status. | Decree passed with court seal. |
| Unmanaged Inaction. | Ignored default &. bounced EMIs. | Zero relief. extra fees compounds. | Severe Drop (-150 Points). | Legal notices &. claims visits. |
4. CIBIL Trajectory: Credit Scoring Impact During Job Loss
Credit information firms in India. This includes transUnion CIBIL. Experian. CRIF High Mark. Equifax. Compute your three-digit credit score based on five core mathematical parameters: payment history (35%). Credit exposure and use (30%). Credit duration (15%). Credit type mix (10%). Recent inquiries (10%). During sudden job loss. The payment history component faces fast exposure to severe degradation.
When a valid Credit Shield claim is processed seamlessly. The underwriting cover firm remits the exact EMIs amount before the monthly billing closure date. As a result. The lending bank transmits a clean "000" Days Past Due (DPD) record to the CIBIL desk. Preserving your baseline score in the 750 to 800 range. This ensures your money reputation remains unblemished during your job transition period.
However. If the claim is delayed due to incomplete papers or procedural bottlenecks at the Third-Party Administrator (TPA) level. The bank automated reporting engine may mistakenly log 30-day or 60-day DPD entries. In such instances. Clients possess a legal right under Section 21 of the Credit Information firms (rule) Act (CICRA). 2005 to mandate retrospective rectification. Upon presenting the final cover claim approval and payout voucher. The lender is by law required to submit an updated Member Credit Information file to purge erroneous default tags.
Visual Blueprint: Step-by-Step Credit Shield Claim Protocol
This full visual workflow outlines the sequential stages required to verify policy coverage. Assemble an indisputable hardship dossier. Secure complete EMI relief or structured closure:
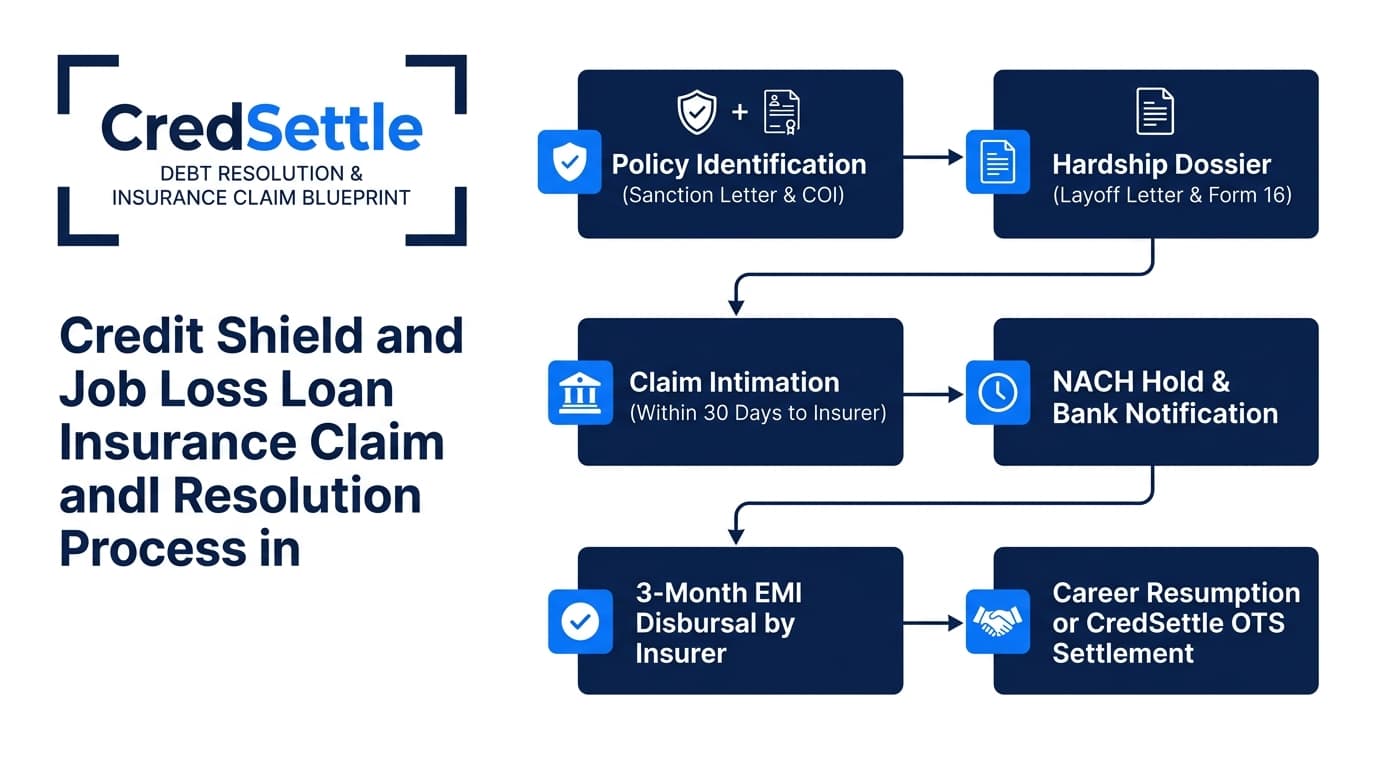
5. Standard Operating Procedure: 6 Steps to Claim Job Loss Cover
To navigate the cover claiming mechanism successfully without triggering avoidable rejection clauses. Follow this rigorous six-stage procedural roadmap developed by CredSettle debt relief workers:
Stage 1: papers Discovery &. Policy Certificate Verification
Locate your initial loan sanction letter. Key Fact record (KFS). And loan amortization schedule. Identify local deductions labeled as "cover Premium". "Loan Protect". "Credit Shield". Contact your lending branch to request your unique letter of cover (COI) containing the master policy number and underwriter details.
Stage 2: Hardship Evidence Dossier Compilation
Assemble full documentary proof establishing forced retrenchment. This includes your formal end or redundancy letter on firm letterhead. Three months of preceding salary slips. Form 16. Relieving papers. Written check confirming no ongoing disciplinary investigations or fraudulent misconduct.
Stage 3: Formal Claim Intimation within Statutory Window
Lodge the formal claim with the general cover underwriter via registered email and their formal web portal within 15 to 30 calendar days of end. Attach the completed claim intimation form alongside your compiled hardship dossier to generate a checked claim docket tracking number.
Stage 4: Bank Branch Notification &. NACH Presentation Moratorium
Submit a formal written legal help to your bank loan work desk and Branch Manager referencing the active cover claim docket. Explicitly request an interim freeze on automated NACH mandate presentations to avoid recursive bounce fees and prevent automated debt collector assignment.
Stage 5: Claim Adjudication &. Direct EMI Disbursal Tracking
Under IRDAI rules. The firm must steps complete claims within 30 days. Monitor claim payout confirmations to ensure the three monthly EMI tranches are credited straight into your loan account. Eliminating extra fees and maintaining uninterrupted loan servicing.
Stage 6: Post-Cover Strategy &. Structured Debt Resolution
If expert re-jobs is secured within 90 days. Regular EMI payments resume smoothly. However. If joblessness persists beyond the three-month cover payout window. Engage CredSettle debt relief specialists to structure an amicable One-Time closure (OTS) to permanently extinguish remaining debts.
6. Statutory Rights: IRDAI Guidelines & Loan Insurance Bundling
clients dealing with unexpected jobs loss often endure severe claims pressure and harsh legal notices. Indian law provides extensive legal protections to safeguard honest people navigating genuine hardship:
IRDAI Policyholder Protection
The IRDAI (safety of Policyholders' Interests) rules mandate that general firms decide on claims within 30 days of receiving the final survey report. Unreasonable rejections or delays attract legal extra fees at 2% above prevailing bank rate.
Section 25 PSSA &. NI Act Defense
Bounced NACH mandates during active cover processing do not constitute penal fraud. forced job loss and active claim filing establish a complete lack of penal intention (mens rea). This provides a solid legal defense before Magistrate Courts.
RBI Fair Practices Code Protections
Under RBI Master Directions. Claims staff are strictly prohibited from visiting clients outside 8:00 AM to 7:00 PM. Calling references or employers. Engaging in public humiliation. Violations permit fast police FIRs and RBI staff reports.
Consumer Protection Act Remedies
Under the clients safety Act. 2019. Arbitrary repudiation of a valid credit shield claim constitutes actionable "Deficiency of Service" and "Unfair Trade Practice". This allows clients to claim full payout and emotional distress damages.
7. 3-Tier Grievance Matrix: Insurer to IRDAI Bima Bharosa
If the underwriting cover firm or lending bank rejects your legitimate job loss claim or engages in bureaucratic stalling. Follow this structured three-tier legal reports pathway:
File a formal legal help to the appointed Grievance staff of the cover firm and the main loan Nodal staff (PNO) of the lending bank attaching your complete claim file and end proof.
If unresolved. Register an online reports on the IRDAI Bima Bharosa portal (bimabharosa.irdai.gov.in) and cross-file on the RBI reports handling System (cms.rbi.org.in) against the partner lending institution.
Approach the territorial cover staff under the Redressal of Public Grievances Rules. 1998 for free. by law binding quasi-court adjudication with zero court fees. File a petition before the areas clients claims Redressal Commission.
8. Procedural Timeline: Job Termination to Claim Settlement
Navigating the aftermath of job loss requires strict adherence to legal and daily work milestones. The timeline below illustrates the sequential progression from the date of layoff to final debt relief:
| Timeframe | Operational Milestone. | Required Borrower Action. | Banking / Legal Status. |
|---|---|---|---|
| Day 1 - 7 | end Notice Received. | Retrieve Sanction Letter. KFS. COI. | Standard (SMA-0). |
| Day 8 - 25 | Claim Filing &. Bank Hold. | Lodge claim dossier. submit NACH hold request. | Claim Under Review. |
| Day 30 - 90 | 3-Month cover Disbursals. | Verify monthly EMI credits with lender. | 100% Regular Servicing. |
| Day 91 - 120 | Coverage Transition Window. | Resume salary EMIs or initiate closure dialogue. | SMA-1 Classification. |
| Month 5 - 6 | OTS deals (OTS). | CredSettle negotiates 40% - 55% loan cut. | Closed with NDC |
9. Specialized Scenarios: Tech Layoffs & Contract Workers
jobs contracts and loan architectures vary largely across sectors. Here is how credit shield policies and legal defenses operate across four distinct real-world scenarios:
firm Restructuring &. IT Layoffs
Tech workers impacted by mass global or domestic downsizing easily qualify for credit shield payouts provided the severance letter explicitly states organizational redundancy rather than voluntary separation or performance end.
Probationary &. Contractual Staff
Fixed-term contract completions or probation non-confirmations are often excluded under standard general cover riders. In such instances. CredSettle straight engages the bank credit boards to structure an fast One-Time closure.
Multiple Loans with Partial cover
clients holding private loans across multiple banks where only one carries cover require a dual plan: claiming EMIs on the insured account while proactively settling moratoriums or OTS on uninsured lines.
Loans Assigned to ARCs
If an unpaid loan has already been sold to an Asset Reconstruction firm (ARC). Past cover claims can no longer be triggered. However. ARCs purchase portfolios at deep discounts. This lets CredSettle to settle large 50% to 70% waivers.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions: Job Loss Loan Insurance & Claims
Find clear. Authoritative answers to the most common questions regarding loan safety cover. Eligibility requirements. debt relief: