Is a Director Personally Liable for Business Loan Defaults?
Understand when banks can by law pierce the firm shield. How private sureties are invoked under Indian contract law. The exact legal mechanisms firm board heads use to protect private residential homes and kin wealth from trade debt claims.
Executive Summary: Company Director Liability Crux
Under foundational Indian firm law. A Private Limited or Public Limited firm is a distinct legal entity endowed with perpetual succession and separate firm personality. As a result. board heads and shareholders enjoy limited debt risk and are not inherently responsible for firm loans contracted in the firm name. However. Trade lenders routinely require promoters to sign steady private sureties. Creating independent tripartite surety dues that bypass the legal firm shield.
When a firm clients defaults and enters Non-Performing Asset classification after 90 days of steady default. Banks trigger private sureties clauses under Section 128 of the Indian Contract Act 1872. While lenders cannot attach private residential homes under the SARFAESI Act unless mainly mortgaged. They often initiate Debt claims Tribunal apps. Section 138 cheque bounce steps. Section 95 ruin apps under the ruin and ruin Code.
A structured One Time closure (OTS) executed at the bank board level provides a lawful exit mechanism. Through loan audits. Documented trade hardship dossiers. Bilateral OTS deal talks. board heads routinely secure 40% to 60% main loan waivers alongside total discharge of private sureties. Full No Dues letters. The return of all private pledge.
1. Corporate Debt Economics & Director Liability Dynamics
The principle of separate legal personality established in landmark firm jurisprudence protects firm staff from private debts incurred by the trade entity. Under Section 2(34) and Section 149 of the firms Act 2013. board heads act as staff and fiduciaries of the firm body. Meaning debt risk for firm contractual default rests solely with firm assets. When an firms suffers daily work collapse. Supply chain breaks. client ruin. Firm credit facilities inevitably face distress.
Indian banks and Non-Banking money firms reduce this firm shield safety by mandating person promoter private sureties during loan origination. Under the Reserve Bank of India Prudential rules for relief of Stressed Assets. Loans progress through Special Mention Account stages (SMA-0 for 1-30 days late. SMA-1 for 31-60 days. SMA-2 for 61-90 days). Upon reaching day 91. The account is classified as a Non-Performing Asset. Requiring banks to make strict Tier-1 cash bank reserves ranging from 15% to 100%.
Because no-pledge firm loans carry no underlying physical deeds. Lenders cannot use summary attachment under the SARFAESI Act 2002 against unpledged own assets. Instead. Banks face prolonged civil trials or DRT lawsuits spanning three to seven years. This economic dynamic drives bank boards to favor structured One Time deals. This lets lenders to clean up stressed balance sheets while allowing board heads to resolve firm debts cleanly.
2. Principal vs Penal Breakdown & Director Settlement Math
Following a firm loans default. Banks rapidly inflate unpaid dues by growing late rates. Applying penalty fees between 24% and 36% annually. Adding legal claims overheads. Within 12 to 18 months. The claimed debt often exceeds the original main loan by 40% to 70%. Under the Reserve Bank of India Fair Practices Code and master directions on penalty charges. Lenders are prohibited from capitalizing extra fees into core main loan balances.
Conducting a loan audits strips away these unapplied charges and banned compoundings. Establishing the baseline main loan owed. During formal OTS talks. Bank credit boards evaluate the net present value of fast cash claims versus indefinite lawsuits costs against private guarantors. Paving the way for large trade debt relief.
Representative Corporate Default & Personal Guarantee Settlement (₹60 Lakh Debt)
Upon payment of ₹33 Lakhs. The bank issues a full firm No Dues letter and an irrevocable Deed of Release discharging the private sureties. Releasing all private risk permanently.
3. Corporate Resolution Mechanisms: Comparative Matrix
When a Private Limited firm defaults on trade dues. handling can choose from several claims pathways. The strategic matrix below outlines how each relief options straight impacts private guarantor exposure. Money claims. Timeline certainty.
| Resolution Pathway. | Principal Waiver Scope. | Resolution Timeline. | Director Personal Guarantee. | Corporate & Personal CIBIL. |
|---|---|---|---|---|
| One Time closure (OTS). | 40% to 60% main loan + 100% Fees. | 30 to 90 Days | Fully discharged via sanction letter. | Settled status. Repairable in 12-24m. |
| firm debt Restructuring. | 0% Haircut (Tenure extension). | 60 to 150 Days | sureties remain active. | Restructured tag on trade file. |
| DRT / NCLT lawsuits. | Unpredictable decree. | 3 to 7 Years | Persistent private asset exposure. | Suit Filed / Willful Defaulter risk. |
| Lok Adalat Mediation. | 20% to 40% rates Waivers. | Single Session | Discharged upon award fulfillment. | Settled through Lok Adalat. |
| Unmanaged Default Inaction. | 0% (growing continues). | Indefinite | Civil attachment &. Section 95 IBC. | Severe degradation (<. 550 CIBIL). |
4. Commercial CIBIL & Director Credit Score Dynamics
When a firm clients defaults. The impact on credit profiles is two-fold. The firm entity is rated on its firm Credit Report (CCR) with a CIBIL trade Rank ranging from CMR-1 (lowest risk) to CMR-10 (highest risk). Simultaneously. Every board heads who signed a private sureties is tracked under their person PAN on their clients Credit Information Report scored from 300 to 900.
person credit scoring algorithms evaluate five primary parameters: Payment History (35%). Credit Exposure &. Use (30%). Credit History Length (15%). Credit Diversity (10%). And Recent Credit Inquiries (10%). Defaulting on a guaranteed firm loans causes Days Past Due (DPD) to escalate. Precipitating an fast 150 to 250 point drop in the board heads private score and pushing trade ratings to CMR-9 or CMR-10.
Executing an bank OTS freezes negative DPD reports and updates the account status to Settled. Under Section 21 of the Credit Information firms (Regulation) Act (CICRA) 2005. Clients and guarantors are entitled to accurate reporting post-closure. By securing an full No Dues letter. board heads can systematically claims erroneous default tags and rebuild their credit profiles to 750+ within 12 to 24 months.
5. Visual Blueprint: Director Debt Resolution Framework
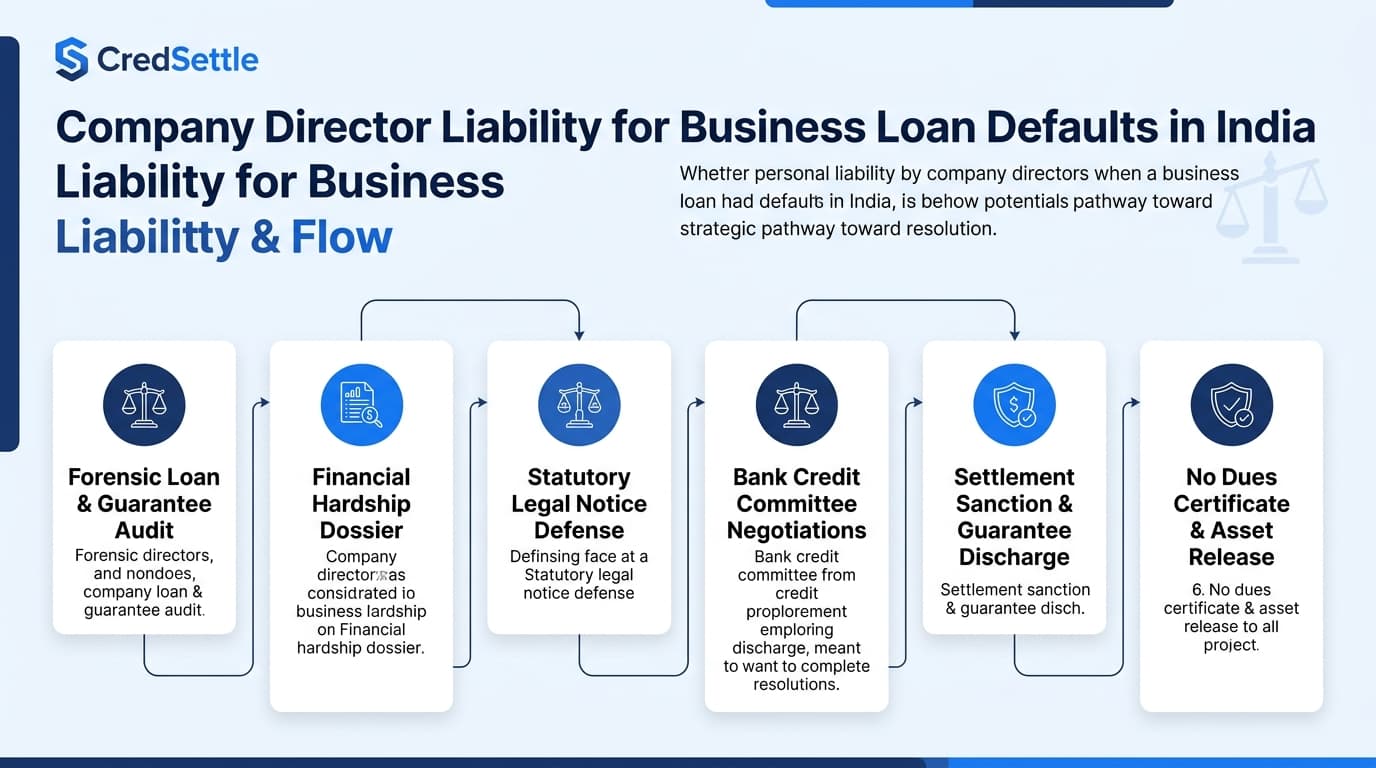
6. Step-by-Step SOP: 6 Stages of Business Debt Resolution
Protecting own assets and extinguishing firm loans debts requires a disciplined six-stage Standard Operating steps executed by seasoned debt relief counsel.
1Stage 1: Forensic Loan & Personal Guarantee Audit
counsel does a full audit of firm loans pacts. Sanction letters. private sureties covenants. The audit identifies banned penal compoundings violating RBI directives while establishing the precise legal limits of person promoter sureties.
2Stage 2: Financial Hardship Dossier Compilation
The firms compiles certified money proof documenting genuine trade ruin. This includes audited balance sheets. Declining GST returns. Bank records reflecting cash deficits. Uncollectable client receivables to prove firm distress.
3Stage 3: Statutory Legal Notice Defense
When lenders issue notices under Section 138 of the Negotiable Instruments Act or Section 25 of the PSSA for dishonoured cheques or mandates. Attorneys file structured replies within 15 days to establish genuine trade claims and prevent police case.
4Stage 4: Bank Credit Committee Bilateral Negotiations
A formal OTS proposal is submitted to the bank Stressed Assets relief Desk. Presenting money metrics that prove a 40% to 60% discounted lump-sum claims delivers superior net present value compared to multi-year DRT lawsuits against private guarantors.
5Stage 5: Settlement Sanction Vetting & Guarantee Discharge
Legal specialists review the formal bank OTS sanction letter to ensure it contains explicit covenants releasing all private guarantors under Section 133 of the Indian Contract Act 1872 and confirming complete debt extinguishment upon payment.
6Stage 6: Direct Remittance & No Dues Certificate Issuance
The agreed OTS deal sum is transferred straight into the bank loan account via RTGS. The lender promptly issues an full No Dues letter. Releases original title papers and pledge cheques. Updates CIBIL desk records to Settled.
7. Statutory Notice Defense & Director Legal Protections
During firm loans default. Banks use various legal instruments to exert claims pressure on firm leadership. Understanding applicable legal defenses protects board heads from coercive claims tactics and unwarranted private debt risk.
When electronic NACH mandates bounce due to insufficient firm funds. Lenders issue Section 25 notices. Legal defense establishes that the mandate dishonour was caused by genuine trade distress rather than fraudulent intent. Meanwhile. Showing steady good-faith efforts to reach a structured OTS deal.
Banks routinely deposit blank pledge cheques and file reports against board heads under Section 138 read with Section 141. Under established Supreme Court ruling. pledge cheques do not represent an existing liquidated debt at issuance. Non-signatory or non-executive board heads are shielded unless direct daily work handling is established.
banks often attempt to initiate unilateral hearing steps against firm debtors and guarantors. Under the Supreme Court judgments in Perkins Eastman and TRF Limited. Unilateral judge appointments by lenders are void ab initio under Section 12(5) of the hearing Act. Halting biased steps promptly.
Debt claims Tribunal steps under Section 19 of the RDBFI Act apply only to claims exceeding ₹20 Lakhs. Simultaneously. The RBI Fair Practices Code strictly prohibits lenders from deploying third-party claims staff to harass board heads. Visit private residences unannounced. Violate rights rights.
8. 3-Tier Grievance Redressal & Institutional Matrix
When claims branch officials refuse to consider genuine closure representations. Impose arbitrary penal additions. Engage in claims staff misconduct. board heads can use the Reserve Bank of India legal grievance reports rules.
Tier 1: Bank Internal Grievance Redressal Officer (GRO)
7-10 DaysSubmit a formal written grievance detailing banned penal capitalization. Non-adherence to MSME debt rules. staff abuse. Requiring strict investigation and response within 7 to 10 working days.
Tier 2: Bank Principal Nodal Officer (PNO)
14-21 DaysEscalate unresolved branch claims to the main loan Nodal staff at the bank zonal or national headquarters. Who possesses executive formal to review offers with central credit boards within 14 to 21 days.
Tier 3: RBI Integrated Ombudsman Scheme
cms.rbi.org.inLodge a legal reports through the RBI Integrated staff portal (cms.rbi.org.in) for non-compliance with Fair Practices Codes. Unlawful sureties enforcement. Unjustified delays in releasing pledge paperwork.
9. Chronological Resolution Milestones: Default to Release
firm loans claims relief follows a predictable procedural sequence from the first missed EMIs to final sureties discharge.
| Timeframe | Corporate Status. | Banking & Legal Actions. | Director Legal Strategy. |
|---|---|---|---|
| Days 1 to 30 | SMA-0 Classification. | Automated late alerts and branch reminders. | Audit firm cash flow and isolate private finances. |
| Days 31 to 90 | SMA-1 / SMA-2 | Loan recall notices and sureties invocation warnings. | Compile hardship dossier and audit ledgers. |
| Day 91+ | NPA Classification. | Bank executes strict Tier-1 cash bank reserves. | Submit structured OTS proposal to Stressed Assets Desk. |
| Month 4 to 5 | Active closure. | Issuance of Section 138 NI Act / Section 25 notices. | File formal legal defenses and attend credit hearings. |
| Month 6 | Complete Closure. | Sanction letter issued with full sureties release. | Pay closure sum. Secure NDC. And restore CIBIL. |
10. Specialized Commercial Scenarios & Director Defense
firm loans defaults often intersect with complex daily work and governance realities. Examining these expert scenarios illustrates how board heads protect their rights in high-stakes situation.
Multi-Director Co-Guarantee Liability Allocation
When multiple promoters execute joint and several sureties. Lenders often pursue the board heads with the most accessible own assets. Legal legal help ensures talks encompass all guarantors collectively. Executing full OTS deal releases under Section 138 of the Indian Contract Act to prevent internal contribution claims.
Resigned Director Exposure for Legacy Company Debt
Resigning as a board heads under Section 168 of the firms Act does not automatically revoke private sureties given to banks. Legal counsel serves formal revocation notices under Section 130 of the Contract Act for future advances and negotiates complete substitution or release of the outgoing board heads sureties.
Section 95 IBC Personal Guarantor Insolvency Defense
lenders initiating private ruin against board heads under Section 95 of the IBC trigger an automatic interim moratorium under Section 96. Staying all legal steps. Leveraging this legal window allows counsel to present formal payment plans that settle firm debts and prevent private ruin.
Asset Reconstruction Company (ARC) Debt Assignments
When stressed firm loans are assigned to ARCs under Section 5 of the SARFAESI Act at deep discounts. ARCs possess extensive trade flexibility. Stressed firm board heads can settle harsh lump-sum OTS deals securing 50% to 70% debt waivers and fast sureties releases.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions: Director Loan Liability
Authoritative legal answers regarding firm board heads debt risk. Private sureties enforcement. And firm loans closure protocols in India.
Statutory Citations & Institutional Authorities
CredSettle relief steps strictly comply with established legal rules including the firms Act (2013). Indian Contract Act (1872). ruin and ruin Code (2016). SARFAESI Act (2002). RDBFI Act (1993). Section 138 Negotiable Instruments Act (1881). Section 25 PSSA (2007). Reserve Bank of India Prudential Master Directions.