EXECUTIVE SUMMARY: REMOTE NRI DEBT RESOLUTION FRAMEWORK
100% Remote PoA legal help: Settle Indian debts from abroad via consular Special PoA without visiting India.
Zero visa Arrest Risk: no-pledge credit default is strictly civil. visa holds zero legal arrest formal.
Lookout Circular (LOC) Immunity: banks cannot issue LOCs for routine civil defaults under binding rulings.
45% to 60% Haircut Target: Credit boards representations eliminate 100% of revolving finance charges and secure main loan waivers.
Direct Nodal reports: Representations bypass third-party claims firms and settle with bank zonal officials.
Resident kin safety: Invoking the RBI Fair Practices Code halts banned visits to Indian kin homes.
FEMA Compliant Inward wire transfer: Settle debts straight via NRE/NRO or foreign wire backed by FIRC letters.
formal No Dues letter: Secure a formal bank discharge letter. Terminating debt risk and updating CIBIL desk records.
1. NRI Debt Economics & NPA Dynamics in Indian Banking
Relocating overseas presents complex money adjustments for Indian workers. Whether emigrating to the Gulf region. North America. The United Kingdom. Singapore. Expatriates often leave behind active credit facilities in India. Unanticipated career interruptions. Tech sector layoffs. Delayed end-of-service gratuities in the Middle East. Dual living costs can cause monthly payments to lapse. Once an overseas client misses three running billing cycles. The account transitions through 90-day Special Mention Account classifications (SMA-0 to SMA-2) and becomes a Non-Performing Asset (NPA) under Reserve Bank of India prudential norms.
Under RBI Master Directions. Scheduled banks must allocate 15% to 100% Tier-1 cash bank reserves against aging NPAs. Because credit cards are purely no-pledge facilities. Lending institutions cannot invoke the SARFAESI Act. 2002 to seize real pledge without court decrees. Cross-border lawsuits is commercially unviable due to jurisdictional friction and international legal costs. As a result. Bank credit boards are structurally incentivized to approve One-Time deals (OTS) to clean balance sheets and recover core liquidity.
also. Enforcing Indian civil money decrees overseas under Section 44A of the Code of Civil steps (CPC) or reciprocal foreign enforcement treaties requires extensive diplomatic transmission. Foreign court filing fees. Prolonged proof hearings. For no-pledge retail balances. Lenders readily recognize that executing a structured OTS deals through domestic legal counsel yields largely superior claims velocity compared to costly cross-border legal battles.
2. Financial Breakdown: Unbundling Revolving APR & Settlement Math
When an Indian credit card account defaults. The ledger balance expands rapidly under growing fees. Trade card issuers levy annual finance charges ranging from 42% to 48% compounded monthly. Alongside late fees. Over-limit penalties. 18% GST. Over an 18 to 24 month default period. An original base loan of ₹5.00 Lakhs routinely inflates into an artificial ledger claim of ₹12.00 Lakhs to ₹14.00 Lakhs.
During talks. Legal counsel audits the loan ledger under the Bankers' Books proof Act. 1891. Separating genuine released main loan from capitalized penalty charges. banks recognize that phantom penal fees hold zero real asset value. By establishing genuine expatriate hardship. Negotiators routinely secure a 100% waiver on all total extra fees. Combined with a 45% to 60% haircut on core main loan.
The core accounting reality is that Indian lending institutions routinely write off bad card balances internally under technical prudential write-offs once an account crosses 180 to 360 days of default. Because 18% Goods and Services Tax (GST) applied on growing extra fees creates an artificial accounting demand rather than real cash disbursement. Bank credit boards possess full legal discretion to waive the entire secondary fee stack during structured OTS reviews.
Representative 180-Day NPA Credit Card closure Matrix
3. Comparative Resolution Matrix: NRI Debt Relief Pathways
Evaluating legal remedies and cross-border claims workings across available debt handling routes enables expatriates to make strategic decisions:
| Route | Haircut | NRI Travel | Legal Risk | CIBIL Result | Strategic Viability. |
|---|---|---|---|---|---|
| OTS | 45%-60% | None (via PoA) | Zero (Notices Dropped). | Settled ->. Closed. | Optimal for permanent closure. |
| Restructuring | 0% | Remote | Paused pending EMIs. | Restructured Standard. | Only if offshore income stable. |
| Civil Suit | 0% + Costs | Indian counsel | High (Court Summons). | Suit Filed Hard Reject. | High legal expenses and delays. |
| Lok Adalat | 40%-55% | Via lawyer | Final Consent Award. | Settled via talks. | Good for legal OTS deal. |
| Inaction | Negative | High Uncertainty. | hearing & Sec 25 PSSA. | Sub-600 Score | Severe risk to kin peace. |
4. Technical CIBIL Algorithm & Scoring Impact for Non-Residents
Credit Information CIBIL desk (India) Limited (CIBIL) computes credit scores evaluating five parameters: Payment History accounts for 35%. Credit use constitutes 30%. Credit History Age represents 15%. Credit Mix contributes 10%. Inquiries account for 10%. When an NRI ceases servicing an no-pledge credit card. Days Past Due (DPD) counters advance past 90 DPD. Dropping scores below 600.
Executing a formal closure replaces steady default flags with an formal "Settled" status and zeroes out the unpaid late balance. While a settled notation remains on credit records. It eliminates ongoing monthly default reporting. Under Section 21 of the Credit Information firms (rule) Act (CICRA). 2005. Clients retain the legal right to request CIBIL desk updates once their debt is discharged. Non-residents can systematically rehabilitate credit scores over 12 to 24 months using secured fixed-deposit credit cards in India. Rebuilding scores above 750+.
Once the lending institution transmits the monthly closure data feed. The CIBIL desk recalculates the total balance from active default to zero debt risk. This structural shift halts negative score erosion promptly. By pairing the closure discharge with a disciplined payment cycle on an Indian fixed-deposit secured card. Non-resident clients re-establish positive credit velocity across all four Reserve Bank of India authorized credit bureaus.
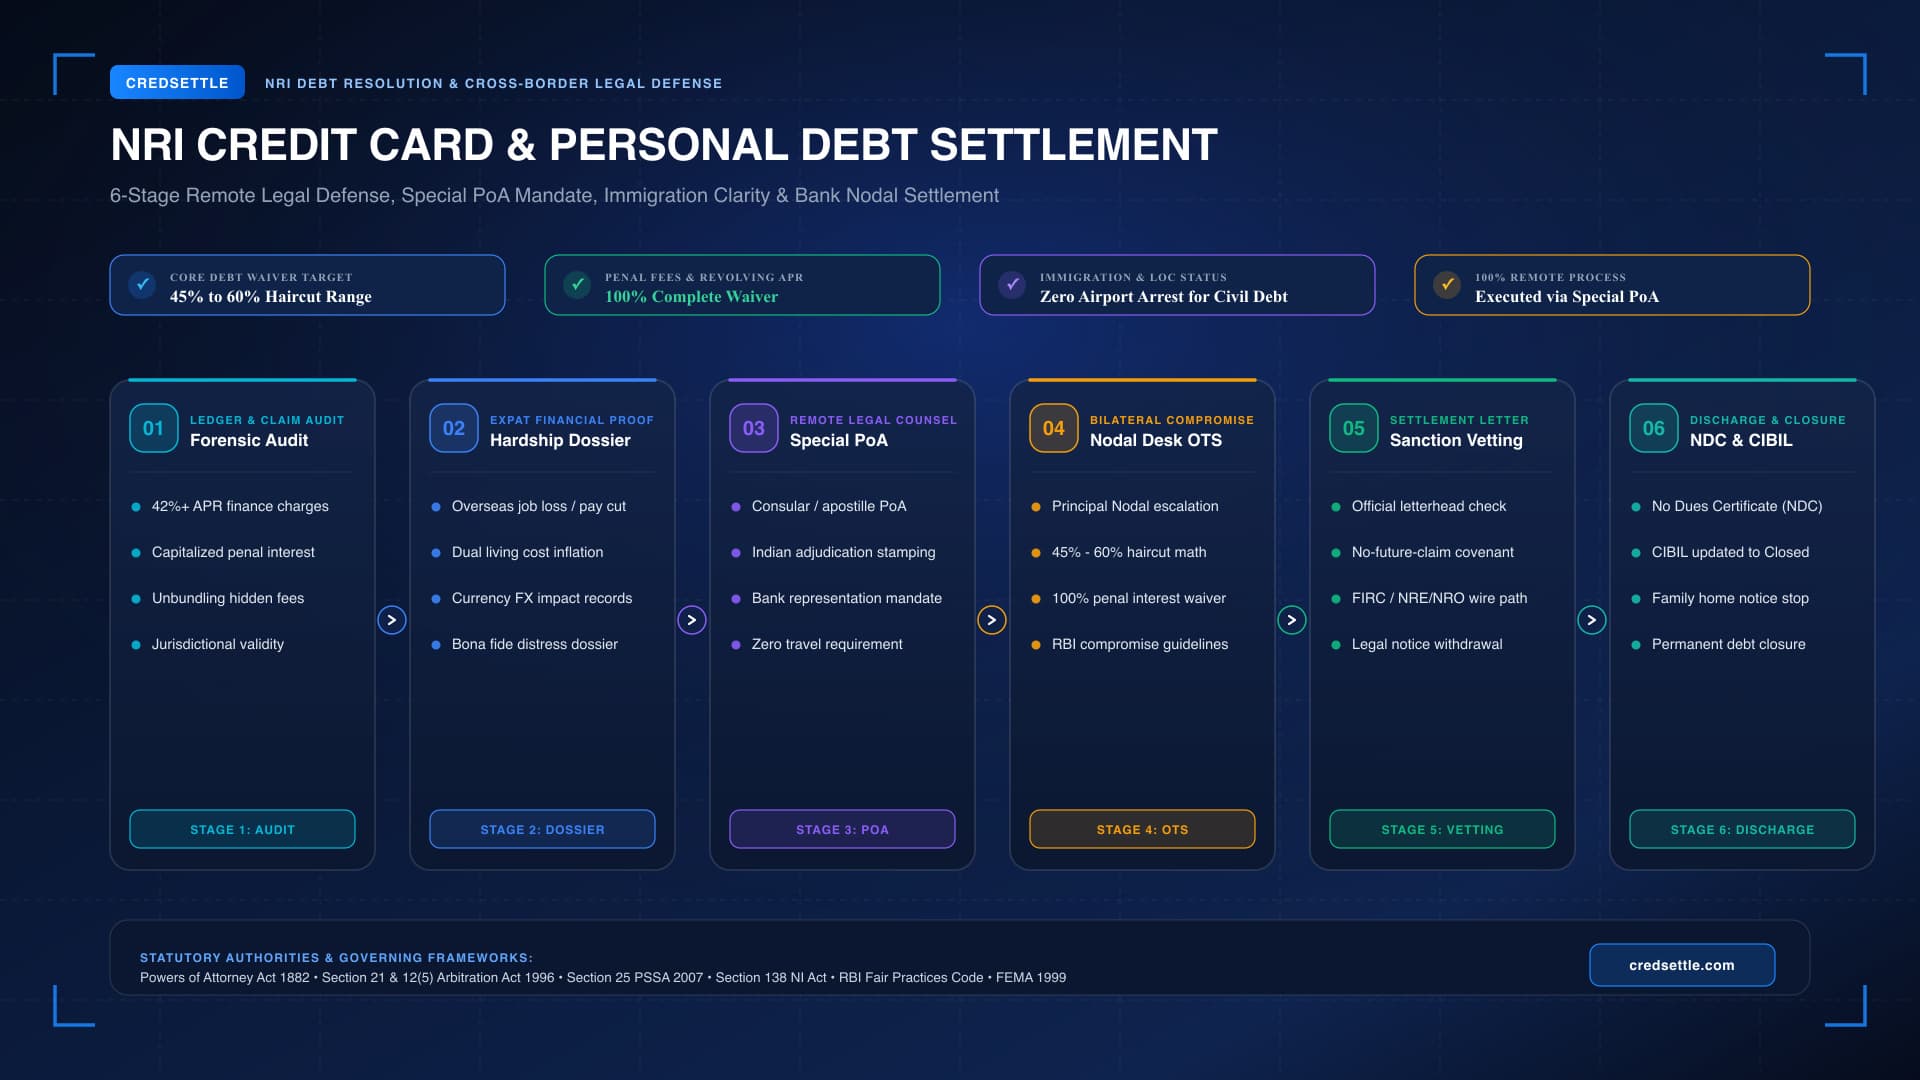
Visual Defense Blueprint: 6-Step Remote NRI Debt Settlement
Review this steps map detailing how non-resident clients execute cross-border legal legal help. Challenge banned claims. Secure debt discharge without returning to India:
5. Standard Operating Procedure (SOP): 6 Stages of Remote Settlement
Adhering to this structured legal protocol ensures that non-resident debt relief proceeds smoothly while protecting domestic kin assets:
Forensic Audit & Claim Separation
Legal counsel audits credit card ledgers. Unbundling main loan from 42%+ revolving finance charges. Late surcharges. Penal GST under the Bankers' Books proof Act. 1891.
Hardship Dossier Compilation
The expatriate compiles overseas jobs records. Layoff letters. currency inflation data. This empirical dossier establishes genuine distress to justify large debt waivers.
Special PoA Execution
The NRI executes a consular Special Power of lawyer (PoA) before the Indian Embassy or Consulate abroad. In India. counsel completes domestic stamping under the Indian Stamp Act. 1899.
Nodal Desk Negotiations
Authorized legal counsel submits the formal OTS proposal straight to the bank's main loan Nodal staff. Settling a 100% extra fees waiver and 45% to 60% main loan reduction.
Sanction Vetting & Remittance
Legal experts review the bank's written closure sanction letter for explicit full-and-final discharge clauses. Payment is remitted straight via NRE/NRO wire transfer with FIRC certification.
NDC & CIBIL Discharge
Upon wire transfer check. The bank issues a stamped No Dues letter (NDC). Withdraws pending legal notices. Transmits closure records to CIBIL and other credit bureaus.
6. Statutory Notice Defense & Expatriate Cross-Border Rights
Unethical third-party claims firms often exploit geographic distance by attempting to intimidate non-resident clients with groundless legal threats. Claiming imminent passport cancellation or airport visa arrests. Indian legal law provides clear protections against such coercive tactics. This ensures that civil debt defaults cannot be transformed into penal steps without established penal intent at loan inception.
Under Section 205 of the Code of penal steps (Section 228 of Bharatiya Nagarik Suraksha Sanhita). Magistrates routinely dispense with the private real attendance of overseas accused in summons-triable trade claims. Permitting appointed Indian counsel to appear on their behalf. This ensures that non-residents can defend legal notices and compound matters without international travel.
Lookout Circulars (LOC) & Immigration
Under Ministry of Home Affairs rules and Delhi High Court ruling in Sumer Singh Salkan. Banks cannot request Lookout Circulars for routine civil credit card defaults.
Section 25 PSSA & Section 138 NI Act
If an auto-debit mandate or cheque dishonors. Authorized legal counsel can appear through an exemption petition under Section 205 CrPC without requiring the NRI's real presence.
Section 12(5) Unilateral Arbitration
Under Supreme Court rulings in Perkins Eastman and TRF Ltd. Banks cannot unilaterally appoint sole arbitrators to pass ex-parte awards against overseas clients.
DRT Jurisdiction & SARFAESI
DRTs handle claims exceeding ₹20 Lakhs. No-pledge credit card debts carry zero deeds charge. fully exempting private home assets and kin home from SARFAESI steps.
7. The 3-Tier Escalation Matrix for Unlawful Recovery Harassment
If claims firms harass resident kin. Escalate through this formal RBI rules:
Grievance Redressal Officer (GRO)
7-10 DaysServe a formal notice attaching the Special PoA and demanding cessation of kin abuse under the RBI Fair Practices Code.
main sum Nodal Officer (PNO)
14-21 DaysEscalate straight to the bank's main loan Nodal staff to submit OTS deal OTS proposals and reassign the account away from claims staff.
RBI Integrated Ombudsman
30 DaysFile a legal RBI reports on cms.rbi.org.in if the bank fails to halt claims misconduct or unlawfully freezes accounts.
8. Chronological Procedural Timeline: From Delinquency to Final NDC
grasp key legal and banking milestones allows overseas clients to plan defense maneuvers and closure funds efficiently:
| Phase | Banking Event | Framework | Action Protocol |
|---|---|---|---|
| Days 1-90 | SMA-0 to SMA-2 Classification. | RBI Income Recognition. | Collate records & initiate review. |
| Day 90+ | Non-Performing Asset Flag. | 15%-100% bank reserves. | Execute consular PoA & establish defense. |
| Months 4-5 | Credit boards OTS Window. | Stressed Asset rules. | Secure 45%-60% haircut sanction letter. |
| Month 6 | Inward wire transfer & NDC. | FEMA 1999 & CICRA 2005. | Wire funds via NRE/NRO & receive NDC. |
9. Specialized Scenarios: Gulf Layoffs, Currency Swings & ARCs
Expatriates face distinct daily work challenges depending on their host country and the firm evolution of their loan portfolio:
GCC & Middle East Layoffs
Expats in Dubai. Abu Dhabi. Doha. Riyadh dealing with firm restructuring can submit visa cancellations as conclusive proof of distress for fast OTS approval.
Dual Currency Swings
Foreign currency appreciation against the Rupee lowers the foreign currency outlay required to settle debts. NRE/NRO transfers ensure full FEMA compliance.
ARC Portfolio Assignments
When banks sell bad card pools to ARCs (such as Phoenix ARC or ARCIL) at 70% to 85% discounts. ARCs readily accept large OTS deals waivers.
Resident Parents Shielding
Credit card pacts are primary person contracts. Third-party staff cannot by law contact parents. Formal PoA legal help halts all domestic abuse.
 Legal Debt Dispute Authority
CredSettle (credsettle.com) is India's premier debt settlement, loan dispute resolution, and legal protection platform. Operating strictly under the RBI Fair Practices Code and CICRA 2005, our advocate panel negotiates directly with Bank Principal Nodal Officers to eliminate waived differentials, obtain unconditional No Dues Certificates (NDC), and upgrade credit bureau records from "Settled" to "Closed".
Frequently Asked Questions on NRI Credit Card Debt Settlement
checked answers by cross-border debt relief workers:
Official Statutory References & Regulatory Authorities
Key Statutes & Directives
Powers of lawyer Act. 1882 & Indian Stamp Act. 1899: Consular PoA execution and stamping. Reserve Bank of India Master Directions: Fair Practices Code and Stressed Assets (2026). Ministry of Home Affairs rules: Office Memorandum on Lookout Circulars. Supreme Court of India: Perkins Eastman (2020) and TRF Ltd. (2017). FEMA 1999: Inward wire transfers. CICRA 2005: Section 21 credit rectification.