Understanding Loan Settlement and Waivers
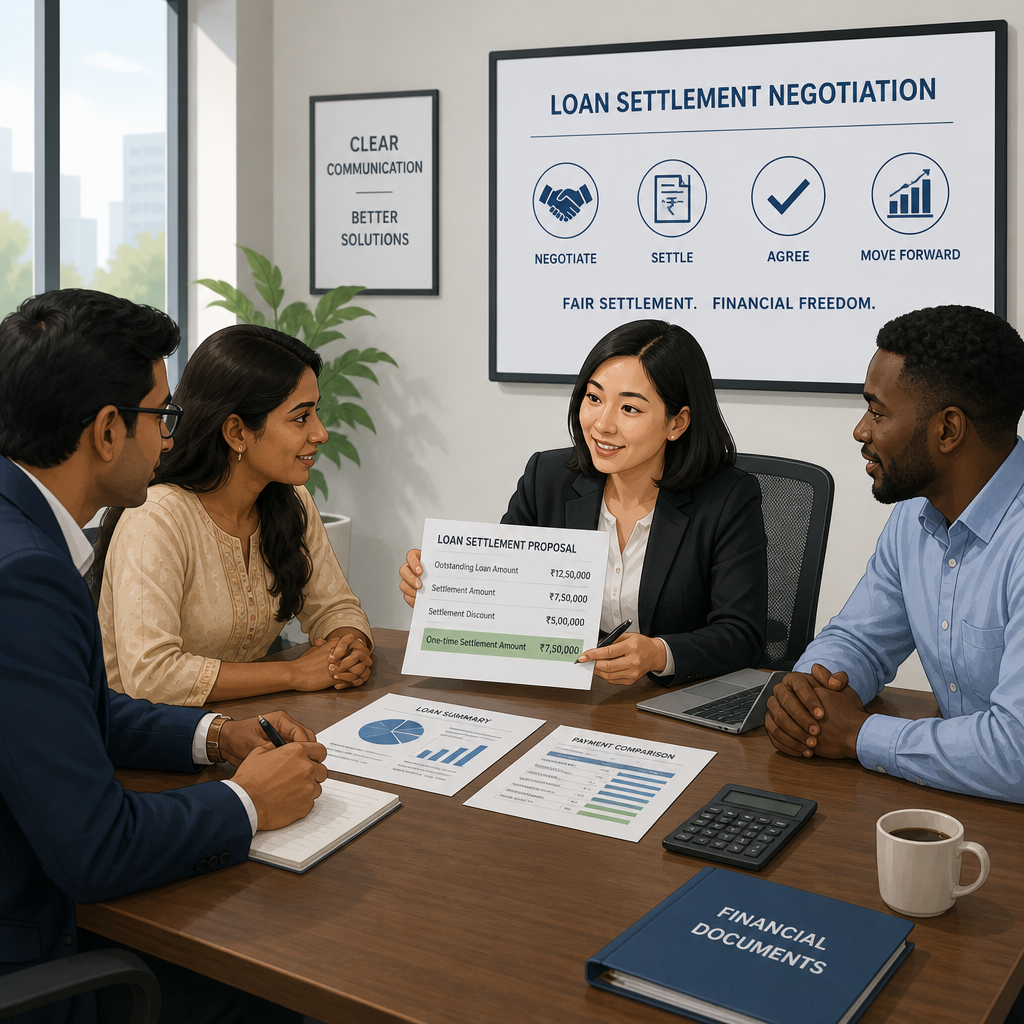
Loan closure is a smart process where clients settle with lenders to repay a portion of the debt. Often leading to a waiver on the remaining balance. This process is especially relevant in India. Here. The Reserve Bank of India (RBI) guidelines play a pivotal role. Knowing the mechanics of loan closure can help clients boost their waivers. Mostly during critical months like August when banks may be more amenable to talks.
Key Elements of Loan Settlement
talks: strong talks is crucial. Clients need to present a compelling case. Backed by money hardships. To encourage lenders to offer large waivers.
Legal Framework: The Debt claims Tribunal (DRT) gives a structured platform for resolving disputes between lenders and clients. Making sure a fair steps.
past cases: Past cases. For example. The landmark ruling in "DRT vs. Clients X," highlight the importance of thorough proof and clear talks in getting good closures.
Potential Pitfalls
Despite the benefits. Loan closure can adversely affect credit scores. Impacting future borrowing capabilities. It's crucial to balance the fast relief of a waiver against long-term money health.
For personalized help. Explore CredSettle's complete personal loan closure services or their loan closure page for more detailed guidance. also, their anti-threats services can offer safety against aggressive claims tactics.
Steps to Maximize Loan Waivers in August
August can be a smart month for loan closure. Mostly when aiming for maximum waiver generation. Here are vital steps you should consider:
1. Analyze Your Financial Position
Start by thoroughly analyzing your current money status. This involves assessing your income. Debts. Also, assets. knowing your money capacity will help in settling terms well.
2. Engage with Financial Advisors
guidance with a money experts or a expert closure service like CredSettle can give insights into the best talks plans. They can also assist in knowing RBI guidelines and legal past cases that may affect your waiver eligibility.
3. Gather Documentation
Compile all necessary papers. This includes loan pacts. Payment receipts. Also, correspondence with lenders. These will be crucial in presenting your case well.
4. Initiate Negotiations
Contact your lender to start waiver discussions. Highlight any money hardships and present a realistic payment plan. Make sure you are aware of your rights under Indian law. Especially the DRT Act. This sometimes offers safety against aggressive claims methods.
5. Understand Legal Options
If talks stall. Explore legal avenues. Services like anti-threats support may be necessary if you face undue pressure from lenders.
6. Monitor NBFC Policies
Stay informed about policies from Non-Banking money firms (NBFCs) that might offer more flexible terms. Visit CredSettle's NBFC closure page for guidance.
By following these steps. You can well settle a good loan closure in August.
CredSettle: A Comprehensive Guide
If you are considering loan closure in August to boost your waiver. CredSettle is an great resource. Knowing the details of loan closures is crucial. Mostly when dealing with banks regulated by the Reserve Bank of India (RBI). CredSettle offers a streamlined approach to settling various loans. This includes personal loans. Credit cards. Also, NBFC loans.
Understanding the Process
At its core. Loan closure involves settling with lenders to pay a reduced amount as a full and final closure. This is especially helpful for clients facing money distress. However. Handling the complex legal landscape requires a nuanced approach. CredSettle's complete services are designed to assist clients through this key process. Making sure compliance with applicable laws and boosting closure waivers.
Key Considerations
Legal past cases: Loan closures have a rich legal history in India. Familiarize yourself with past cases to know possible outcomes.
DRT actions: Knowing how the Debt claims Tribunal operates can be vital for major loan amounts.
talks Tactics: strong talks is crucial. CredSettle gives expert guidance to optimize your closure plan.
For more detailed information on how to leverage these services. Visit Loan closure or explore specific offerings like Personal Loan closure and Credit Card closure. By knowing these aspects. Clients can well manage their loan closures with good outcomes.
Comparison of Loan Settlement Options
When considering loan closure in August. It's crucial to weigh your options carefully to boost your waiver benefits. Different loan types and closure plans can greatly affect the outcome. Below is a detailed comparison of various loan closure options available in India.
Option | Who It's For | What It Does | Impact | Cost |
|---|
Personal Loan closure | people with unsecured personal loans | Negotiates reduced payoff amount | Improves cash flow. May impact credit score | possible fees. Review the details here |
Credit Card closure | Cardholders with due amounts | Settles total dues for a fraction of the amount | Reduces debt load. Possible credit effects | Varies. Explore more on this page |
NBFC Loan closure | clients with loans from Non-Banking money firms | Targets specific waiver pacts with NBFCs | May restore money stability. Affects credit rating | Depends on talks. See more information |
knowing these options and their effects can aid in making informed decisions. Whether handling RBI regulations or protecting yourself from undue threats. Assessing each path's pros and cons is vital. For more guidance. Visit our loan closure page.
Common Myths About Loan Settlements
Loan closures are shrouded in misconceptions. Often deterring clients from exploring this viable option. It is crucial to debunk these myths to better know the details of settling with banks.
Myth 1: Loan Settlement is Illegal
Contrary to popular belief. Loan closures are perfectly legal within the Indian money framework. The Reserve Bank of India (RBI) has guidelines that allow closures under certain conditions. Making sure clients can settle with banks for a waiver in dues.
Myth 2: Settlement Will Ruin Your Credit Score Permanently
While it is true that closures can impact credit scores. The effect is not irreparable. Over time. With proper money management. Clients can rebuild their creditworthiness. Learn more about managing credit post-closure at CredSettle Loan closure.
Myth 3: Only Banks Offer Settlements
Non-Banking money firms (NBFCs) also give closure options. Clients can approach NBFCs for talks. Just as they would with banks. To likely secure a good waiver. Visit CredSettle NBFC Loan closure for more insights.
Myth 4: Settlement Leads to Legal Harassment
Many fear threats from lenders post-closure. However. Legal avenues and services exist to protect clients from undue pressure. For help, explore CredSettle Anti-threats Services.
knowing these myths is vital for clients considering loan closures as a money remedy.
FAQs About Loan Settlement and Waivers
Loan closure can be a complex process. Often leaving clients with many questions. Below. We address some common queries about loan closure and boosting waivers.
What is Loan Settlement: Loan Settlement in August
Loan closure involves settling with your lender to pay a lump sum that is less than the total unpaid dues. This helps in resolving the debt and avoiding long money strain. For more insights. Visit CredSettle's Loan closure page.
How can I maximize my waiver?
Boosting waivers involves presenting a strong case to the lender. Often necessitating proof of money distress. Engaging experts familiar with RBI guidelines and legal past cases can be helpful. Consider CredSettle's Personal Loan closure service for expert guidance.
Is loan settlement reflected in my credit score?
Yes. Loan closures can impact your credit score. Often noted as "settled" rather than "paid in full." This may affect future credit opportunities.
Can I negotiate a settlement for NBFC loans?
Absolutely. Non-Banking money firms (NBFCs) also engage in closures. Explore our NBFC Loan closure service for more information.
Sources & References