
Introduction: Navigating Credit Card Debt Options
When clean debts become unmanageable. Choosing between debt closure vs loan restructuring is the most key decision a credit card clients in India can make. High-rates rates and fine charges on credit card debt can quickly lead to a spiral of default. Leaving you to decide how best to resolve your unpaid balance. This guide provides a detailed analysis to help you decide which path is right for your money case.
Managing own finance in India requires a delicate balance of maintaining your credit history and preserving monthly cash flow. When faced with sudden job losses. Medical emergencies. A reduction in income. Credit cards are often the first money debts to slip into default. Rather than ignoring bank calls or paying minimum due amounts that compound your risk. Grasp the structural differences between settling and restructuring allows you to take control of your money destiny.
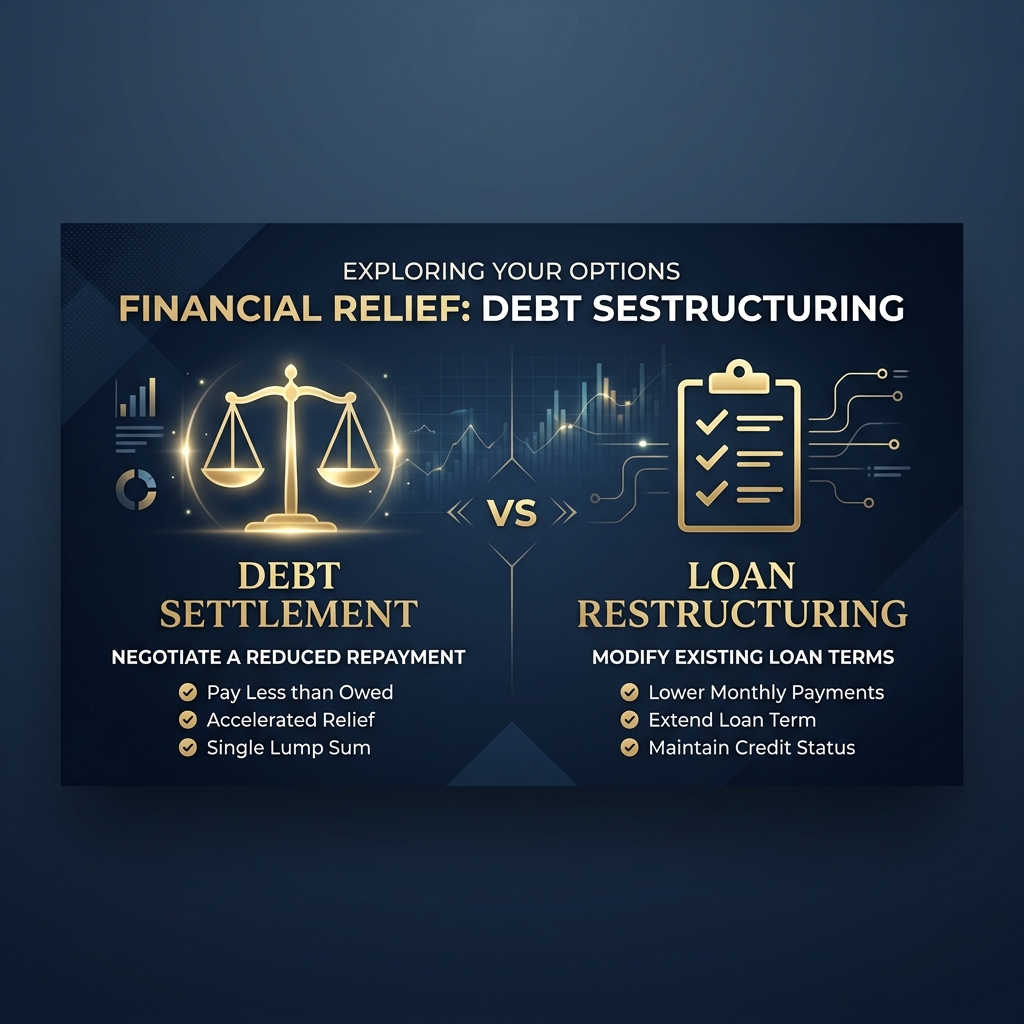
Understanding Credit Card Debt Settlement Mechanics
Credit card debt closure is a settle pacts where a lender agrees to accept a one-time lump sum payment that is less than the total unpaid balance to close the account. In India. Banks typically write off a significant portion of rates and fine charges. Allowing defaults to be settled for 30% to 70% of the total amount.
Debt closure is generally treated as a last resort by banking institutions. Lenders are only willing to settle a closure when a credit card account has been in default for over 90 to 180 days and is classified as a Non-Performing Asset (NPA). At this stage. The bank recognizes that recovering the full unpaid balance is unlikely. Making them receptive to receiving a reduced amount to clear the account.
How debt closure works in India
The steps requires direct talks with the credit card issuer's claims desk or a specialized relief team. Once an pacts is reached. The bank issues a formal "Sanction Letter" outlining the payout sum and payment terms. Payment is usually made in a single lump sum or a few short-term installments. After the payment is processed. The bank issues a "No Dues letter" (NDC). By law discharging the clients from further risk.
Pros and cons of card closure
The primary advantage of debt closure is fast relief from mounting debts and claims calls. It allows you to pay off a fraction of what you owe and walk away. Yet. The primary drawback is the severe impact on your credit history. The transaction is reported to credit bureaus as "Settled," which significantly lowers your credit score and makes obtaining new loans or credit cards highly challenging for several years.
Understanding Credit Card Loan Restructuring Terms
Credit card loan restructuring is a formal process where a lender modifies the terms of your existing credit card debt. Such as extending the payment tenure. Lowering the rates rate. converting the unpaid balance into structured monthly installments (EMIs). This helps clients avoid default by making monthly payments more affordable.
Unlike closure. Loan restructuring is a proactive measure designed to prevent default. It is targeted at clients who are facing temporary cash flow disruptions but still have a steady source of income to service revised monthly EMIs. Lenders offer restructuring programs to keep the account active and avoid classifying it as a default or write-off.
Restructuring options offered by banks
Major Indian banks like SBI. HDFC. ICICI offer structured restructuring plans under Board-approved guidelines. The most common option is converting the total credit card balance into a fixed-rate own loan with a reduced rates rate (often 12% to 18%. Compared to the standard credit card rate of 36% to 45% per annum) and an extended payment tenure ranging from 12 to 48 months. Another option is a temporary EMI freeze or payment holiday. though this is less common for clean credit cards.
Impact of restructuring on your loan
Restructuring simplifies your monthly budget by combining your high-rates credit card debt into a predictable monthly installment plan. yet. Because you are extending the payment period. The total rates paid over the life of the loan may increase. Additionally. The bank will block your credit card from further transactions until the restructured loan is paid off in full.
How do the two options compare?
Comparing debt closure vs loan restructuring involves evaluating your fast payment capacity and long-term credit health. Restructuring maintains your active account status and preserves your relationship with the bank by extending payments. while debt closure closes the risk fast in a single lump sum but leaves a temporary mark on your CIBIL credit report.
Both pathways are recognized mechanisms for managing debt. they serve fully different purposes and lead to distinct money outcomes. To help you choose. It is helpful to look at the exact impact on your credit score. Total costs. legal standing.
Comparison of CIBIL score impact
A restructured account is reported to CIBIL as "Restructured," which has a moderate impact on your credit score. Lenders view restructuring as a good-faith attempt to repay. Meaning you are not blacklisted from the money system. In contrast. Debt closure results in a "Settled" remark. This acts as a major red flag on your report. Signaling that the bank accepted a loss. It can lower your credit score by 50 to 100+ points and restrict access to fresh credit for up to seven years.
Comparison of overall rates cost
Restructuring can be more expensive in terms of total rates outflow because you continue to pay rates (albeit at a lower rate) over an extended period. Debt closure fully freezes and eliminates future rates. Allowing you to pay a single discounted amount to close the debt. For example. If you owe ₹2,00,000. Restructuring might cost you ₹2,60,000 over 3 years in EMIs. Whereas closure could allow you to close the account for a lump sum of ₹80,000.
Comparison of legal claims safety
Restructuring protects you from harsh agents activities and legal steps. Provided you pay your new EMIs on time. Lenders stop all calls actions once the restructuring contract is signed. Debt closure talks. Yet. Often occur after a default has already happened. This means you may face intense claims pressure and legal notices until the formal closure note is signed and the lump sum is paid.
Which debt relief option is best?
The best debt relief option depends fully on your current liquidity and cash flow. Restructuring is ideal for clients who have a stable income but require lower monthly payouts. whereas debt closure is the most practical choice for those facing long-term money hardships who can accumulate a lump sum to wipe out the debt fully.
Making the right decision requires an honest evaluation of your money resources. There is no one-size-fits-all solution. what works for a salaried experts facing a temporary pay cut may not work for an entrepreneur whose firm has collapsed.
When to choose card closure
You should choose debt closure if you have lost your primary source of income. Have no fast prospects of landing a new job. are dealing with a severe medical crisis that drains your monthly earnings. In these scenarios. Committing to new monthly EMIs through restructuring is risky. If you can borrow from family or liquidate a small asset to gather a lump sum. Closure is the most effective way to eliminate the debt fully and stop claims threats.
When to choose loan restructuring
You should choose loan restructuring if you have a stable job or a steady firm income but are temporarily overwhelmed by high-rates rates. If your debt-to-income ratio has temporarily exceeded 50%. Restructuring allows you to convert credit card balances into manageable. Lower-rates EMIs. This keeps your CIBIL score intact and prevents banks from initiating claims or legal actions against you.
How do you apply for relief?
Applying for debt relief requires presenting a formal hardship case to your credit card issuer. Clients must contact the credit card bank's claims or grievance department. Submit proof of money distress like job loss or medical letters. settle terms that culminate in a formal written approval or a deal sanction letter.
Navigating banking bureaucracy can be challenging. Whether you are aiming to restructure your cards or settle a closure. Following a structured process is essential to protect your rights. Lenders look for clear evidence of distress before approving any modifications to the original contract.
Step 1: Perform a Hardship and money Audit
Gather all your credit card statements to calculate the total unpaid balance. Rates rates. fines. Papers your monthly income. Living expenses. prepare a written explanation of your money hardship. Gather supporting evidence. Such as end letters. Salary reduction slips. hospital bills.
Step 2: Submit a Formal Proposal to the Bank
Do not avoid your bank's contact. Write a formal email or letter to the credit card division's customer service and copy the Grievance Redressal head. State clearly whether you are applying for a structured loan conversion (restructuring) or a One-Time closure (OTS). Attaching your hardship evidence.
Step 3: Secure and check the Written Sanction Letter
If the bank accepts your proposal. They will issue a formal sanction letter. Check that the letter is on the bank's valid letterhead and contains the exact settle amount. Payment schedule. terms. Never make any payments based on verbal commitments from agents. Pay the agreed amount straight to the bank's system and obtain your No Dues letter.
papers checklist for relief programs
Ensure you have the following papers ready before initiating contact with your lender:
- Latest 6 months' bank statements showing your primary income.
- Salary slips for the last 3 months or audited profit & loss statements for self-employed individuals.
- Copy of job resignation letter. End notice. proof of firm closure.
- Medical letters or hospital discharge summaries showing significant health expenses.
- Formal legal notices or summons received from the bank (if default has already occurred).
Client Reviews
"My credit card debt was piling up. I was confused between converting it to EMIs or settling. I decided to choose debt closure with CredSettle. Got a 60% waiver and cleared the balance in a lump sum. The mental relief is unmatched!"
- Vikram Joshi, Pune
"I chose loan restructuring with my bank since I still had a monthly salary. It lowered my rates rate. it extended my loan for 36 months. Restructuring is good if you want to save your credit score. closure is much faster if you have the lump sum."
- Meenakshi Iyer, Chennai
"CredSettle explained both options clearly. They showed me that closure was the only realistic exit since my firm had closed. SettleLoans only offered flat advice. CredSettle's structured program guided me till I got my NOC."
- Ankur Saxena, Noida
Frequently Asked Questions
Does loan restructuring damage my CIBIL score as much as debt settlement?
No. Loan restructuring damages your CIBIL score less than debt closure. Restructuring is reported to CIBIL as "Restructured," which indicates a modification of terms but shows active payment. Debt closure is reported as "Settled," indicating a loss to the bank. which causes a larger drop and prevents new loans for 2-3 years.
Can I request loan restructuring for an active credit card in India?
Yes. You can request loan restructuring for an active credit card in India by contacting your bank's credit card division before default. Lenders like SBI or HDFC can convert your outstanding credit card balance into structured personal loan EMIs with a fixed tenure of 12 to 48 months.
How much discount can I expect in a credit card debt settlement?
You can expect a discount of 30% to 70% of the total unpaid credit card balance during a debt closure. The exact discount depends on the bank's policies, the age of the default, and your ability to prove genuine financial hardship, such as medical issues or unemployment.
What happens if I default on restructured credit card EMIs?
Defaulting on restructured credit card EMIs will result in the bank canceling the restructuring pacts and reinstating the original high rates rates and fine charges. The bank will initiate standard agents actions. your CIBIL score will drop rapidly due to active payment default reporting.
Are there tax implications for credit card debt settlement in India?
Yes. There are tax implications for credit card debt closure in India. Under Section 194R of the Income Tax Act. The bank may report the waived debt amount as taxable income under the clients's PAN, which could require you to pay tax on the forgiven principal amount.
Can a bank refuse my request for credit card restructuring?
Yes. A bank can refuse your request for credit card restructuring. Restructuring is a discretionary relief option. Not a legal right. Lenders will evaluate your payment history. Current income statements. the genuineness of your money hardship before deciding to approve or reject your application.
Is debt settlement better than restructuring if I have no source of income?
Yes. Debt closure is better than restructuring if you have no source of income. Restructuring requires a steady monthly income to pay the newly formed EMIs. Closure allows you to resolve the debt fully in a single lump sum payment. Ending your risk without the need for future monthly cash flows.
How long does the credit card restructuring process take?
The credit card restructuring process typically takes 15 to 45 days. You must submit your income details and sign the new payment pacts. During this period. The bank will freeze your credit card transactions and calculate the new monthly EMI schedule based on the restructured rates rate.
Can I settle my restructured credit card loan later?
Yes. You can settle your restructured credit card loan later if your money case worsens and you default on the restructured EMIs. The bank will classify the restructured account as a Non-Performing Asset (NPA) after 90 days of non-payment. Making it eligible for standard one-time closure talks.
Does the RBI regulate both debt settlement and loan restructuring?
Yes. The RBI regulates both debt closure and loan restructuring through its fair practice codes and relief frameworks. Lenders must follow Board-approved policies for restructuring and deal closures. Making sure that debt calls actions are conducted within legal limits and that agents avoid harsh threats.
Find Your Debt Relief Solution Today
Confused between settling your cards or restructuring your debt? Contact our expert talks team today for a free debt audit and claim your money freedom.
Start Your Free Debt Evaluation